2025年FRM金融风险管理师《FRM二级》模拟试卷二
一、单选题
根据题目描述选择正确答案
1.
Deposit accounts are the number one source of funds at most banks. Important indicators of management’s effectiveness are whether or not funds deposited by the public have been raised at the lowest possible cost and whether sufficient deposits are available to fund all those loans and projects management wishes to pursue. There are plenty of differences between transaction and non-transaction deposit types. Regarding transaction versus non-transaction deposit types, which of the following statements is TRUE?
参考答案B
解析Answers: B:本题考查的是银行存款负债的辨析。对于A选项,大额存单(Certificates of deposit )属于非交易存款,而并非是交易存款。因此A选项描述错误,为错误选项。对于B选项,NOW账户属于付息的交易存款账户,并且NOW账户只能是给个人或者非盈利机构开立的存款账户。B选项描述正确,为正确选项。对于C选项,核心存款(core deposit)是一种具有粘性的存款,是一种稳定且可预测的存款资金基础,通常由家庭存款和小型企业存款构成,包括交易类账户和非交易类账户,对市场利率变动不太敏感。 然而,核心存款不是监管资本(一级资本是银行股权资金,存款是负债资金)。因此,C选项描述错误,为错误选项。对于D选项,与交易存款相比,非交易存款通常能给银行提供一个更稳定的资金来源。因为非交易存款往往是一些储蓄存款,粘性比交易存款高。因此,D选项描述错误,为错误选项。
2.
参考答案B
解析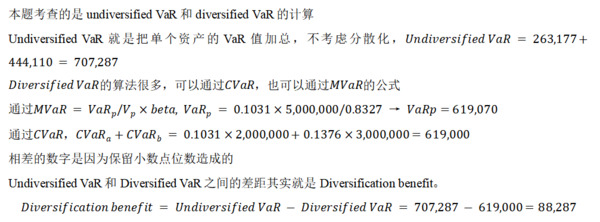
3.
Togashi Yoshihiro and Takeuchi Naoko are students of Waseda University, majoring in Financial Engineering. They had just finished a fixed income course, which addressed the difficult concepts about MBS/ABS products, structured products, and the history of 2007-2008 financial crisis. They learnt that several parties played critical roles in the crisis. These parties were having some sort of frictions with each other, which contributed to the crisis. Takeuchi disagreed with Togashi on the interpretation of these complex frictions, especially the frictions between arranger, credit rating agencies (CRA) and investor. She claimed:“Firstly, the role of arranger is played by special purpose vehicles rather than commercial banks.Secondly, the arranger has more information about the quality of the mortgage loans than third parties so they may securitize bad loans and keep the good ones themselves. This phenomenon is called information asymmetry rather than predatory lending.Finally, you said that credit rating agencies were totally innocent, but in my opinion, credit rating agencies had honest errors. They didn’t pay enough attention on rapid financial innovation and complexity, and lost the independence of rating agencies due to the so-called issuer-pay fee structure.”How many statements that Takeuchi made is(are) most likely incorrect?
参考答案D
解析P2B2 – friction in subprime crisis此题考查的是次贷危机7大摩擦中的有关SPV, 评级机构和投资者之间的摩擦。Takeuchi这三句话都是正确的。Arranger指的是SPV而非商业银行。其次,SPV和评级机构比起来,拥有更多的信息优势,知道哪些底层资产是好的,哪些是不好的,这种信息优势造就了信息不对称性。最后,评级机构在整个次贷危机中并非无辜的,在资产证券化的热潮中,他们热衷于给与很多资产证券化产品高评级,没有仔细研究和测度复杂的结构化产品的风险,当然,其中的发行者付费模式也使得他们的评级客观性令人生疑。
4.
Michael S. Dunham and his colleague Theresa L. Gutman is debating on the performance of debt and equity of Company Dragon-Fruit under different circumstances using the Merton model. Company Dragon-Fruit has two debt issues outstanding: a senior debt and a subordinate debt. Both of them agree that the current market environment is good for Dragon-Fruit, and the company is expanding rapidly. Under the Merton model framework, Michael claims that the subordinate debt will perform like equity and since firm volatility increases at the moment holding other factors constant, the value of subordinate debt will decrease. Theresa argues that the subordinate debt will perform like senior debt, and when interest rate increases holding other factors constant, the value of subordinate debt will increase. Which of these two statements is/are most likely correct?
参考答案D
解析P2B2 – Merton model subordinated debt首先在行情好的时候,公司快速扩张,价值应该会比较高。公司价值比较高的时候,次级债表现得像高级债,因为都很安全。所以Michael的前半句错了,Theresa的前半句对。根据莫顿模型,波动率上涨时,高级债价值下降,所以次级债价值下降,Michael的后半句是对的。利率上涨时,高级债的价值下降, 所以次级债价值下降,Theresa的后半句是错的。所以两个人说的话综合来看都是错的。
5.
Analyst Mary wants to improve his short-term interest rate simulation by employing Model 2. The time step in his model is one month, dt = 1/12. His Model 2 also makes three assumptions.1) The initial or current (t0) short-term rate is equal to 3.00%.2) The annual basis-point volatility is 220 basis points.3) The annual drift is +100 basis points.In the first step of his first trial, the random uniform variable is 0.0793 such that, via inverse transformation, the associated random standard normal value is -1.410[NORM.S.INV(7.93%) = -1.410. ]What level does the rate evolve in the first month, r(1/12)?
参考答案B
解析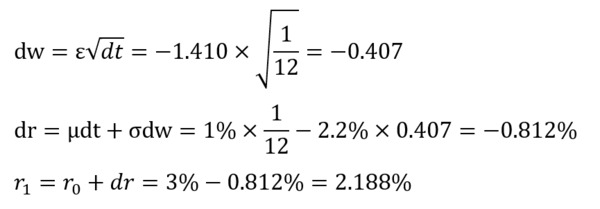
6.
A risk analyst expects that the volatility of the market will surge compared to the historical standard deviations of the market. The risk analyst compares several historical simulation methods to choose the best one for calculating VaR and makes the following statements.Statement I: Non-parametric method is not subject to covariance matrix estimation.Statement II: Non-parametric approaches are more intuitive and conceptually simple than parametric methods.Statement III: Semi-parametric approaches are better than non-parametric methods when incorporating current market volatility estimates instead of using historical data directly.Which of the following statement is most likely correct?
参考答案D
解析该题主要考点为非参法和参数的优缺点比较。非参法简单直观,不用假设分布,而参数法需要对分布的各种参数进行估计,各有优缺点。对于statement I,非参法不需要估算协方差矩阵。该选项描述正确。对于statement II,非参法相比较参数法,更直观更易于理解。该选项描述正确。对于statement III,半参法可以将当下对于市场波动率的预期加入到模型中,而不是直接采用历史数据。尤其是在当下市场波动率预计会高于历史波动率的时候,就更加凸显了半参法的优势。该选项描述正确。因此,该题正确选项为D。
7.
An investor who is based and reported on the British Pound wants to create a short position on the correlation among component stocks in S&P 500 index. According to the historical data, the country’s equity market and quoted currency value usually moves inversely. Which of the following descriptions about the strategies is most likely correct?
参考答案C
解析首先要做空股票市场指数的相关性,那么使用以指数为标的的期权来做空,同时做多一组以指数中的股票为标的的期权,这样就是对冲所有其他因子敞口,当指数相关性下降时,策略获得收益。这类策略是既可以使用call,又可以使用put的,因为无论用哪种期权,它们的delta敞口都被对冲掉了。所得收益是以美元报示的,要换回英镑,题干有一句话,美元指数和美元价值的关系从历史来看是反向变动的,这句话是用来迷惑的,因为前一个策略的敞口和股票市场方向性变动无关,只和股票相关性有关,而股票相关性和美元价值的关系并没有提及,那就无法判断使用quanto call这个工具是否有利,而long quanto call是要支付期权费的,成本较高。既然成本更高,但收益又没有明确证据证明是较高的,那么直接使用利润结算出来时的即期汇率将美元收益换回即可。
8.
After the 2007–2009 global financial crisis, regulation about the over-the-counter (OTC) derivative market was tightened in order to reduce the systematic risk of overall markets. Thus, a set of regulation reform measures according to Basel III standard was taken to improve the soundness and robustness of the entire financial markets. Based on the Regulation Reform of the Basel III Standard, which of the following statements is least likely correct?
参考答案A
解析金融危机后的监管改革,互换主要通过CCP进行清算,而非通过双边清算。因此,选项A描述错误,符合题意,为正确选项。 对于选项B,Basel III改革后,大部分衍生品应通过CCP进行清算。因此,该选项描述正确,不符合题意,为错误选项。 对于选项C,对于双边清算的衍生品,保证金是强制性要求。因此,该选项描述正确,不符合题意,为错误选项。 对于选项D,按照Basel III标准进行监管改革的目标之一是提高整个衍生品市场信息披露的透明性。因此,该选项描述正确,不符合题意,为错误选项。
9.
Illiquidity can arise due to the following market imperfections: Clientèle effects and participation costs, transaction costs, search frictions, asymmetric information, price impact, or funding constraints. Therefore, we can characterize the effects of these imperfections as "illiquidity." Concerning the characteristics of illiquid markets, which of the following statements is true?
参考答案A
解析Answers: A. :本题考查的是非流动性资产的辨析对于A选项,流动性比较好的市场,也可能会出现流动性不足的时候,比如在金融次贷危机的时候,MBS市场就是从流动性比较好,变成了流动性不好的市场。因此A选项描述正确,为正确选项。对于B选项,对于大多数个人投资者,他们的财富中,占比权重大的是非流动性资产,而不是流动性资产,比如,大部分个人投资者持有的房产之类的非流动性资产就是占他们财富的一大部分。因此B选项描述错误,为错误选项。对于C选项,大部分资产类别都是属于非流动性资产,并不是流动性资产。因此非流动性资产的市场是非常大的。因此C选项描述错误,为错误选项。对于D选项,现实中的交易成本,搜索摩擦,信息不对称,价格影响,融资限制等问题依旧存在,技术的发展到目前为止,并没有解决这些问题。因此D选项描述错误,为错误选项。
10.
Golden Wind (GW) hedge fund is a mid-sized hedge fund which AUM (asset under management) is around $200 million. GWfocuses on fixed-income investment and fixed-income relative value strategies. In order to enhance the flexibility of investment and hedge credit risk, GW has various OTC derivative positions, such as credit default swap, credit-linked notes, forward, interest rate options, etc. The private-issued bond of Stone Ocean Co. is a large position that GW hedge fund allocates recently. Stone Ocean Co. is a mining company which is the industry leader and has the largest market share. It is to be noted that the fluctuations of commodity market and funding liquidity dry up would be crucial for mining industry. Stone Ocean Co. is an end user in OTC derivative markets to hedge positions and having various line of credit will be vital for its operations. Ripple derivative company is the major counterparty of Stone Ocean Co. for OTC derivatives and there is a netting scheme and two-way CSA between Ripple derivative company and Stone Ocean Co.Tom Feng, FRM, a senior portfolio manager at GW hedge fund, focuses on the bond position of Stone Ocean Co. He hedges these bonds with a short position in Stone Ocean Co.’s equity because Feng thinks that unfavorable information will negatively affect both equity price and bond price. Unfortunately, the value of the debt falls, but the value of equity does not fall as expected, so Feng and his fund make a huge loss. Based on Merton’s debt valuation model,consider the following circumstances:I. Interest rates increased.II. Volatility of firm value fell.III. Volatility of firm value increased.IV. A liquidity crisis increased the liquidity component of the credit spreads.Which circumstances according to Merton Model are possible explanations for why Feng’s hedge does not work out?
参考答案B
解析P2B2-Merton model本题考查的是Merton model中,影响股票和债券价值的不同因素。基金经理持有债券多头,通过股票空头来对冲。但现在发生了债券价格下跌,但股票价格并未下跌的情况。Statement I, 利率上升,根据Merton Model,股票价格可以被看做是看涨期权,利率上升看涨期权价值上身,但利率上升会带来债券价值下降,利率上升可以解释为何债券价值下降但股票价值却上升。Statement I符合题意,为正确原因之一。Statement II,公司价值波动下降,根据Merton Model,股票价格可以被看做是看涨期权,标的资产波动率下降,看涨期权价值下降,但站在债权人角度,公司价值平稳,会带来债券价值的上升,股票价值下降,债券价值上升,不符合题目中描述的场景。Statement II不符合题意。Statement III, 公司价值波动上升,根据Merton Model,股票价格可以被看做是看涨期权,标的资产波动率上升,看涨期权价值上升,但站在债权人角度,不希望发行人公司价值面临巨大波动,会带来债券价值的下降,公司价值波动上升可以解释为何债券价值下降但股票价值却上升。Statement III符合题意,为正确原因之一。Statement IV,Merton Model在假设中,不考虑流动性调整,依据此模型做出分析无法从流动性的角度来进行考量。Statemtn IV不符合题意。
11.
Golden Wind (GW) hedge fund is a mid-sized hedge fund which AUM (asset under management) is around $200 million. GWfocuses on fixed-income investment and fixed-income relative value strategies. In order to enhance the flexibility of investment and hedge credit risk, GW has various OTC derivative positions, such as credit default swap, credit-linked notes, forward, interest rate options, etc. The private-issued bond of Stone Ocean Co. is a large position that GW hedge fund allocates recently. Stone Ocean Co. is a mining company which is the industry leader and has the largest market share. It is to be noted that the fluctuations of commodity market and funding liquidity dry up would be crucial for mining industry. Stone Ocean Co. is an end user in OTC derivative markets to hedge positions and having various line of credit will be vital for its operations. Ripple derivative company is the major counterparty of Stone Ocean Co. for OTC derivatives and there is a netting scheme and two-way CSA between Ripple derivative company and Stone Ocean Co.One of the largest markets for Stone Ocean Co. is European market that 23.4% gross income is from trading with European manufacturers. Not only commodity price volatility, but also currency risk is a large risk for Stone Ocean Co.’s operation. In order to hedge the currency risk and market risk, Stone Ocean Co. has large number of OTC positions with Ripple derivative trading company, an American company. Which one of the following transactions will be a wrong-way exposure for Ripple derivative trading company?
参考答案A
解析P2B2- WWRRWR本题考查的是错向风险和正向风险的辨析。此题站在Ripple derivative trading company的角度分析交易对手信用风险。A选项,Stone Ocean Co.为远期多头,Ripple即为远期空头,看跌欧元。Ripple敞口上身,EUR贬值,交易对手Stone Ocean Co.的违约概率上升,为WWR,故A选项为正确选项。B选项,Stone Ocean Co.为期权的买方,Ripple即为期权卖方,期权卖方不存在信用敞口,无需讨论WWR or RWR,故为错误选项。C选项,Stone Ocean Co.为大宗互换的标的收益换出方,Ripple即为标的收益换入方,当金价上升,Ripple敞口上升,此时Stone Ocean Co.作为开采商,收益更高,更加不容易违约,为RWR,故为错误选项。D选项,Stone Ocean Co.为期权的买方,Ripple即为期权卖方,期权卖方不存在信用敞口,无需讨论WWR or RWR,故为错误选项。
12.
Golden Wind (GW) hedge fund is a mid-sized hedge fund which AUM (asset under management) is around $200 million. GWfocuses on fixed-income investment and fixed-income relative value strategies. In order to enhance the flexibility of investment and hedge credit risk, GW has various OTC derivative positions, such as credit default swap, credit-linked notes, forward, interest rate options, etc. The private-issued bond of Stone Ocean Co. is a large position that GW hedge fund allocates recently. Stone Ocean Co. is a mining company which is the industry leader and has the largest market share. It is to be noted that the fluctuations of commodity market and funding liquidity dry up would be crucial for mining industry. Stone Ocean Co. is an end user in OTC derivative markets to hedge positions and having various line of credit will be vital for its operations. Ripple derivative company is the major counterparty of Stone Ocean Co. for OTC derivatives and there is a netting scheme and two-way CSA between Ripple derivative company and Stone Ocean Co.There is a sudden shock to the Stone Ocean Co. The accident death of CEO leads the operation and corporate governance into chaos. In addition, the breakout of Covid-XX makes the price of commodity sharply volatile. Stone Ocean Co. falls to make payments in one of the OTC derivative contracts with Ripple derivative trading company. Which of the following statements regarding counterparty risk and netting is correct?
参考答案B
解析P2B2 – close-out netting本题考查的是和netting相关的概念。A选项,Stone Ocean Co.是违约一方,理应Ripple derivative trading company启动close-out netting,防止风险扩散,而非违约一方要求close-out netting,故A选项描述错误,不符合题意。B选项,netting合约存在于Ripple derivative trading company和Stone Ocean Co.之间,可以保护Ripple,使其终止和Stone Ocean的其他合约,并且进行净额结算。但这会侵害到GW的利益,GW买了Stone Ocean的私募债,是Stone Ocean的债券人,Close-out netting会跳过破产清算程序,先行结算,故B选项描述正确,符合题意,为正确选项。C选项,netting合约存在于Ripple derivative trading company和Stone Ocean Co.之间,这会侵害到GW的利益,GW买了Stone Ocean的私募债,是Stone Ocean的债券人,Close-out netting会跳过破产清算程序,先行结算,故C选项描述不正确,不符合题意。D选项,CCP逐日盯市中使用的并非close-out netting,close-out netting仅适用于一方发生违约的情况下,故D选项描述不正确,不符合题意。
13.
Golden Wind (GW) hedge fund is a mid-sized hedge fund which AUM (asset under management) is around $200 million. GWfocuses on fixed-income investment and fixed-income relative value strategies. In order to enhance the flexibility of investment and hedge credit risk, GW has various OTC derivative positions, such as credit default swap, credit-linked notes, forward, interest rate options, etc. The private-issued bond of Stone Ocean Co. is a large position that GW hedge fund allocates recently. Stone Ocean Co. is a mining company which is the industry leader and has the largest market share. It is to be noted that the fluctuations of commodity market and funding liquidity dry up would be crucial for mining industry. Stone Ocean Co. is an end user in OTC derivative markets to hedge positions and having various line of credit will be vital for its operations. Ripple derivative company is the major counterparty of Stone Ocean Co. for OTC derivatives and there is a netting scheme and two-way CSA between Ripple derivative company and Stone Ocean Co.Jorge T. Sisemore, FRM, a risk analyst for GW hedge fund, is currently looking into different alternatives and credit derivatives to invest or to transfer credit risk, rather than holding his pure fixed-income portfolio unchanged. Moody’s has recently lowered the credit ratings of several Jorge’s holdings. GW hedge fund’s CIO, Dawn P. Haskins, is concerning Jorge’s holdings will be affected heavily and agrees on Jorge’s decision to hedge the current exposures using three potential derivatives: total return swap, credit default swap and credit-linked notes. During Jorge’s discussion with his colleagues regarding which derivatives to invest in, he makes the following statements:Statement I: A total return swap is equivalent to a synthetic long position in the underlying asset for the credit risk seller.Statement II: Total return swap receiver bears all risks, including credit risk and market risk.Statement III: If Jorge wants to transfer the credit risk of the holdings, he could either buy credit default swap or buy credit-linked notes to buy credit protection and sell credit risk.Which of the statements made by Jorge is/are most likely correct?
参考答案A
解析P2B2 – credit derivatives对于Statement I,总收益互换相当于合成了资产的多头,合成一方为信用风险的买入方而非卖出方,Statement I描述错误,不符合题意。对于Statement II,总收益互换的换入方承担了底层资产的所有风险,包括信用风险和市场风险,Statement II描述正确,符合题意。对于Statement III,转嫁信用风险,可以通过买CDS或者卖CLN来转嫁,Statement III描述错误,不符合题意。故最终选择A选项。
14.
Culture is an unreal and sensitive topic in a corporation. Below are statements regarding definition and execution of culture. Which statement is wrong?
参考答案D
解析风险文化是公司文化的一个组成元素,风险文化是子文化、亚文化(subculture)。文化不容易被量化。因此,D选项描述错误,符合题意,为正确选项。对于选项A,文化既包括有形的职场行为(conducts)和职场外行为(behaviors),也包括无形的价值观和道德观。因此,该选项描述正确,不符合题意,为错误选项。对于选项B,文化可通过机制予以传递,通过职场行为进行塑造。因此,该选项描述正确,不符合题意,为错误选项。对于选项C,文化可通过一些关键方面予以执行和落实,比如高级管理者的责任和治理、业绩管理和激励、员工发展和晋升、有效的三道防线。
15.
A new fund manager assistant has been asked to collect the information about creating alpha relative to a benchmark by making bets that deviate from that benchmark. Grinold’s fundamental law of active management states that the maximum information ratio can be attainable. Which of the following statement about Grinold’s fundamental law is correct?
参考答案A
解析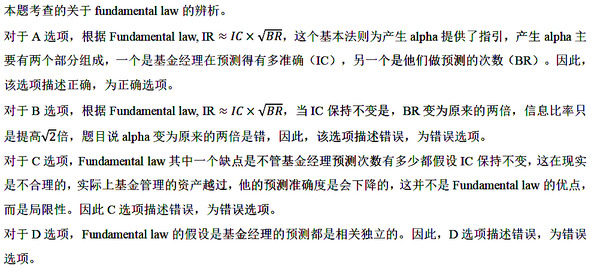
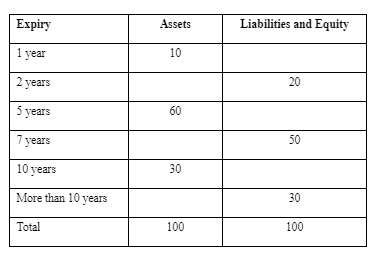
16.
An internal auditor at a large bank is reviewing the bank’s economic capital framework to ensure that it meets best practices. The auditor identifies deficiencies in the bank’s governance framework as well as the process used to determine the firm-wide economic capital and asks the CRO to suggest corrective actions that conform with best practices. Which of the following actions should the CRO recommend?
参考答案C
解析在银行的经济资本政策中,将一整套升级程序包含到银行的应急计划中是CRO应给到的推荐。因此,正确选项为C。对于选项A,董事会而非业务部门经理有责任挑战资本模型的假设,且董事会对模型最最终批准。因此,该选项错误。对于选项B,将不同风险的经济资本金做加总的做法忽略了风险之间可能存在的分散化好处(diversification benefit),该做法不符合ERM的视角,不是CRO的推荐做法。因此,该选项错误。对于选项D,不鼓励使用第三方服务商(third-party vendor)的开发的模型,但可以使用第三方服务商提供的宏观经济情景并对该情景做调整用于经济资本模型的压力测试。因此,该选项错误。
17.
Enterprise risk management (ERM) framework could supply a useful and effective view on the risk-return tradeoff for firms, especially the large and diversified conglomerates. In details, firms need to distinguish risks which would be retained and risks which would be transferred. Which of the following statements is/are correct?I. Management should retain strategic and business risks in which the company has a comparative advantage but diversify risks that can be hedged inexpensively through the capital markets.II. When proposing new projects, business unit managers must evaluate all major risks in the context of the marginal impact of the project on the firm’s total risk.
参考答案C
解析对于陈述I,公司管理层应当保留具有比较优势领域的业务和战略风险,针对不想要的风险,公司可以通过资本市场以划算的成本予以对冲。因此,该陈述正确。对于陈述II,在提议新项目时,业务部门经理应当从项目对公司总风险的边际贡献角度进行评估,即评估做了该项目后给公司增加了多少风险。因此,该陈述正确。综上所述,陈述I和陈述II均正确,因此,正确选项为C。
18.
Too many stress tests can hide the risk of a portfolio, but a fair number of stresses is important to develop a comprehensive view of the risks in the portfolio. More integrated stress tests can be generated by combining the credit risk view with the loan portfolio, or the market risk view of counterparty credit risk can be combined with the trading book. Which of the following statements about stress test for counterparty exposures is most likely correct?Ⅰ. A financial institution can stress the probability of default similarly to the loan case by stressing the probability of default or the variables that affect probability of default, including company balance-sheet values, macroeconomic indicators and values of financial instruments.Ⅱ. In addition to considering just current exposure, the financial institution must consider including the probability of default over the time horizon and the EPE in its stress-test framework.Ⅲ. To capture the full impact of various scenarios on CVA profit and loss, a financial institution should include the liability side effects in the stress as well.
参考答案A
解析本题考查交易对手风险的压力测试。对于Statement Ⅰ,对纯贷款组合的违约概率进行压力测试时,金融机构可以通过模拟极端情况下的各种变量,包括公司资产负债表价值、宏观经济指标和金融工具价值等指标,来模拟极端情况下的违约概率。因此该陈述正确。对于Statement Ⅱ,压力情况下,衍生产品的敞口变化迅速,所以需要同时针对违约概率和预期正敞口进行测试,并且需要充分考虑违约概率和预期正敞口之间的相关性以及错向风险问题。因此该陈述正确。对于Statement Ⅲ,为了全面反映压力状况下的交易对手风险,除了对交易对手的CVA进行压力测试外,金融机构还应在压力测试中包含自身信用风险的变化情况,即对自身的DVA进行压力测试。因此该陈述正确。因此,Statement Ⅰ,Ⅱ和Ⅲ均描述正确,正确选项为A。
19.
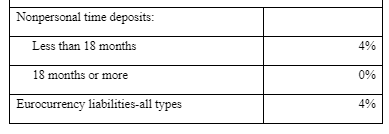
Michael is estimating the total financing cost included deposit and non-deposit funds. By reviewing the bank’s past expense, he concluded that the following table: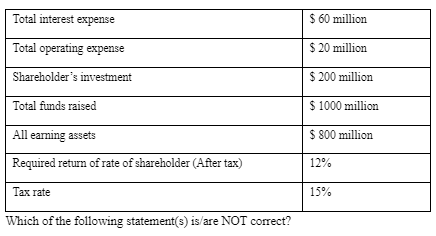
参考答案D
解析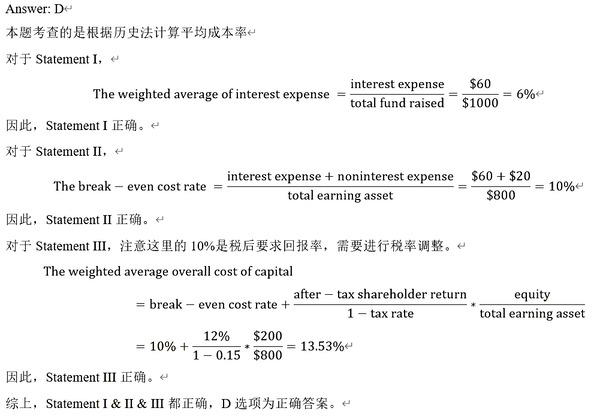
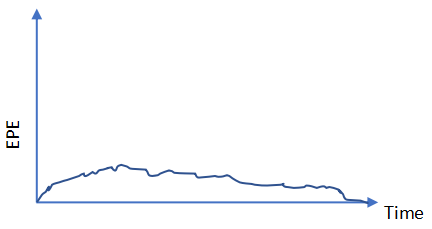
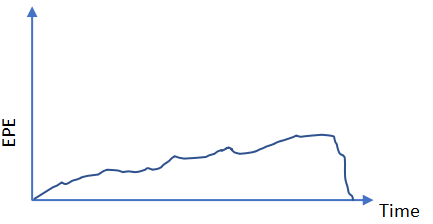
20.
Rosenfeld Savings is attempting to determine its liquidity requirement. The bank has classified its checking, savings, and nonperson time deposits into three categories: hot money, vulnerable, and stable (aka, core) funds: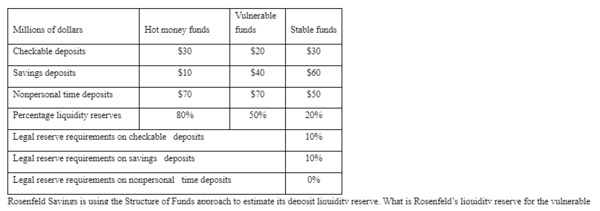

参考答案C
解析Answers: C本题考查的是存款准备金的计算。Vulnerable funds的流动性准备金计算如下:50.0%× [$20.0*(1 - 10%) + $40.0×(1 - 10%) + $70.0] = $62.0 million因此,C选项为正确选项。
21.
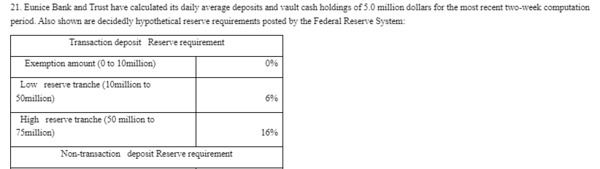
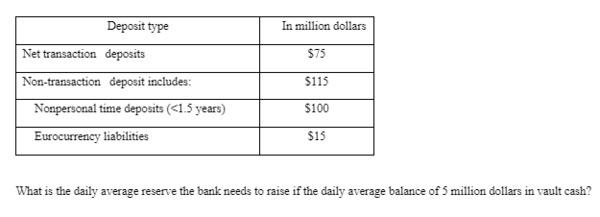
参考答案A
解析Answer: A :本题考查银行法定存款准备金计算。总法定存款准备金涉及两个部分的计算,一个是交易存款,另一个是非交易存款。由题目给出表格可知,净交易存款共有75million,分为三个准备金级别进行缴纳。第一个豁免部分10million,不需要计算准备金。第二个部分是低准备金部分是(50-10)million,准备金缴纳比例6%。第三部分高准备金部分是(75-50)million,准备金缴纳比例16%。非交易存款共有115million美元,分成两个类型:第一个是非个人定期存款,存款时间低于1.5年,余额是100million,准备金缴纳比例4%。第二是欧洲货币负债是15million,准备金缴纳比例4%。因此,14天存款准备金计算周期的准备金计算额是:The Bank's Total Required Legal Reserve = ($50 - $10) × 6.0% + ($75 - $50) × 16% + ($100 + 15) ×4.0% = $11.0 million但由于该银行的库存现金是5 million美元,因此,该银行需要额外筹措的准备金是:Daily Average Reserve the bank needs to raise = $11.0 - $5.0 = $6.0 million因此,A选项为正确答案。
22.
SkyLine Airways has a defined benefit pension scheme with assets of $165 million and liability of $150 million. The annual growth of the liabilities is expected to be 4.5% with 2.4% volatility. The annual return on the pension assets has an expected value of 7.8% with 12% volatility. The correlation between asset return and liability growth is 0.35. What is the 95% surplus at risk for SkyLine?
参考答案A
解析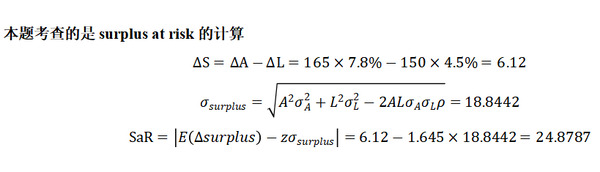
23.
At the initiation of a repurchase agreement (repo), Bank Holly sells a security to Bank Wood for settlement on June 1st, 2022 at an invoice price of USD 180.0 million. At the same time, Bank Holly agrees to repurchase the security three months later, for settlement on September 1st, 2022, at a purchase price equal to the original invoice price plus interest at a repo rate of 0.90%. Using the actual/360 convention of most money market instruments, which is nearest to the repurchase price?
参考答案C
解析Answer: C:本题考查的是回购交易的回购金额的计算。回购期初,出售了一个证券,借入180,000,000资金,按照actual/360的天数计算惯例,2022年6月1日到2022年9月1日,共计92天。因此,回购证券的金额为:180,000,000 × (1 + 0.0090 ×92/360)=$180,414,000 因此,C选项为正确答案。
24.
A commercial bank constructed a backtest of 95% daily VaR and observed 24 exceptions (the number of days where the daily P&L loss exceeded the VaR) over last 252 trading days. Normal distribution is applied for the purposes of model verification. What is the result of hypothesis testing for the model under a 90% two-tail test? And what is the most exceptions that can be observed to make sure that the bank can accept the VaR model under 95% two-tail test?
参考答案C
解析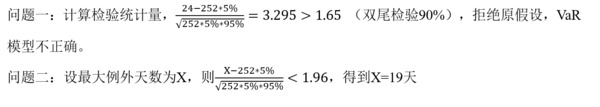
25.
Owing to the global financial crisis in 2008, the Basel Committee amended the market risk framework and added an extra stressed VaR requirement. Assume a bank used the internal model approach for market risk charge and had developed the following risk measures (in USD million) for the trading book positions: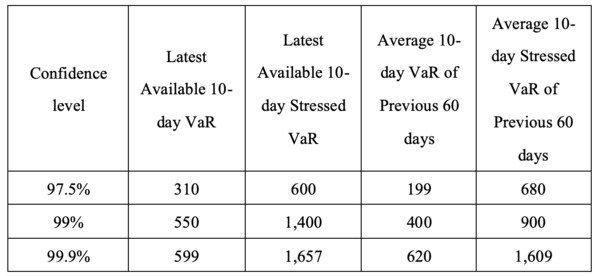 The regulators have set the multiplication factors values to three for both VaR and Stressed VaR. The capital charge for general market risk is closest to:
参考答案B
解析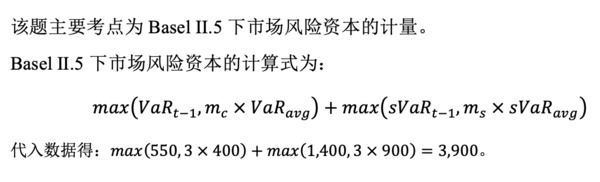
26.
The single-factor model, since it is a structural model, emphasizes the correlation between the fundamental driver of default of different firms. Default correlation in that model depends on how closely firms are tied to the broader economy. Which of the following statements about the single factor model is least likely correct?
参考答案D
解析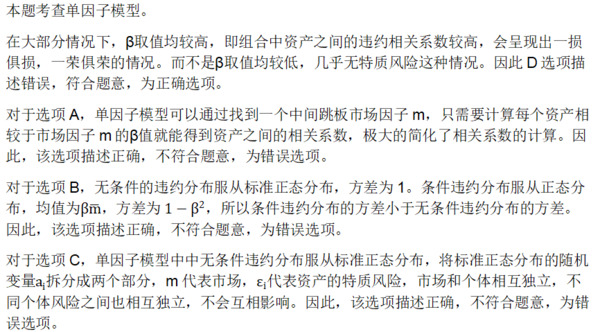
27.
When we apply the Gaussian copula utilized for financial model, which of the following statements is least accurate?
参考答案D
解析D选项描述错误,高斯连结函数同样可以运用于信用风险分析,但是事实证明效果不是特别理想,因为信用风险的尾部损失要比高斯正态的假设大得多,而且分布规律也不是特别接近。最初高斯连结的运用场景也是从联合违约概率问题开始的。A选项描述正确,资产的尾部相关性会突然暴增,导致分散化失败。B选项描述正确,正态分布假设过强,对于资产价格和结构化工具的适用性存疑。C选项描述正确,高斯连结是静态化处理数据的方法,就是把两组收益数据拿来刻画散点图的方式,没有假设随机波动过程。类似标准差这种算法,没有办法和GARCH这种动态模型比拟。
28.
The staff at Umbrella Street Bank, which is a commercial bank, produces several liquidity risk reports on a daily, weekly, monthly, and quarterly basis. Among these liquidity risk reports is a deposit tracker report. Among the following metrics, which is most likely to appear in their deposit tracker report?
参考答案B
解析Answer: B本题考查的是流动性风险报告的辨析。存款跟踪报告:存款跟踪报告是当前存款规模以及对未来存款水平的预测的报告,并且它提供了短期内存贷比率的相关数据,而存贷比率是银行一个关键的管理流动性比率。对于A选项,在存款跟踪报告中,不仅有当前的存款规模,而且还预测了未来的存款水平,因此A选项描述正确,为正确选项。对于B选项,存款跟踪报告的确提供了短期贷款与存款(LTD)比率的数据,而短期贷款与存款(LTD)比率(当前和预测)的下限通常为120%是不正确,因为存贷比率过高说明,银行需要通过存款以外的负债来支持贷款业务,这种情景下,银行流动性容易出现问题,更不可能说存贷比率的下限是120%。因此,B选项不符合题意,为错误选项。对于C选项,普通股的市净率(当前和预测)与投资者传达的目标并不会写在存款跟踪报告上面。因此,C选项不符合题意,为错误选项。对于D选项,杠杆调整后的久期缺口也不会在存款跟踪报告上面。因此,D选项不符合题意,为错误选项。
29.
Bank of Redrock, a fractional-reserve bank, is concerned about the funding liquidity risk. William, the head of the Assets and Liabilities Management Committee, is to search for information about the liquidity risk. which of the following statements is incorrect?
参考答案D
解析Answer: D本题考查的是融资流动性,商业银行商业模式,期限转换和存款准备金的相关辨析。对于A选项,市场参与者融资流动性风险通过借入短期资金进行需要较长时间才能盈利的投资而产生的。因此,A选项描述正确,不符合题意,为错误选项。对于B选项,商业银行的核心功能是吸收存款,向非金融企业提供工商贷款,在此过程中,银行进行流动性、期限和信贷的转换。商业银行流动性转换是指将流动性不好的资产转换成流动性好的负债。商业银行期限转换是指长期的资产转换成短期的负债。信用转换是指贷款人的商业信用转换成银行信用,存款人无需考虑贷款人的信用情况,只需要考虑银行信用状况。因此,B选项描述正确,不符合题意,为错误选项。对于C选项,市场参与者用短期负债为长期资产提供资金的资产负债表情况称为期限错配。因此,C选项描述正确,不符合题意,为错误选项。对于D选项,银行即使存在一个正确校准的资产负债管理系统,也不能让存款人对银行支付能力的失去信心进行免疫。而题目说的是可以完全免疫,因此,D选项描述错误,符合题意,为正确选项。
30.
Analyst Johnson is evaluating various short-term interest rate models. Two primary criteria that he is told to meet is that:1) To avoid a model that will produce a negative short-term rate, where current short-term rate is set to zero.2) To make a model that will simulate a gradually decreasing volatility level.Which of the following approaches can help Johnson to meet the criteria?
参考答案D
解析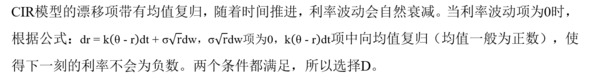
31.
Erik and Eric, two analysts within an investment firm, are discussing operational resilience, a new concept within the whole risk industry. Below are their comments on operational resilience. Which ones are right?I. Impact tolerance is a good measure to test operational resilience.II. Operational resilience is a kind of ability of firms to respond to disruptions.III. Continuity of business service is an essential component of operational resilience.IV. The objective of operational resilience is to maintain the firm’s systems and processes.V. The assumption of operational resilience is that disruptions will seldom occur.
参考答案B
解析对于陈述I,冲击容忍度是检验经营弹性的一个较好的度量指标。因此,该陈述正确。对于陈述II,经营弹性是公司应对业务中断(disruption)的能力。因此,该陈述正确。对于陈述III,业务服务的持续性是经营弹性的必要元素。因此,该陈述正确。对于陈述IV,经营弹性的目标是聚焦于业务服务(business service)而非系统和流程。因此,该陈述错误。对于陈述V,经营弹性的假设是业务中断会发生。因此,该陈述错误。综上所述,正确选项为B。
32.
Cheryl Stjohn, a risk manage intern, just joined a credit rating agency. Although she learnt several quantitative methods to calculate the default probability for different issues and issuers, she has no practical experience in doing such thing. On her second week after joining the company, she was asked by her director Richard Coleman to estimate the implied default probability for a 2-year BB rated corporate bond using intensity model. The continuously compounded spreads are given in the following table: The recovery rate on that BB rated bond is expected to be constant at 50% in the event of default. Before send her report to Richard, there are two statements Cheryl is not certain. So, Cheryl asks her colleague’s opinions. Which of the following statements is/are the most likely correct?Statement I: The risk-neutral probability that the BB rated discount bond survives in the first year and then defaults in the second year is 7.69%Statement II: The risk-neutral probability that the BB rated discount bond defaults within the next 2 years is 7.10%
参考答案D
解析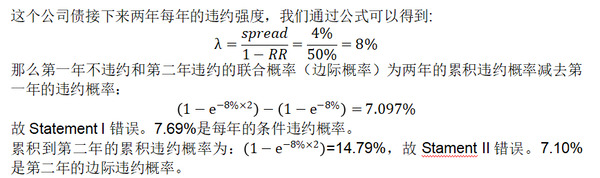
33.
National Australia Bank (NAB), one of the largest Australia banks, suffered system shut down on Oct 19th, 2020. Information from social media showed NAB’s payment system, mobile bank and internet visiting were not available during that day. Millions of customers could not access to their banking accounts. It was not the first time for the kind of accident. The data shows the accelerating growth of the IT error from 1000 times in 2017 to 2300 times in 2020. Even Commonwealth Bank of Australia (CBA), the most state-of-the-art IT system owner, occurred system crash 2 times. Now Fat Cat Bank (FCB) takes the example above as a good external loss data resource. The operation team discusses the case carefully and summarizes lessons below:
参考答案C
解析FCB可运用冲击容忍度来优化资源配置,将有限资源优先配置到最重要的业务服务中去。因此,正确选项为C。对于选项A,网络弹性的概念不仅指避免硬件损害,除了避免硬件损害外,还应保持系统软件稳健运行、夯实网络基础设施等,该网络弹性的建设是一个系统工程。因此,该选项错误。对于选项B,设置冲击容忍度无法阻止关键服务的失灵和中断,该冲击容忍度确定了潜在服务失灵或中断的容忍范围。因此,该选项错误。对于选项D,NAB案例应该被归类为“Business disruption and system failure (BDSF)”操作风险事件。因此,该选项错误。
34.
After decades’ efforts, WALAWA Bank finally enters into tier-1 banks within the region and has introduced enterprise risk management (ERM). But recent two risk events alert the bank to improve its risk management. The heads of the bank gather a meeting to try guidelines for risk management. Below are opinions from these heads.CFO: Risk-based pricing for products and services should be promoted within the organization. This year, we need to introduce RAROC (Risk-adjusted Return on Capital) as a powerful tool to help us to select projects with risk department. As head of finance to manage financial risk, I will give the number of expected losses for RAROC calculation.CBO: We understand its importance of risk appetite framework (RAF) to the bank’s risk management. But its heavy work loading spent my lines business managers too much time. We all know the board has final responsibilities of risk management, why not let the board get RAF done.CIO: Cyber risk is coming! Recent two risk events have obvious logic chain with the cyber risk. So I need to build a special force within my IT department to fight with the support from risk department.CRO: As head of risk and supporter of ERM, I need to get more resources to build integrated risk department to handle all relevant risks. But I know resources is limited and should be allocated among various department, I am happy to talk to each senior managers to delegate my part of risk responsibility with you.CEO: We face more and more risk challenges. But board process is too long and late. The best way is to have part of independent power from the board to delegate to us to risk management in a flexible and timely way. So, I will launch meeting with the board to discuss.Whose opinion( ) is(are) right?
参考答案D
解析对于CFO的陈述,CFO的陈述错误。在ERM思维下,银行应建立集成的风险管理部统筹管理所有的风险,统一计算所有风险可能带来的期望损失及非期望损失。该CFO仅计算自己部门财务风险可能带来的期望损失,该做法是传统的风险管理方式,而非ERM方式。因此,该陈述错误。对于CBO的陈述,RAF由管理层制定(develop)并交由董事会批准和审查(approve and review)。因此,该陈述错误。对于CIO的陈述,ERM思维下,网络风险应纳入风险池交由风险管理部统一管理,而非IT部门单独配置人力资源进行管理。因此,该陈述错误。对于CRO的陈述,ERM的本质是将不同部门的风险进行集成,置于CRO的领导之下做统筹管理。如果将集成的风险代理给各个部门单独管理,那么这与ERM方式相冲突。因此,该陈述错误。对于CEO的陈述,董事会对风险管理负总责,董事会将风险管理的总责代理出去不是好的业务实践做法。因此,该陈述错误。综上所述,各高管的陈述均错误,因此,正确选项为D。
35.
A portfolio manager’s “bogey” is a benchmark portfolio invested in three components: 60.0% in the S&P 500 (the equity index), 30.0% in a Lehman Bond Index (the bond index), and 10.0% in a money market fund (the cash index). The manager’s actual portfolio components included 70.0% in equities, 20.0% in bonds, and 10.0% in cash.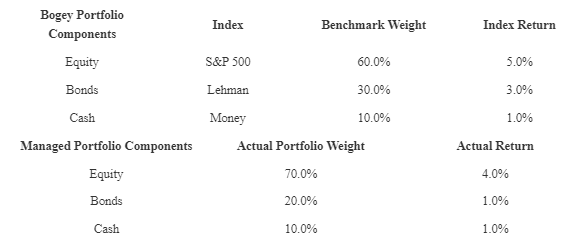 When evaluating an active manager’s performance, the excess return is usually decomposed into two components, asset allocation and security selection. Which of the following statements is CORRECT regarding performance attribution?
参考答案C
解析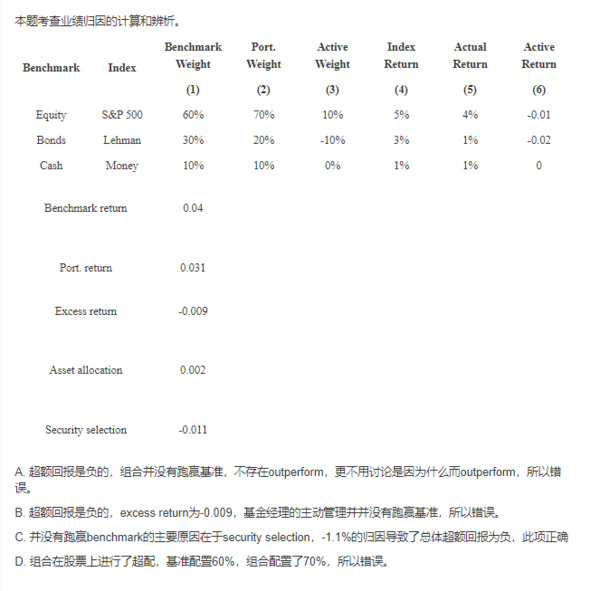
36.
Jenny makes an estimation that the underlying stock is currently at the volatility level of 25% per annum, and she has inputted the parameter into the Black-Scholes-Merton model to work out the European call option price as $4.88. While the market price of the call option is at $5.23. Now assuming a European put option with the same strike price and maturity on the same underlying stock. The put option has BSM model price output of $3.44 with the same volatility parameter input. What is the nearest price if the put option is traded in the market?
参考答案C
解析本题考察波动率微笑。买入期权市价和理论价值的差距为5.23-4.88=$0.35, 将超过部分归因到期权隐波上,意味着这支期权的市价隐波要高于模型输入的25%。对应到另一个执行价、到期时间和标的资产都完全相同的卖出期权上,它的市场价值应该也比其理论价值要高出$0.35。所以简单计算后得3.44+0.35=$3.79。
37.
Andy, a senior risk manager, is now estimating the market risk of his portfolio with both the normal and lognormal distribution assumptions. He has gathered following information:Annualized expected return = 18%Annualized volatility = 30%Current portfolio value = $3,000,000Trading days within one year =250Confidence level: 95%Andy is curious about which of the two assumptions will lead the calculation outcomes much larger, and what is the differences between the two? (Setting the loss as positive amount)
参考答案B
解析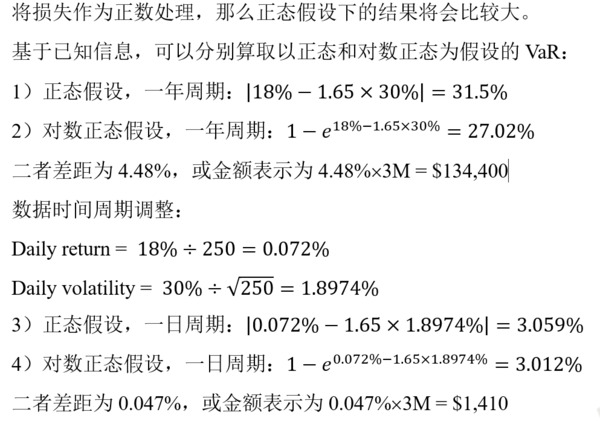
38.
A popular group of correlation options are multi-asset options. In the choices below, S1 is the price of asset #1 and S2 is the price of asset #2 at option maturity. K is the strike price, the price determined when entering into the contract, at which the underlying asset can be bought in the case of a call, and the price at which the underlying asset can be sold in the case of a put. For which of the following multi-asset options does an increase in correlation between the asset prices S1 and S2 imply an increase in the option price?
参考答案B
解析B选项的构造符合题意,题中表述是选出随着两资产相关性上升,期权的价值也一并上升的品种。二者选差,意味着只有两资产同涨同跌的情况下,期权才有可能结算出较大的收益,如果此消彼长则期权收益总是很低。
39.
A bank has implemented a VaR model for its portfolio of commodity derivatives. The bank’s risk management unit would like to establish a process for the validation of this new model. Which of the following actions would be most appropriate for a validator to take as part of this process?
参考答案B
解析验证团队应该审查输入模型的参数,分析生成模型输出结果的操作流程和信息科技系统。因此,正确选项为B。对于选项A,模型验证人员应当与模型开发人员独立开来,二者不能有交叉。因此,该选项错误。对于选项C,验证人员应当确保中台人员(middle office)能获取独立的市场和风险数据源,且交易员不能设定VaR限额,该VaR限额由高级管理层设定。因此,该选项错误。对于选项D,应当定期对模型假设做审查以确定是否有必要根据最新市场条件修订模型假设,而非在较长时间内保持模型假设不变。因此,该选项错误。
40.
Golden bank carries risk-weighted assets (RWA) of 4 billion Euros. For regulator’s capital requirement, the bank holds:-160 million Euros of Common Equity Tier 1 Capital (CET-1)-50 million Euros of Additional Tier 1 Capital-130 million Euros of Tier 2 CapitalHow many statements below are right?I. The bank’s capital structure meets the bottom line capital requirement of Basel I.II. The bank’s total capital meets the bottom-line capital requirement of Basel III.III. The bank’s core Tier 1 capital does not meet the bottom line capital requirement of Basel III.IV. The bank’s Tier 1 capital meets the capital requirement of Basel III after considering the capital conservation buffer in normal times.
参考答案C
解析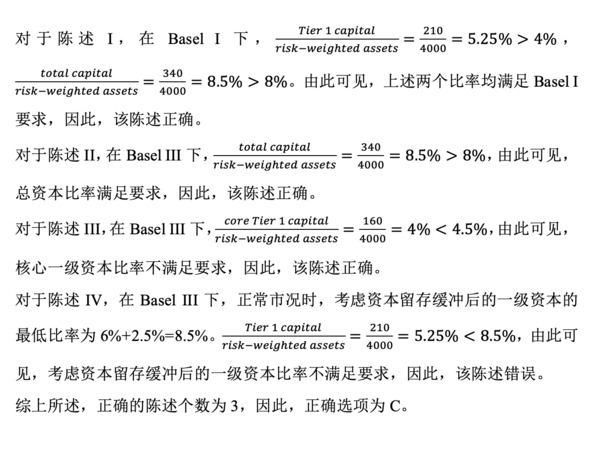
41.
A regulatory analyst at a large multinational bank is examining regulatory requirements the bank must comply with under the Basel Committee’s FRTB guidelines. The analyst explores how the FRTB guidelines evolved from the Basel I and Basel II.5 frameworks as well as the instructions for applying the guidelines. Which of the following is correct regarding the FRTB?
参考答案D
解析Basel I和Basel II.5基于VaR和Stressed VaR计量市场风险资本金,而FRTB基于Stressed ES计量市场风险资本金。因此,正确选项为D。对于选项A,Basel I和Basel II.5要求在整个公司层面计算市场风险资本金,而FRTB要求在交易台(trading desk)层面计算市场风险资本金。因此,该选项错误。对于选项B,FRTB不鼓励银行使用内部模型法计量市场风险资本金,更加聚焦标准法。因此,该选项错误。对于选项C,Basel I和Basel II.5针对所有的风险因子设置统一的流动性期限,即10天,而FRTB针对不同的风险因子设置不同的流动性期限,即10天,20天,40天,60天,120天。因此,该选项错误。
42.
Aoi Banerjee, CIO of Sagittarius Fund (a fund managing several large portfolios investing in EMEA market), is concerned that some of these portfolios may have previously unidentified biases in their alphas. She asked a senior analyst to prepare a presentation on process of refining alpha and benchmark neutralization alpha for the portfolio managers. Regarding the process of scaling the alphas, trimming alpha outliers, and benchmark neutralization, which of the following statements is correct?
参考答案C
解析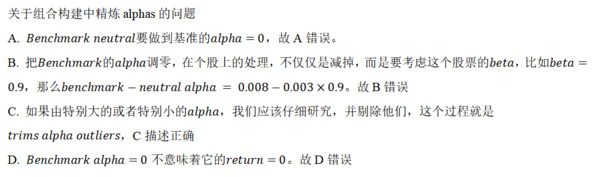
43.
Tom, FRM, a manager under asset-liability committee of financial institution, is aggressively searching ways to insulate asset and liability portfolios and the profits from the ravages of changing interest rates. The financial institution is dealing with the important goal which is to insulate profit (i.e., net income) from the effects of fluctuating interest rate. To meet the goal, Tom collects some data of his financial institution and applies interest-sensitive gap management as the hedge strategies. 6 billion dollars in interest revenues from its loans and security investment, 3 billion dollars in interest expense paid out to attract borrowed funds and it holds 50 billion dollars in earning assets. Which of the following statement Tom made is correct?
参考答案A
解析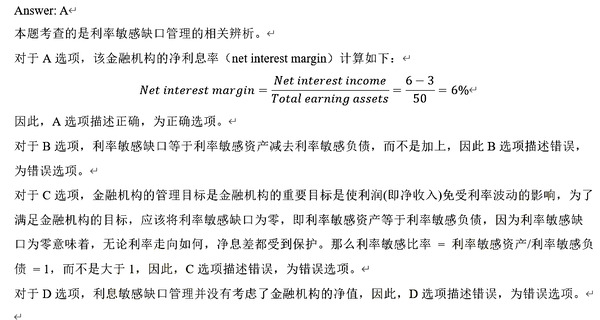
44.
Annette, FRM is an independent financial risk consultant providing risk management solutions for large pension fund. These days, Annette was hired by a pension fund named Silver Fund to tackle issues regarding risk budget. The pension fund is considering the risk budget among four portfolios which are equally weighted and all have 5% annualized volatility. How much risk budget should be allocated to each portfolio if all portfolios are uncorrelated? Assume the the annual VaR risk budget for the whole fund is $450 million using 95% confidence level.
参考答案B
解析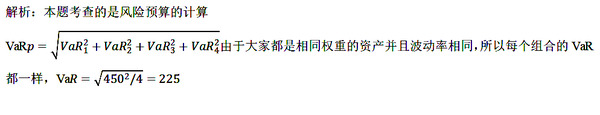
45.
Lee, a risk analyst from RUMs, collected the past performance of Neptune Endowment emerging market portfolio and generated a report to Mark Shaw, who would be delegated to manage the portfolio in one month. The market returns are derived from MSCI Emerging Markets Index. The key information from the factor regression is shown in the following table: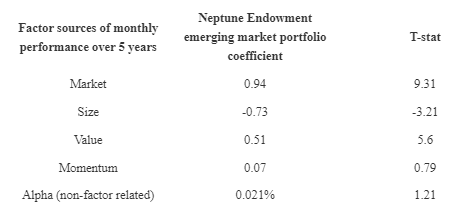 After reviewing the key information, Mark made the following short comments regarding the Neptune Endowment emerging market portfolio:üOrientation of large size stocksüMomentum factor tiltüBeat the benchmark in long runWhich of Mark’s comments about the portfolio is most accurate?
参考答案A
解析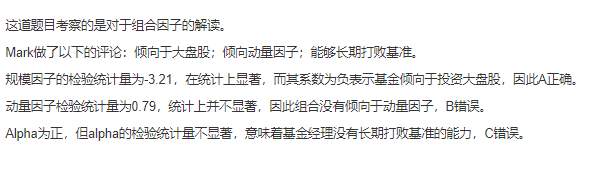
46.
Rosenfeld's startup company has built a new electronic financial platform that enables participants to trade derivatives on certain cryptocurrencies. Rosenfeld knows that market participants have a strong preference for continuous liquidity, and participants will avoid a market that suffers lack of liquidity. Rosenfeld is preparing a marketing brochure to promote the new exchange. If her goal is to promote the exchange's well-functioning liquidity features, which feature contributes to a stable market concerning liquidity?
参考答案D
解析Answer: D:本题考查都是不同交易策略和流动性关系的辨析。市场的流动性变得不好,很多时候是因为出现了单边市场,单边市场往往都是在“追涨杀跌”的交易过程中出现的。如果电子交易平台希望流动性比较好,应该尽量避免出现单边市场的情况。对于A选项,止损规则(Stop loss rules),指的是投资者在交易后设置了止损线,达到止损线则会自动进行交易,而在止损自动交易时,如果投资者是多头头寸,则说明在价格下跌达到止损线时,会自动卖出资产。那么可能会出现,在资产价格下跌时候,投资者都想卖出,造成资产价格进一步下跌,容易出现单边市场,导致流动性不好,因此止损原则是消耗流动性的策略。因此,A选项不符合题意,为错误选项。对于B选项,趋势交易(Trend trading),指的是投资者在资产价格上涨的趋势中,认为资产价格会有继续上涨,所以大家都想买入,而投资者在资产价格下跌的趋势中,认为资产价格会继续下跌,所以大家都想卖出,在这种交易模式中,就是“追涨杀跌”过程出现单边市场,使得市场流动性变得不好。因此,B选项不符合题意,为错误选项。对于C选项,流动性黑洞(Liquidity black hole)指的是市场流动性消失,就像黑洞一样,把流动性全部吸收完了。因此,C选项不符合题意,为错误选项。对于D选项,负反馈交易(Negative feedback traders),指的是投资者在资产价格下跌的时候买入该资产,在资产价格上涨到一定程度时卖出。低买高卖的形式,给市场提供了流动性。因此,D选项符合题意,为正确选项。
47.
Netting is a traditional way to mitigate counterparty risk where there may be a large number of transactions of both positive and negative value with either a single counterparty (bilateral netting) or multiple counterparties (multilateral netting). Close-out refers to the process of terminating and settling contracts with a defaulted counterparty. Which of the following statements about netting and close-out is least likely correct?
参考答案C
解析本题考查净额结算的相关概念。净额结算可以减少场外衍生品交易对手的风险敞口,但可能对其他债权人产生不利的影响,因为在净额结算的过程中会将资金从其他债权人重新分配给场外衍生品交易对手。因此C选项描述错误,符合题意,为正确选项。对于选项A,净额结算可以将所有的债权和债务进行汇总处理,是缓释交易对手风险的有效措施,对快速增长的场外衍生品市场的风险管理至关重要,在保持市场风险恒定的同时,减少了结算风险、交易对手风险、运营风险、流动性风险和系统性风险。因此,该选项描述正确,不符合题意,为错误选项。对于选项B,通过多个交易对手的合作实现多边净额结算可以压缩交易规模,最大限度地减少市场中的名义总头寸。因此,该选项描述正确,不符合题意,为错误选项。对于选项D,清盘净值结算在交易对手违约时生效,旨在及时终止和结算与该交易对手的所有交易净值,可以跳过破产清算环节优先获取资金。因此,该选项描述正确,不符合题意,为错误选项。
48.
Covered interest parity (CIP) is a physical law in international finance that hold the interest rate differential between two currencies should equal the differential between the forward and spot exchange rates. But it has been violated since 2014 and many bankers are studying why. And this law is related with the FX swap, cross-currency swap and cross-currency basis swap. Which of the following statement is correct about this issue?
参考答案B
解析Answer: B:本题考查的是FX互换,cross-currency互换,抛补利率平价公式迷失原因的辨析对于A选项,cross-currency swap是一项长期的工具,借入的金额在期初和到期日均按初始即期汇率进行交换。在FX swap中,借入的资金以即期汇率交换,到期时以预先商定的远期汇率偿还。题目的表述刚好相反,因此A选项描述错误,为错误选项。对于B选项,在跨货币基差掉期(cross-currency basis swap)中,在基差掉期的有效期内,交易对手定期交换利息,融入非美元的一方需要支付非美元货币对应的利息,这部分利息对应的利率等于该币种的LIBOR加上基差basis。B选项描述正确,为正确选项。对于C选项,银行、机构投资者和非金融机构对货币对冲的需求是导致swap basis扩大的原因,而不是为什么不收敛到零的原因,因此C选项描述错误,为错误选项。对于D选项,大金融危机后,监管变化、成本和风险增加、定价结构变化等对套利活动的新约束是导致swap basis为什么不收敛到零的原因,而不是导致swap basis扩大的原因,因此D选项描述错误,为错误选项。
49.
Several banks are currently trying to automate their lending decision making process using machine learning.Wally Wong is a student of University of Pennsylvania, majoring in Computer & Cognitive Science. When she applied for the credit risk summer internship program in Morgan Stanley, she wrote following sentences in her cover letter to convince HR of her thorough understanding of algorithms and models in machine learning and artificial intelligence:“Altman’s Z-score model is used commonly nowadays and we can easily get z-score for public firms from Bloomberg. With this approach, algorithm is given a great deal of data on firms and whether they have defaulted, and then it come up with a rule for distinguishing between those firms that default from those that do not.The most significant advantage of this model is that it is a nonlinear discriminant analysis model which can explore nonlinear relationship between features and dependent variable. Moreover, there is no need to worry about overlapping zone because Z-score model can provide perfect classification.There are some complex algorithms increasingly used in risk management such as neural networks. Neural networks algorithm tries to simulate the behavior of the human brain, to mimic human’s fuzzy logic and to learn from success or failure outcomes over time.However, complex algorithms also have some shortcomings, such as black box. It is hard for any human to understand and audit from outside, and to examine step by step how results are obtained.”Which of the concepts Wally Wong shared in her cover letter is inaccurate?
参考答案B
解析P2B2 – other method to estimate PD此题考查的是机器学习人工智能在信用风险里的一系列模型的定性辨析。A选项正确,Altman’s Z-score模型就是通过算法,从公司数据中,试图来区分哪些公司可能会违约,哪些公司不太容易违约。B选项错误,Altman’s Z-score模型是一个线性区分模型,并不能探索特征和应变量之前的非线性关系。C选项正确,神经网络模型就是来模拟人脑的行为,试图模拟人类模糊逻辑的决策过程,并且会不断地从失败和成功中学习。D选项正确,很多复杂的模型都会有黑箱的问题,黑箱导致我们很难去阐释结果,很难理解,无法审计。
50.
A risk management team of a large investment bank is running a risk control of bank’s counterparty risk. The bank has a large number of counterparties and demands a better counterparty risk management system. Different managersare suggesting different credit risk mitigation methods: netting, collateral, and central counterparty, and they made the following statements on their risk report to department head:Statement I: Since CCP offers great transparency, efficiency and a well-defined loss mutualization process, every member will be benefited. It can effectively mitigate systemic risk because OTC counterparty risk can almost be eliminated by CCP clearing.Statement II: When using collateral under Credit support Annex, an initial margin will more likely make the exposure overcollateralized. The bank should encourage counterparties to post initial margin to reduce counterparty risk, operational risk and funding liquidity risk.Statement III: Rehypothecation is the reuse of variation margin by margin payer. For end users, reuse of margin is common because they often involve in offsetting transactions.Which of these statements is/are most likely correct?
参考答案D
解析P2B2 – credit risk mitigants该题主要考点为各种对手方风险缓释工具的性质。StatementI错误,CCP确实有众多益处,但是CCP把风险集中在自己身上,可能会造成金融系统的风险。StatementII错误,初始保证金确实可以看作是一个使得敞口变成超额抵押的手段,它可以有效降低交易对手风险,但可能会引起更多的融资流动性风险。Statement III错误,再抵押现象主要出现在margin receiver中,当他们收到抵押品,由于签订了反向合约,会再把这些抵押品抵押出去,这个现象为再抵押,主要发生在投行中,end users比较少,因为end users合约的方向比较明确,较少出现offsetting transactions.
51.
The board of directors of an insurance company has identified a number of potential growth opportunities for the company to consider. To help assess these opportunities and determine an optimal risk structure to use across the organization, the risk committee has recommended that the company implement an ERM program. Which of the following would best represent an appropriate goal for the firm to state as part of the ERM program?
参考答案A
解析ERM视角下,公司既不是最小化风险,也不是最大化收益,而是应平衡好风险和收益的关系,实现既定风险敞口下的较高收益,从而最大化股东和企业价值,同时反映出公司的目标信用评级。公司还应确保业务部门在公司总的目标信用评级和总的风险偏好度范围内来评估新开展的业务。因此,正确选项为A。对于选项B,ERM视角下,公司应将陷入财务困境的概率限定在既定水平上,而不是完全消除财务困境出现的概率,完全消除财务困境出现的概率既不符合现实,也不可能实现。因此,该选项错误。对于选项C,最大化杠杆比率来追求最高的ROE会带来较大的风向敞口,一旦市场发生不利的变化,较大的风险敞口会带来较大的损失,该损失可能会超过银行既定的风险限额(risk limits),与审慎的风险文化理念相违背。因此,该选项错误。对于选项D,公司展业会带来利润,但同时也会带来风险。所以,在风险视角下,不能设定最低利润值,因为公司为了实现最低的利润目标,可能会追逐一些高风险业务,进而增大风险敞口,这和审慎的风险文化理念相违背。因此,该选项错误。
52.
As we know, the bank prefers economic capital as capital requirement to regulatory capital under standardized approach. Below are the reasons and advantages for economical capital except:
参考答案D
解析经济资本基于内部模型法予以计量,内部模型法适用于大的、风险管理完善的银行,不适用于小银行,小银行往往偏向于使用标准法来计量监管资本。因此,D选项陈述错误,符合题意,为正确选项。对于选项A,经济资本考虑了不同产品组合之间的相关性和分散化效应,监管资本不考虑产品组合之间的分散化效应,故经济资本往往比监管资本低。因此,该选项陈述正确,不符合题意,为错误选项。对于选项B,监管资本基于会计资本和会计价值,如果会计价值低于经济价值,则监管资本被低估,银行可能会被处罚,被要求保有足够的流动性资产来覆盖资本金的缺口部分。因此,该选项陈述正确,不符合题意,为错误选项。对于选项C,经济资本基于内部模型法予以计量,内部模型法会耗用较多的银行资源用于建模,而监管资本基于标准法予以计量,耗用的银行资源相对较少。因此,该选项陈述正确,不符合题意,为错误选项。
53.
Billy Cox works in Dwarf Planet, a special purpose vehicle established by a Poland-based investment bank that was recently formed by the merger of three small investment banks in Poland, Belarus and Czech. A SPV is a distinct legal entity that is the “company” through which a securitization is undertaken, and to secure favorable tax treatment, Dwarf Planet is set up in Cayman Islands. After reviewing the underlying asset pool, Billy recommends credit enhancements for a better issuance.The following are excerpts from a recent internal document by Billy about the credit enhancements:1. Overcollateralization is one of the credit enhancement methods we can use. We can issue a par amount of ABSs that is smaller than the par amount of underlying collateral. This method provides credit enhancement for all of the bond tranches of a securitization.2. We can consider excess spread. Excess spread means that there is more cash flow received from the assets used to secure the issue than the interest paid to investors.3. We can also seek help from external support. Some composite insurance companies provide insurance policy (pool insurance) to cover the risk of principal loss in a collateral pool.4. Afterall, we should note that overcollateralization is soft credit enhancement while excess spread is hard credit enhancement.Which of the features about credit enhancement is incorrect?
参考答案C
解析P2B2 – securitization credit exposure此题考查的是不同的信用增强方法。Overcollateralization,超额抵押,指的是发行的产品总量比抵押品少。Excess spread,利差储备,指的是底层资产的现金流入大于发行产品的现金流出,可以给未来现金流的不确定做缓冲。超额抵押是Hard credit enhancement,因为抵押品是实实在在抵押在那儿的,而利差储备是soft credit enhancement,因为是否能达成利差储备取决于底层的现金流流入,有一定的不确定性。还有外部信用增强的方式,比如找保险公司做担保。
54.
Eric, a fund manager of Jupiter Fund. After managing the fund for two years, he is requested by the limit partners of the fund to provide a comprehensive investment performance report. According to the reporting requirement, time-weighted return and dollar-weighted return should be applied simultaneously. Eric recalled his investment decisions as follows: He invested $100 million in an account, initially. After one year, the value of his investment was $120 million, and Eric added another $80 million into the account. At the end of Year 2, the total value of the investment was $220 million. Which of the following statements about the return calculation is CORRECT?
参考答案B
解析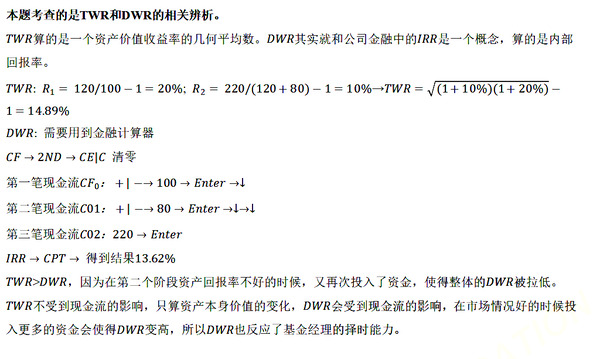
55.
Afund manager of a pension fund manages a 30 million portfolio only including one security. Due to repay the pension funds to the investors, the fund manager needs to liquidate the portfolio. The assistant of the fund manager collects the information on that daily volume in that security is 10 million and one-day liquidation does not exceed 15% of the daily volume in that security can avoid a material adverse earning impact. During the liquidity duration, the fund manager equally liquates the positions and assumes the daily volatility keeps constant. Before liquidation, the 1-day 95% VaR of this portfolio is 4 million dollars. Please calculate the liquidity duration and convert the 1-day 95% VaR to the 95% VaR of the whole liquidity duration considering the adverse price impact. Liquidity duration 95% VaR of the whole liquidity duration
参考答案D
解析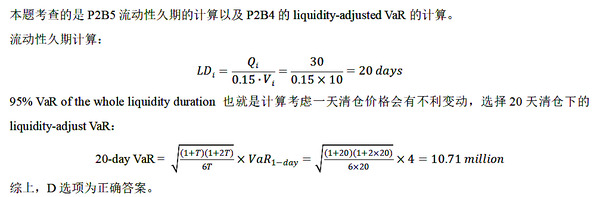
56.
An endowment fund has received a donation of USD 800 million. The fund’s CIO has decided to invest the USD 800 million in a portfolio that contains two actively managed portfolios which managed by different active managers, both benchmarked to the same index. Currently, the CIO is trying to decide how to allocate the USD 800 million to these two active managers within the overall portfolio so as to maximize the resulting information ratio, subject to an overall 4% tracking error target. Relevant statistics for the two managers, the current overall portfolio, and the benchmark index are given in the following table: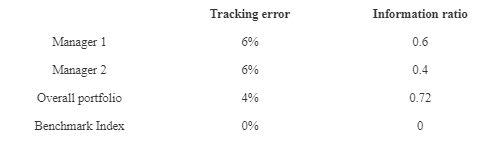 Assuming the active returns of the two managers are independent and normally distributed, which of the following statements is INCORRECT about the fund’s relative risk budget?
参考答案D
解析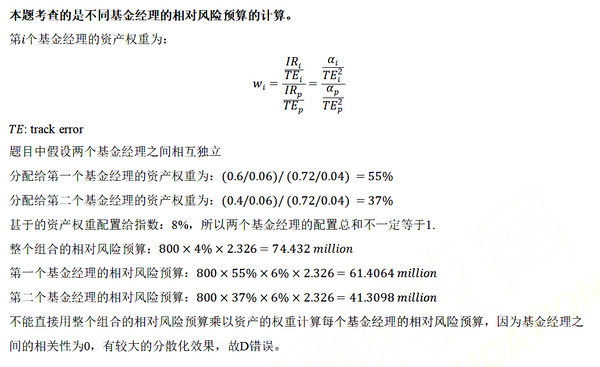
57.
An underwriter structures a collateralized loan obligation (CLO) composed of 100 identical loans, each with a notional value of GBP 800,000 to be repaid in one year with an interest rate of LIBOR+3%. The CLO has one planned payment at maturity and its capital structure is given by: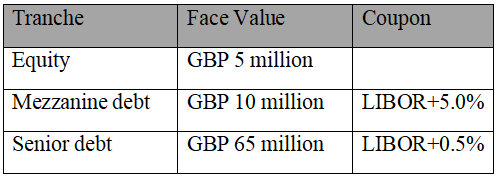 At maturity the CLO accumulates GBP 6,625,000 of losses from defaults and unpaid interest. If LIBOR was flat at 1% over the 1-year period, and assuming no recovery on the defaults, how would the losses be absorbed by the capital structure?
参考答案B
解析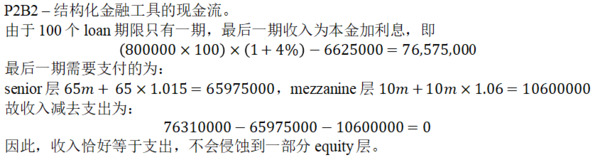
58.
An analyst is employing the Merton model to estimate the default probability. The capital structure of the firm consists of two parts: zero-coupon debt with a face value of $10 million and the rest of is equity. The firm current asset value is $15 million with an expected return of 4.5% per annum with continuous compounding. The volatility of the firm’s assets is 30% and the risk-free rate is 3%. Which of the following statements is most likely correct?Ⅰ. The approximate distance to default of the firm is 1.35 for one year horizon.Ⅱ. An increase in the risk-free rate will increase the firm’s equity market value.Ⅲ. The credit spreads widens as interest rates increase.Ⅳ. An increase in the risk-free rate will decrease the risky world default probability.
参考答案B
解析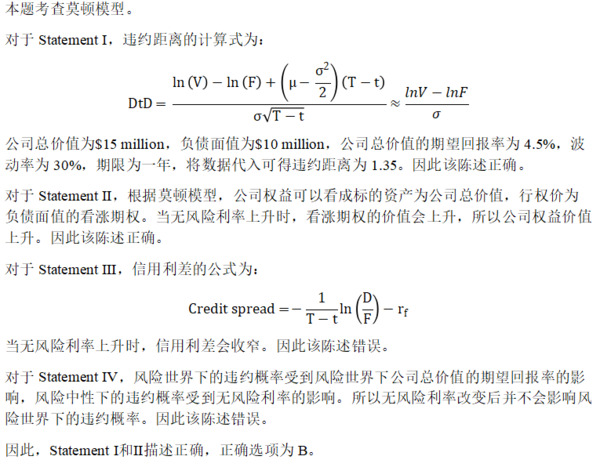
59.
In portfolio risk management, there is a systematic application of VaR to many sources of portfolio risk. VaR was developed as a methodology to measure portfolio risk initially andover time, risk managers have discovered that they could use the VaR process for active risk management by using marginal VaR, incremental VaR, and component VaR. What’smore,the calculation of VaRcanalsoconsider liquidityrisk.which of the statement about VaR tools is correct?
参考答案B
解析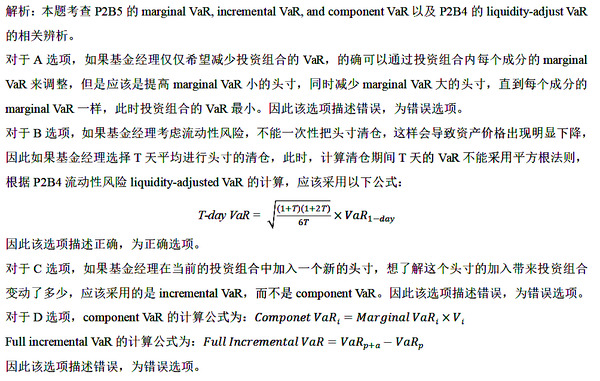
60.
Basel III introduces two buffers to reduce procyclicality and build-up additional capital in normal time that can be drawn down in periods of stress respectively. Which of the following statements concerning the two buffers is (are) correct?I. Basel III introduces a capital conservation buffer of 2.5% (of RWA) consisting of common equity Tier 1 capital.II. Basel III introduces a countercyclical capital buffer of between 0% and 2.5% (of RWA) to be determined by respective national supervisory authorities.
参考答案D
解析:该题主要考点为Basel III下资本留存缓冲和逆周期资本缓冲的概念。对于陈述I,Basel III要求计提2.5%的资本留存缓冲比率,且该缓冲必须是一级权益资本。因此,该陈述正确。对于陈述II,Basel III设置了逆周期资本缓冲,该缓冲比率介于0和2.5%之间,具体比率由各个国家监管当局确定。因此,该陈述正确。因此,正确选项为D。
61.
Peter is an analyst who works for a hedge fund. Unlike many of his peers from business school, who work for funds that cannot much drift from their somewhat narrowly defined investment styles, Peter’s fund has broad discretion with respect to both location of opportunity and trade tactics. However, his fund does tend to make directional bets in liquid, often highly liquid, markets. For which type of hedge fund does Peter most likely work?
参考答案B
解析本题考查的不同对冲基金策略的辨析。此题用排除法做会更好。首先,没有一个特定的investment style,所以C、D就不太符合(可转债套利、困境债券就只专注于某类资产的投资),和A相比,选全球宏观更好,全球宏观可以运用最广泛最弹性的权限,在世界各地进行投资,并且全球宏观策略是一个directional方向性的策略。
62.
Sammi Li, CFA, FRM, CQF, is a manager in treasury department of a small bank, Bank Capricorn. She is monitoring and managing quantitative liquidity risk by using the term structure of expected cash flows and the term structure of expected cumulated cash flows. She collects the data in the following chart: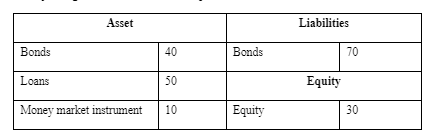
 According to the information Sammi collected, which of the following statement is correct?
参考答案B
解析Answer: B本题考查的是TSECF和TSECCF的相关辨析。对于A选项,预期现金流期限结构(TSECF)描述不仅仅是正预期现金流,还有负预期现金流。因此A选项描述错误,为错误选项。对于B选项,当银行对过去净现金流的动态演变如何影响其当天的总现金头寸感兴趣时,Sammi应该使用累积预期现金流的期限结构(TSECCF)来分析。因此,B选项描述正确,为正确选项。对于C选项,根据题目给到的信息,我们可以得知在第2年到第5年之间是存在负的累积预期现金流的,因此,C选项描述错误,为错误选项。对于D选项,当累积预期现金流的期限结构(TSECCF)在预期基础上显示为负值时,这意味着银行可能会破产,而题目说的预期现金流期限结构(TSECF),因此,D选项描述错误,为错误选项。
63.
A bank issues a $200,000,000 loan with the following characteristics:■ Loan pays a fixed annual interest rate of 8.5%.■ The interest expense associated with the loan is 6.0%.■ The operating cost to the bank’s commercial lending division is $1,600,000.■ Economic capital required to support the loan is $16 million, which is invested in T-bills paying a rate of 2.8%.■ The expected loss associated with the loan is 15 basis points per year.■ The effective tax rate is 20%.What is the risk-adjusted return on capital (RAROC) for this loan?
参考答案D
解析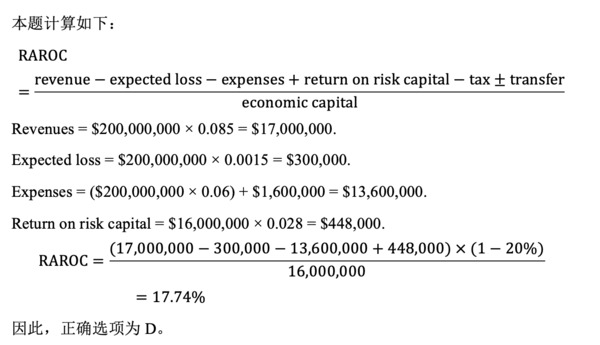
64.
Thomas Wood, FRM, joins Falent Investment as junior risk analyst. He is dispatched to the credit risk quant team. He and his colleague discuss how to deal with credit risk mitigation more effectively. They make the following four statements:1. The credit value adjustment (CVA) is defined as the present value of the expected value or price of counterparty credit risk.2. A greater CVA value represents a cost to one party who bears a greater propensity to credit loss of his counterparty.3. Implementing a netting scheme will be more effective than increasing collateral to lower credit risk.4. Setting minimum transfer amount and posting collateral will help lower CVA.Which of the sentences that Thomas Wood says is(are) correct?
参考答案A
解析P2B2 - CVA第一句话和第二句话都正确,是对CVA的定义和解读,CVA就是对于交易对手风险的定价,CVA越大,意味着交易对手违约的可能性越大。第三句话错在,相对于其他各种方法,增加抵押品是最有效的降低信用风险的方法。第四句话错在,MTA会增加CVA,没有足额抵押,会有敞口存在,但抵押品确实会降低敞口从而降低CVA。
65.
Jackson is an employed risk analyst who is evaluating the latest back-testing results of his firm’s VaR. The back-testing is based on the framework for conditional coverage model on one-year statistical test. Which of the following is the most likely reason to be the justification for a shift to a conditional coverage model?
参考答案A
解析条件覆盖模型是在无条件模型的基础上,引入了极端亏损金额的联动假设,考虑亏损聚集效应,先判断是否存在聚集效应,再判断是否需要拒绝原模型的VaR值结果。
66.
Basel II requires a back-testing of a bank’s internal value at risk (VaR) model (IMA). Assume the bank’s ten-day 99% VaR is $1.35 million. The null hypothesis is that VaR model is accurate under two-tailed 95% or 99%confidence interval. Out of 1,000 observations, 25 exceptions are observed.
参考答案A
解析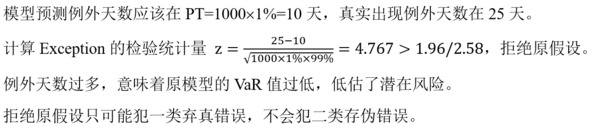
67.
Lucy, FRM, is a quantitative analyst and recently uses historical simulation to estimate the 95% expected shortfall of certain risky portfolio. She firstly takes 100 trading-days loss data, and assumes empirical loss/profit distribution as a uniform distribution, and collects data as follows.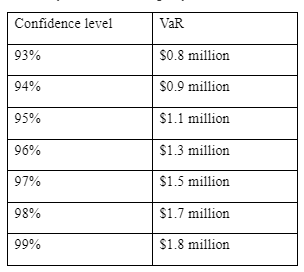 Before she calculates the expected shortfall, she finds that all of the seven largest loss data happened from 40 to 60 trading days ago. According to the age-weighted historical simulation method with decay rate of 0.9, which of the following statements is most likely correct (Setting the loss as positive amount)?
参考答案B
解析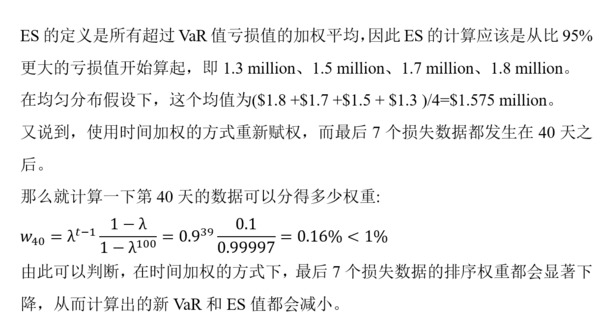
68.
Assuming the current one-year interest rate is 10.0%. In each of the next two years, the rate will either increase or decrease by 2.0% with equal probabilities. It is expected that the rate will either increase to 12.0% or decrease to 8.0% in the next year due to volatility. If there is no volatility, the term structure of the interest rate will stay flat, indicating current one-year interest rate is equal to the one-year spot interest rate starting one year from now. What is the absolute yield change regarding spot interest rate starting one year from now owing to convexity effect implied by Jensen's Inequality (Assuming interest rate is compounded annually)?
参考答案B
解析
69.
Assuming a trader has currently bought $100 million of nominal Treasury bond. Since he holds the belief that the bond markets will go bearish and hedging protection is necessary, he decides to take a face amount of TIPS based on either DV01-hedge or single-variable regression method. The regression results are shown as below: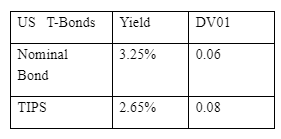
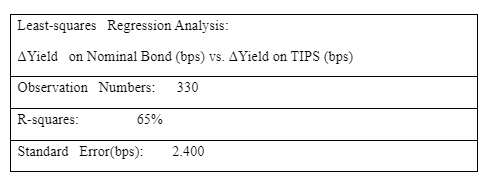
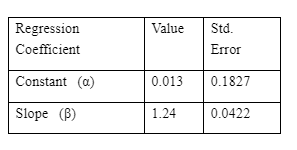 Which of the following statements is least likely considered as correct?
参考答案B
解析B选项说法错误,(1.24-1.0)/0.0422=5.6872>1.96, 拒绝1.0的原假设,所以应该接受β=1.24。A选项正确,R2=0.65, ρ= 0.8062。C选项正确,DV01-hedge method下,N(TIPS)=N(Nominal Bond)´0.06/0.08=$75MD选项正确,regression hedge method下,N(TIPS)=N(Nominal Bond) ´ 0.06/0.08 ´ 1.24 =$93M两个方法的差距为93M-75M=$18M
70.
The senior management team of a small regional bank has established a committee to review procedures and implement best practices related to entering into significant contracts with third-party vendors. The committee is reviewing one proposed relationship with a third-party vendor who would have a significant responsibility for marketing the bank’s financial products to potential customers. In establishing policies to reduce the operational risk associated with this potential vendor contract, which of the following recommendations would be most appropriate?
参考答案A
解析本题主要考点为外包风险(outsourcing risk)的管理。银行应审查外部服务商所有的公开可得的审计报告。因此,正确选项为A。对于选项B,银行应审查外部服务商的激励性薪酬结构从而确保服务提供商的销售代表的销售佣金(commission)不与银行产品的销售量挂钩。因此,该选项错误。对于选项C,银行可能将自身关键的业务服务外包给第三方服务提供商,此时第三方服务提供商会接触到这些关键的业务服务,银行应做好对应的风险管控。因此,该选项错误。对于选项D,银行应该监控(monitor)外部服务提供商建立(develop)的应急规划流程(contingency planning process)以缓释外部服务提供商的风险敞口。因此,该选项错误。
71.
To understand the volatility in foreign currency options, an FRM candidate collects the volatility data of foreign currency options to draw the graph showing the relationship between implied volatility and K/S0 along with the implied and lognormal distribution for foreign currency options. Since the graph illustrates volatility skewness, the analyst finds out that there is a negative correlation between equity prices and volatility. Which of the following statements is least likely correct?
参考答案C
解析该题主要考点外汇期权的波动率微笑和隐含分布的特点。在外汇期权波动率曲线中,隐波两边高,中间低,即虚值和实值状态时,隐波高,而平值状态波动率低。其隐含分布相对于对数正态分布,呈现出尖峰肥尾的特点。对于选项A,波动率曲线是微笑状态。该选项描述正确,不符合题意,为错误选项。对于选项B,由于隐含分布相对于对数正态分布呈现两侧肥尾状态,所以深度实值看涨期权(靠近左侧尾部)的波动率更高,定价也更高。该选项描述正确,不符合题意,为错误选项。对于选项C,隐含分布相对于对数正态分布呈现左右两侧肥尾状态,而不是左侧肥尾、右侧瘦尾。该选项描述不正确,符合题意,为正确选项。对于选项D,外汇期权在虚值和实值状态时,波动率高,而平值状态波动率最低。该选项描述正确,不符合题意,为错误选项。因此,本题正确选项为C。
72.
Assume we map an option portfolio of long call options only to delta and vega. What is the impact to our mapped exposures of a sharp decline in the underlying asset price?
参考答案C
解析现在讨论买入期权call,它的delta和vega都是正向的头寸。标的暴跌,delta敞口会出现亏损,但是暴跌会使得期权的隐波拉升,此时vega头寸会盈利。
73.
Fürstentum Bank (FB), a bank with operations in Germany, Switzerland and Austria, is currently preparing for business expansion and reviewing its portfolios containing several credit-risky securities. Edmund Freitag, a junior risk analyst at FB, distributes the documentations to the risk management team for reviewing. The credit-risky securities that FB holds are bonds, commercial papers, off-balance-sheet exposures such as guarantees and several CDSs. Freitag shares the information he collected to help the risk management team to establish an overview of developed portfolio credit risk models. He says:Sentence I: “One of the most developed portfolio models is Credit Portfolio View model by McKinsey. This model is a top-down model which focuses on the effect of macroeconomic factors on portfolio credit risk.”Sentence II: “KMV model is also a well-developed portfolio credit risk model. The essential feature of this model is the distance to default (DD), which is an application of the Merton approach to estimate the probability of default.”Sentence III: “Another model I want to introduce is CreditRisk+ by Credit Suisse. This model is a mark-to-market model which considers changes in market values and ratings changes. The mark-to-market model is more superior because it takes any movement in the market value of the bond or in the credit rating into considerations.”Which of the sentences that Freitag says is(are) correct?
参考答案A
解析P2B2 – portfolio credit risk此题考查的是四个组合信用风险模型中的三个:CreditRisk+, KMV和Credit portfolio view。这一知识点学生重点掌握每一个模型的特征即可。Sentence I 正确。Credit Portfolio View由麦肯锡开发,是一个自上而下的模型,希望通过宏观因子来找到信用风险的变化。Sentence II正确。KMV模型亦可以用在信用组合中,是莫顿模型的具体应用,关注的焦点就是违约距离。Sentence III错误。CreditRisk+这个模型是一个default mode model而非盯市模型,通过泊松分布的来估计违约和违约相关性,但并没有考虑到评级下调但没有违约的市场价值变化。
74.
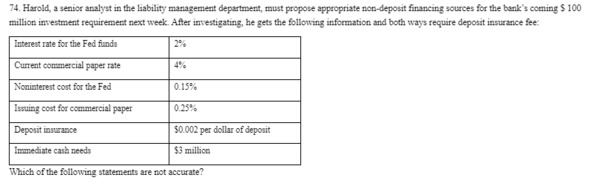
参考答案D
解析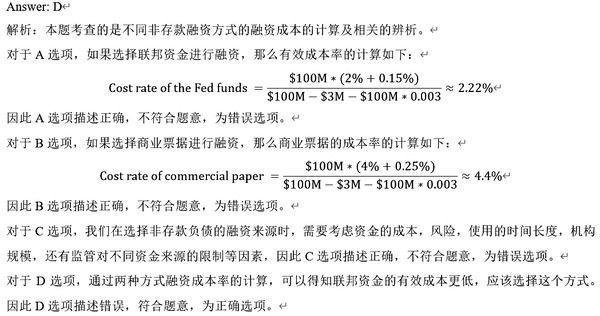
75.
After financial crisis, capital supplement becomes the major trend for large banks. But turbulence financial market delays the process. People realize the system should mobilize more capital channels to fill the capital hole.One possible channel banks favor is CoCo bond. But the Deutsche bank CoCo crisis made investors have big concerns on the tool.Another possible channel is capital conservation buffer, which allow banks to gather money in flexible market time.Xuan Zhang, Zhen Zhang, 2 senior analysts of Forget Your Money Bank, were assigned the job to assess the capital inject plan. Below are their discussion results.
参考答案B
解析Capital conservation buffer直接补充在一级核心资本上,对资本结构的补充较好。而CoCo债只有在转换时才可以补充入资本金,而且是补充在additional tier-1/tier 2资本金上的。所以,Capital conservation buffer对资本增补作用更好。因此,选项B正确,选项A错误。对于选项C,Capital conservation buffer的成本比CoCo债的成本高。因此,该选项错误。对于选项D,Capital conservation buffer的资本比率要求是2.5%,CoCo债并没有相应的比率要求。因此,该选项错误。
76.
John, a risk management analyst, who works in an investment bank, predicts that the market has gone through such a volatile period, which is quite different from the past. He proposes to choose an appropriate non-parametric historical simulation to adapt to the forecasted market. Which of the following statements about the non-parametric model is least correct?
参考答案D
解析该题主要考点为非参数和半参数模型。此题比较时间加权、波动率加权、相关性加权以及过滤历史模拟法的特点。对于选项A,时间加权历史模拟法,赋予最近期间观测值的权重更高,减少了鬼影效应。该选项描述正确,不符合题意,为错误选项。对于选项B,波动率加权模型通过调整预期波动率(而不是单纯使用历史波动率),来体现当下市场环境下对于波动率的预期。比起使用历史波动率的方法,波动率加权对当前波动率预期更加敏感。该选项描述不正确,符合题意,为正确选项。对于选项C,相关性加权历史模拟法通过调整回报,以反映历史和当前相关性之间的变化。该选项描述正确,不符合题意,为错误选项。对于选项D,从结果来看,过滤历史模拟法表现良好。该选项描述错误,符合题意,为正确选项。因此,正确答案选D。
77.
Aeolos Fund manages two European equity portfolios and the benchmark for both is MSCI Europe Index. Two portfolios are managed by two different active managers. At the end of the year, RMUs appraise the performance of two active managers. During the monitoring process, RMUs discuss the characteristics of different performance evaluation methods. Which of the following statements regarding the performance evaluation methods is INACCURATE?
参考答案D
解析本题考查的是业绩评估不同指标的辨析。A选项正确,Jensen’s alpha可以看作,把CAPM的理论预测回报率作为benchmark的超额回报。B选项正确,如果想要测度主动管理的表现,应该关注的是information ratio,也就是承担一单位偏离基准的风险,可以获得的超额回报。C选项正确,是一种调整后的风险收益测度,把组合的风险和基准的风险做了一个调整,调整后,组合和基准就在同一风险维度上。D选项错误,如果要测度承担一单位的系统性风险的超额回报,应该选用Treynor ratio而非Sharpe ratio。
78.
Bach Barthélemy got an interview opportunity from the recommendation by his ESSEC business school alumnus. After the first phone interview, the risk manager Laurent Gérard sent Bach a small case to test his capacity of Python. Bach was asked to draw the expected exposure of four different position by Python. Based on features of these different instrument, Bach used Monte Carlo Simulation to simulate the distribution of these instrument and then draw the diagrams of expected exposure. Which of the following diagrams of expected exposure is most likely incorrect?
- A.FX forward contract
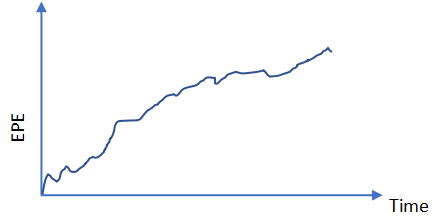
- B.interest rate swap paid quarterly and received semi-annually
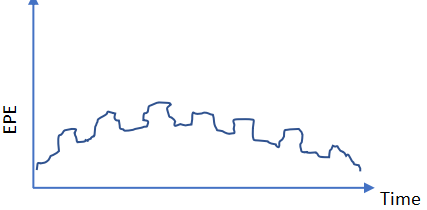
- C.Credit Default Swap
- D.Cross currency swap
参考答案D
解析P2B2 – 敞口形状这里考的是不同工具的EPE的形状。我们课件和教材上是平滑的曲线,是最终根据模拟结果平滑过的,而Bach用蒙特卡罗模拟的结果并没有进行平滑,所以会呈现出弯弯曲曲的曲线,但总体的走势是一样的。A. 远期,随着时间增加,不确定性增加,敞口一路上涨,正确。B. 利率互换的形状应该是先上升后下降,在约1/3处达到顶点。这张图表现的是期限不匹配的互换,会出现这样的情况,课件中下凹是因为收到比支付更加频繁,所以一旦收到后,敞口下降,出现下凹。而这里是支付比收到更频繁,所以一旦支付后,由于没有收到现金流,敞口上升。正确。C. CDS的EPE长得和利率互换很像,正确。只有讨论更加尾部的PFE的时候才会出现触发赔付而高企的状态。D. 货币互换相当于是利率互换+外汇远期,最终图形应该很类似外汇远期,并没有后期敞口陡然下降的情况,故D错误。
79.
Jim works in a financial company that has recently bought large numbers of fixed-rate bonds. He wants to choose appropriate interest rate models to hedge the interest rate risk. After analyzing some models with time-dependent volatility, the CIR and lognormal models come into his consideration. Which of the following statements regarding the characteristics of these two models is (are) most likely correct?Statement I: The CIR model has a constant yield volatility and the basis volatility increases proportionally to the square root of interest rate.Statement II: The lognormal model has a constant yield volatility and the basis volatility increases linearly with interest rate.
参考答案A
解析
80.
Leo, a risk head of a local commercial bank, is reviewing the developments of Basel I~ Basel III and gives his comments below. Which one is wrong in these comments?
参考答案C
解析从Basel I 到Basel III,操作风险计量从Basel II下的基本指标法、标准法及高级计量法转向Basel III的标准法,即标准计量法(standardized measurement approach)。因此,C选项描述错误,符合题意,为正确选项。对于选项A,从Basel I 到Basel III,信用风险计量的标准法没有大幅变化,仅是风险权重更具有颗粒度,资产类别更全面。因此,该描述正确,不符合题意,为错误选项。对于选项B,从Basel I 到Basel III,市场风险计量的标准法发生了巨大变化,即从关注资产类别和风险权重的传统标准法转向风险因子敏感性方法。因此,该描述正确,不符合题意,为错误选项。对于选项D,从Basel I 到Basel III,Basel II.5是独特版本,因为该版本是对2008年金融危机所做出的紧急反应,且仅涉及市场风险。因此,该描述正确,不符合题意,为错误选项。