2025年FRM金融风险管理师《FRM二级》模拟试卷二
FRM二级
模拟试卷
共 80 题
1565 次浏览
更新于 2026-09-28
一、单选题
根据题目描述选择正确答案
1
Deposit accounts are the number one source of funds at most banks. Important indicators of management’s effectiveness are whether or not funds deposited by the public have been raised at the lowest possible cost and whether sufficient deposits are available to fund all those loans and projects management wishes to pursue. There are plenty of differences between transaction and non-transaction deposit types. Regarding transaction versus non-transaction deposit types, which of the following statements is TRUE?
- A.The least popular transaction deposit among all types is the certificate of deposit.
- B.Negotiable order of withdrawal (NOW) accounts, which can be held only by individuals and nonprofit institutions.
- C.Core deposits include transaction accounts and all non-transaction accounts, and core deposit belongs to Tier 1 regulatory capital.
- D.Compared to non-transaction deposits, transaction deposits are generally provided a more stable funding base.
2
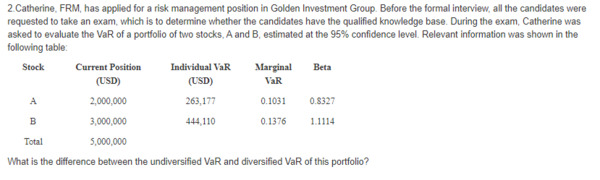
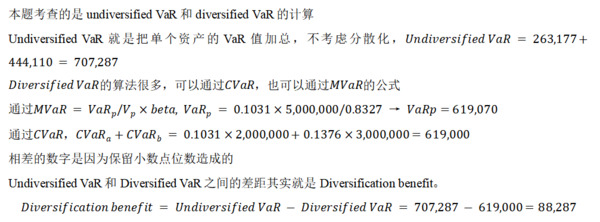
- A.USD 67,539
- B.USD 88,287
- C.USD 101,233
- D.USD 5,444
3
Togashi Yoshihiro and Takeuchi Naoko are students of Waseda University, majoring in Financial Engineering. They had just finished a fixed income course, which addressed the difficult concepts about MBS/ABS products, structured products, and the history of 2007-2008 financial crisis. They learnt that several parties played critical roles in the crisis. These parties were having some sort of frictions with each other, which contributed to the crisis. Takeuchi disagreed with Togashi on the interpretation of these complex frictions, especially the frictions between arranger, credit rating agencies (CRA) and investor. She claimed:“Firstly, the role of arranger is played by special purpose vehicles rather than commercial banks.Secondly, the arranger has more information about the quality of the mortgage loans than third parties so they may securitize bad loans and keep the good ones themselves. This phenomenon is called information asymmetry rather than predatory lending.Finally, you said that credit rating agencies were totally innocent, but in my opinion, credit rating agencies had honest errors. They didn’t pay enough attention on rapid financial innovation and complexity, and lost the independence of rating agencies due to the so-called issuer-pay fee structure.”How many statements that Takeuchi made is(are) most likely incorrect?
- A.One
- B.Two
- C.Three
- D.None
4
Michael S. Dunham and his colleague Theresa L. Gutman is debating on the performance of debt and equity of Company Dragon-Fruit under different circumstances using the Merton model. Company Dragon-Fruit has two debt issues outstanding: a senior debt and a subordinate debt. Both of them agree that the current market environment is good for Dragon-Fruit, and the company is expanding rapidly. Under the Merton model framework, Michael claims that the subordinate debt will perform like equity and since firm volatility increases at the moment holding other factors constant, the value of subordinate debt will decrease. Theresa argues that the subordinate debt will perform like senior debt, and when interest rate increases holding other factors constant, the value of subordinate debt will increase. Which of these two statements is/are most likely correct?
- A.Only Michael\u2019s is correct.
- B.Only Theresa\u2019s is correct.
- C.Both statements are correct.
- D.Neither of them is correct.
5
Analyst Mary wants to improve his short-term interest rate simulation by employing Model 2. The time step in his model is one month, dt = 1/12. His Model 2 also makes three assumptions.1) The initial or current (t0) short-term rate is equal to 3.00%.2) The annual basis-point volatility is 220 basis points.3) The annual drift is +100 basis points.In the first step of his first trial, the random uniform variable is 0.0793 such that, via inverse transformation, the associated random standard normal value is -1.410[NORM.S.INV(7.93%) = -1.410. ]What level does the rate evolve in the first month, r(1/12)?
- A.1.976%
- B.2.188%
- C.2.768%
- D.3.128%
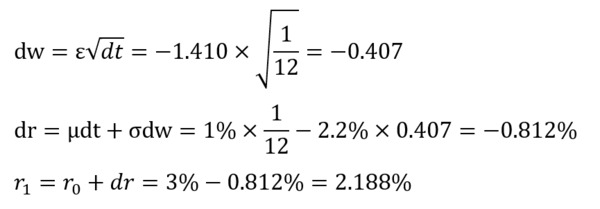
6
A risk analyst expects that the volatility of the market will surge compared to the historical standard deviations of the market. The risk analyst compares several historical simulation methods to choose the best one for calculating VaR and makes the following statements.Statement I: Non-parametric method is not subject to covariance matrix estimation.Statement II: Non-parametric approaches are more intuitive and conceptually simple than parametric methods.Statement III: Semi-parametric approaches are better than non-parametric methods when incorporating current market volatility estimates instead of using historical data directly.Which of the following statement is most likely correct?
- A.Both I and II
- B.Both I and III
- C.Both II and III
- D.All of the above
7
An investor who is based and reported on the British Pound wants to create a short position on the correlation among component stocks in S&P 500 index. According to the historical data, the country’s equity market and quoted currency value usually moves inversely. Which of the following descriptions about the strategies is most likely correct?
- A.Buying put options on individual components of the index, meanwhile selling put options on the index. Then buying the Quanto option with the strategy payoff above as underlying.
- B.Buying call options on the index, meanwhile selling call options on individual components of the index. Then buying the Quanto option with the strategy payoff above as underlying.
- C.Buying call options on individual components of the index, meanwhile selling call options on the index. Then exchanging the profit from the strategy above into the domestic currency with the current exchange rate at that time.
- D.Buying put options on the index, meanwhile selling put options on individual components of the index. Then exchanging the profit from the strategy above into the domestic currency with the current exchange rate at that time.
8
After the 2007–2009 global financial crisis, regulation about the over-the-counter (OTC) derivative market was tightened in order to reduce the systematic risk of overall markets. Thus, a set of regulation reform measures according to Basel III standard was taken to improve the soundness and robustness of the entire financial markets. Based on the Regulation Reform of the Basel III Standard, which of the following statements is least likely correct?
- A.Swaps, as the traditional OTC derivatives, are mainly cleared bilaterally.
- B.A majority proportion of derivatives are cleared in CCP after the Basel III Reform
- C.Margins are mandatory for those derivatives which are cleared bilaterally.
- D.An improved transparency in the information of the whole derivative market is one of the objectives of the Reform of the Basel III Standard.
9
Illiquidity can arise due to the following market imperfections: Clientèle effects and participation costs, transaction costs, search frictions, asymmetric information, price impact, or funding constraints. Therefore, we can characterize the effects of these imperfections as "illiquidity." Concerning the characteristics of illiquid markets, which of the following statements is true?
- A.Normally liquid markets periodically become illiquid.
- B.Most individuals hold the majority of their wealth in highly liquid assets.
- C.Most asset classes are liquid such that genuinely illiquid markets tend to be small and temporary.
- D.Technology has virtually eliminated the following frictions: transaction costs, search friction, asymmetric information, price impact, and funding constraints.
10
Golden Wind (GW) hedge fund is a mid-sized hedge fund which AUM (asset under management) is around $200 million. GWfocuses on fixed-income investment and fixed-income relative value strategies. In order to enhance the flexibility of investment and hedge credit risk, GW has various OTC derivative positions, such as credit default swap, credit-linked notes, forward, interest rate options, etc. The private-issued bond of Stone Ocean Co. is a large position that GW hedge fund allocates recently. Stone Ocean Co. is a mining company which is the industry leader and has the largest market share. It is to be noted that the fluctuations of commodity market and funding liquidity dry up would be crucial for mining industry. Stone Ocean Co. is an end user in OTC derivative markets to hedge positions and having various line of credit will be vital for its operations. Ripple derivative company is the major counterparty of Stone Ocean Co. for OTC derivatives and there is a netting scheme and two-way CSA between Ripple derivative company and Stone Ocean Co.Tom Feng, FRM, a senior portfolio manager at GW hedge fund, focuses on the bond position of Stone Ocean Co. He hedges these bonds with a short position in Stone Ocean Co.’s equity because Feng thinks that unfavorable information will negatively affect both equity price and bond price. Unfortunately, the value of the debt falls, but the value of equity does not fall as expected, so Feng and his fund make a huge loss. Based on Merton’s debt valuation model,consider the following circumstances:I. Interest rates increased.II. Volatility of firm value fell.III. Volatility of firm value increased.IV. A liquidity crisis increased the liquidity component of the credit spreads.Which circumstances according to Merton Model are possible explanations for why Feng’s hedge does not work out?
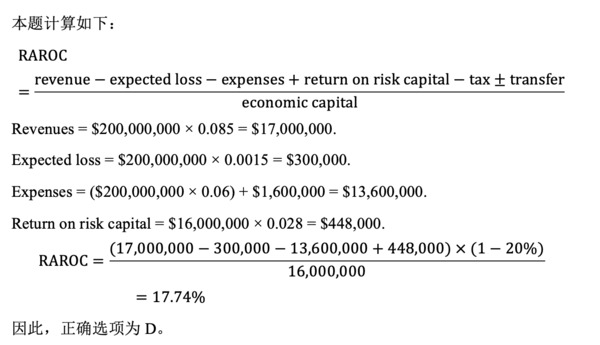
- A.I and II only
- B.I and III only
- C.I, III, and IV only
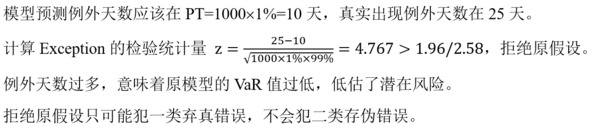
- D.III and IV only
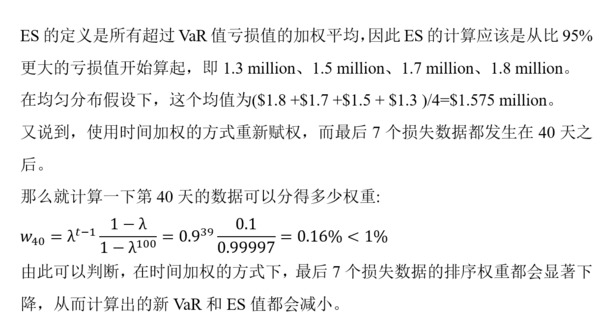
11
Golden Wind (GW) hedge fund is a mid-sized hedge fund which AUM (asset under management) is around $200 million. GWfocuses on fixed-income investment and fixed-income relative value strategies. In order to enhance the flexibility of investment and hedge credit risk, GW has various OTC derivative positions, such as credit default swap, credit-linked notes, forward, interest rate options, etc. The private-issued bond of Stone Ocean Co. is a large position that GW hedge fund allocates recently. Stone Ocean Co. is a mining company which is the industry leader and has the largest market share. It is to be noted that the fluctuations of commodity market and funding liquidity dry up would be crucial for mining industry. Stone Ocean Co. is an end user in OTC derivative markets to hedge positions and having various line of credit will be vital for its operations. Ripple derivative company is the major counterparty of Stone Ocean Co. for OTC derivatives and there is a netting scheme and two-way CSA between Ripple derivative company and Stone Ocean Co.One of the largest markets for Stone Ocean Co. is European market that 23.4% gross income is from trading with European manufacturers. Not only commodity price volatility, but also currency risk is a large risk for Stone Ocean Co.’s operation. In order to hedge the currency risk and market risk, Stone Ocean Co. has large number of OTC positions with Ripple derivative trading company, an American company. Which one of the following transactions will be a wrong-way exposure for Ripple derivative trading company?
- A.Stone Ocean Co. long a six-month FX forward which long EUR at 1.85USD\/EUR with Ripple derivative trading company.
- B.Stone Ocean Co. buys a three-month plain-vanilla EUR\/USD currency option for it to long USD at a certain FX rate from Ripple derivative trading company.
- C.Stone Ocean Co. enter into a payer commodity swap that it pays the return of gold index and receives a fixed rate from Ripple derivative trading company.
- D.Stone Ocean Co. buys a three-month plain-vanilla USD\/EUR currency option for it to long IDR at a certain FX rate from Ripple derivative trading company.
12
Golden Wind (GW) hedge fund is a mid-sized hedge fund which AUM (asset under management) is around $200 million. GWfocuses on fixed-income investment and fixed-income relative value strategies. In order to enhance the flexibility of investment and hedge credit risk, GW has various OTC derivative positions, such as credit default swap, credit-linked notes, forward, interest rate options, etc. The private-issued bond of Stone Ocean Co. is a large position that GW hedge fund allocates recently. Stone Ocean Co. is a mining company which is the industry leader and has the largest market share. It is to be noted that the fluctuations of commodity market and funding liquidity dry up would be crucial for mining industry. Stone Ocean Co. is an end user in OTC derivative markets to hedge positions and having various line of credit will be vital for its operations. Ripple derivative company is the major counterparty of Stone Ocean Co. for OTC derivatives and there is a netting scheme and two-way CSA between Ripple derivative company and Stone Ocean Co.There is a sudden shock to the Stone Ocean Co. The accident death of CEO leads the operation and corporate governance into chaos. In addition, the breakout of Covid-XX makes the price of commodity sharply volatile. Stone Ocean Co. falls to make payments in one of the OTC derivative contracts with Ripple derivative trading company. Which of the following statements regarding counterparty risk and netting is correct?
- A.Stone Ocean Co. can use close-out netting which can protect itself from risk contagion.
- B.Within the netting scheme, the close-out netting can protect Ripple derivative trading company because it ceases all transactions and value netting the remaining contracts. However, close-out netting may negatively affect Golden Wind hedge fund.
- C.Although the netting scheme is between Stone Ocean Co. and Ripple derivative trading company, Golden Wind hedge fund will have benefit from it.
- D.Close-out netting is used in daily settlement in CCP that CCP will pay the amount to the position who has gains and make the margin call to the position who lose money.
13
Golden Wind (GW) hedge fund is a mid-sized hedge fund which AUM (asset under management) is around $200 million. GWfocuses on fixed-income investment and fixed-income relative value strategies. In order to enhance the flexibility of investment and hedge credit risk, GW has various OTC derivative positions, such as credit default swap, credit-linked notes, forward, interest rate options, etc. The private-issued bond of Stone Ocean Co. is a large position that GW hedge fund allocates recently. Stone Ocean Co. is a mining company which is the industry leader and has the largest market share. It is to be noted that the fluctuations of commodity market and funding liquidity dry up would be crucial for mining industry. Stone Ocean Co. is an end user in OTC derivative markets to hedge positions and having various line of credit will be vital for its operations. Ripple derivative company is the major counterparty of Stone Ocean Co. for OTC derivatives and there is a netting scheme and two-way CSA between Ripple derivative company and Stone Ocean Co.Jorge T. Sisemore, FRM, a risk analyst for GW hedge fund, is currently looking into different alternatives and credit derivatives to invest or to transfer credit risk, rather than holding his pure fixed-income portfolio unchanged. Moody’s has recently lowered the credit ratings of several Jorge’s holdings. GW hedge fund’s CIO, Dawn P. Haskins, is concerning Jorge’s holdings will be affected heavily and agrees on Jorge’s decision to hedge the current exposures using three potential derivatives: total return swap, credit default swap and credit-linked notes. During Jorge’s discussion with his colleagues regarding which derivatives to invest in, he makes the following statements:Statement I: A total return swap is equivalent to a synthetic long position in the underlying asset for the credit risk seller.Statement II: Total return swap receiver bears all risks, including credit risk and market risk.Statement III: If Jorge wants to transfer the credit risk of the holdings, he could either buy credit default swap or buy credit-linked notes to buy credit protection and sell credit risk.Which of the statements made by Jorge is/are most likely correct?
- A.II only
- B.I and II
- C.I and III
- D.II and III
14
Culture is an unreal and sensitive topic in a corporation. Below are statements regarding definition and execution of culture. Which statement is wrong?
- A.Culture includes four elements, namely conduct and behaviors, values and ethics.
- B.Culture should be delivered by mechanism and shaped by conduct.
- C.Culture could be executed through key areas: senior accountability and governance; performance management and incentives; staff development and promotion; effective three lines of defense.
- D.Culture could be easily measured in a quantitative way.
15
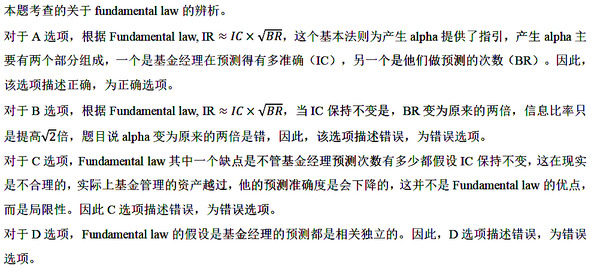
A new fund manager assistant has been asked to collect the information about creating alpha relative to a benchmark by making bets that deviate from that benchmark. Grinold’s fundamental law of active management states that the maximum information ratio can be attainable. Which of the following statement about Grinold’s fundamental law is correct?
- A.The fundamental law offers a guideline to generate alpha by two components, one is how good fund managers have to be at forecasting and the other is how many bets they have to make.
- B.According to fundamental law, if the information coefficient keeps constant when the fund manager makes two times the breadth of the strategy, he can create two times the alpha before.
- C.One advantage of the fundamental law is that the information coefficients are assumed to be constant across the breadth of the strategy which means even if the assets under management increase, the ability to generate information coefficients can be maintained.
- D.An important limitation of fundamental law is that it assumes that the forecasts are dependent on each other which is not close to reality.
16
An internal auditor at a large bank is reviewing the bank’s economic capital framework to ensure that it meets best practices. The auditor identifies deficiencies in the bank’s governance framework as well as the process used to determine the firm-wide economic capital and asks the CRO to suggest corrective actions that conform with best practices. Which of the following actions should the CRO recommend?
- A.Require business unit managers to challenge the assumptions for their unit\u2019s capital model before providing final approval.
- B.Calculate the bank\u2019s aggregate economic capital by summing its exposures for different risk types.
- C.Incorporate a set of escalation procedures into the bank\u2019s contingency plan for its economic capital policy.
- D.Discourage the use of macroeconomic scenarios developed by third-party vendors to stress test economic capital models.
17
Enterprise risk management (ERM) framework could supply a useful and effective view on the risk-return tradeoff for firms, especially the large and diversified conglomerates. In details, firms need to distinguish risks which would be retained and risks which would be transferred. Which of the following statements is/are correct?I. Management should retain strategic and business risks in which the company has a comparative advantage but diversify risks that can be hedged inexpensively through the capital markets.II. When proposing new projects, business unit managers must evaluate all major risks in the context of the marginal impact of the project on the firm’s total risk.
- A.Statement I only.
- B.Statement II only.
- C.Both statements are correct.
- D.Both statements are incorrect.
18
Too many stress tests can hide the risk of a portfolio, but a fair number of stresses is important to develop a comprehensive view of the risks in the portfolio. More integrated stress tests can be generated by combining the credit risk view with the loan portfolio, or the market risk view of counterparty credit risk can be combined with the trading book. Which of the following statements about stress test for counterparty exposures is most likely correct?Ⅰ. A financial institution can stress the probability of default similarly to the loan case by stressing the probability of default or the variables that affect probability of default, including company balance-sheet values, macroeconomic indicators and values of financial instruments.Ⅱ. In addition to considering just current exposure, the financial institution must consider including the probability of default over the time horizon and the EPE in its stress-test framework.Ⅲ. To capture the full impact of various scenarios on CVA profit and loss, a financial institution should include the liability side effects in the stress as well.
- A.\u2160, \u2161 and \u2162
- B.\u2160 and \u2161
- C.\u2160 and \u2162
- D.\u2161 and \u2162
19
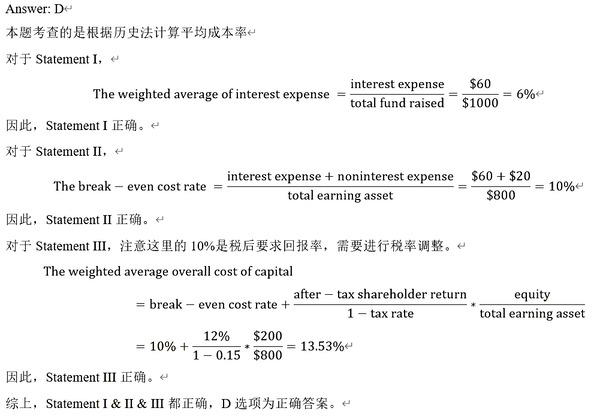
Michael is estimating the total financing cost included deposit and non-deposit funds. By reviewing the bank’s past expense, he concluded that the following table: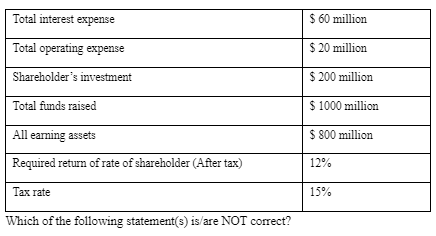
- A.Statement II & Statement II
- B.Statement I & Statement II
- C.Statement I & Statement III
- D.None
20
Rosenfeld Savings is attempting to determine its liquidity requirement. The bank has classified its checking, savings, and nonperson time deposits into three categories: hot money, vulnerable, and stable (aka, core) funds: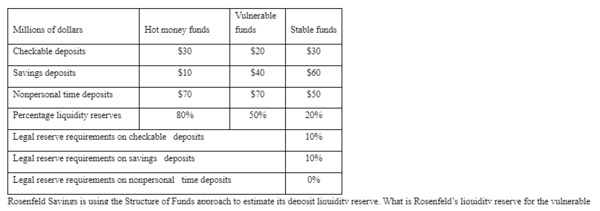

- A.$13.0 million
- B.$30.0 million
- C.$62.0 million
- D.$177.0 million
21
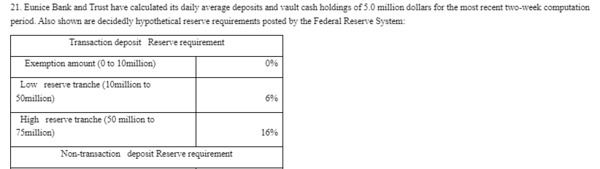
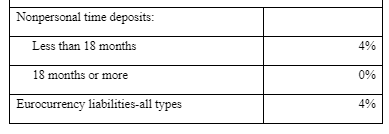
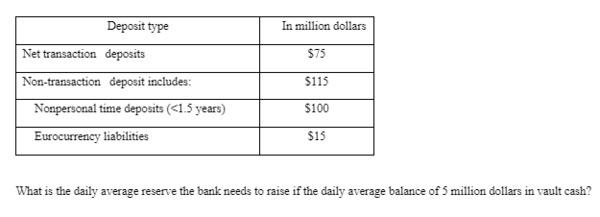
- A.$6.0 million
- B.$9.5 million
- C.$12.5 million
- D.$23.0 million
22
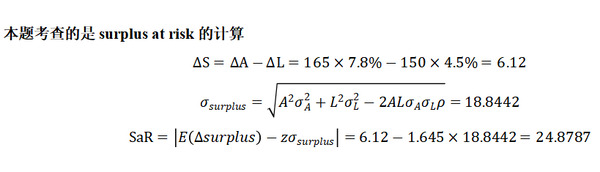
SkyLine Airways has a defined benefit pension scheme with assets of $165 million and liability of $150 million. The annual growth of the liabilities is expected to be 4.5% with 2.4% volatility. The annual return on the pension assets has an expected value of 7.8% with 12% volatility. The correlation between asset return and liability growth is 0.35. What is the 95% surplus at risk for SkyLine?
- A.$24.8787million
- B.$54.8198million
- C.$18.8456million
- D.$6.1234million
23
At the initiation of a repurchase agreement (repo), Bank Holly sells a security to Bank Wood for settlement on June 1st, 2022 at an invoice price of USD 180.0 million. At the same time, Bank Holly agrees to repurchase the security three months later, for settlement on September 1st, 2022, at a purchase price equal to the original invoice price plus interest at a repo rate of 0.90%. Using the actual/360 convention of most money market instruments, which is nearest to the repurchase price?
- A.$414,000,000
- B.$180,000,000
- C.$180,414,000
- D.$181,620,000
24
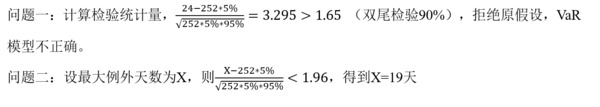
A commercial bank constructed a backtest of 95% daily VaR and observed 24 exceptions (the number of days where the daily P&L loss exceeded the VaR) over last 252 trading days. Normal distribution is applied for the purposes of model verification. What is the result of hypothesis testing for the model under a 90% two-tail test? And what is the most exceptions that can be observed to make sure that the bank can accept the VaR model under 95% two-tail test?
- A.accept under 90% confidence level, and the most exceptions are 19
- B.accept under 90% confidence level, and the most exceptions are 17
- C.reject under 90% confidence level, and the most exceptions are 19
- D.reject under 90% confidence level, and the most exceptions are 17
25
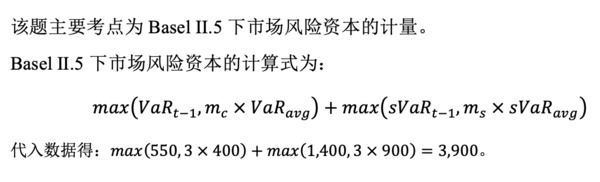
Owing to the global financial crisis in 2008, the Basel Committee amended the market risk framework and added an extra stressed VaR requirement. Assume a bank used the internal model approach for market risk charge and had developed the following risk measures (in USD million) for the trading book positions: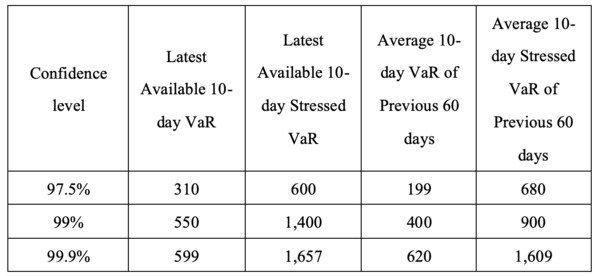 The regulators have set the multiplication factors values to three for both VaR and Stressed VaR. The capital charge for general market risk is closest to:
- A.USD 1,950 million
- B.USD 3,900 million
- C.USD 6,635 million
- D.USD 9,885 million
26
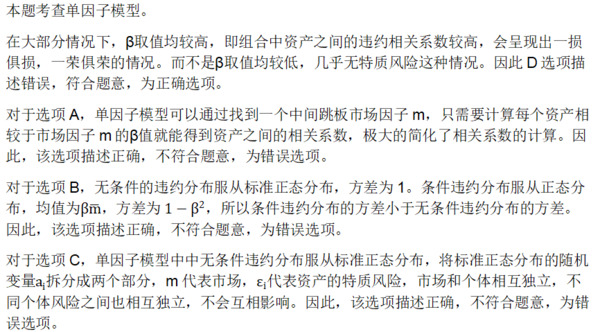
The single-factor model, since it is a structural model, emphasizes the correlation between the fundamental driver of default of different firms. Default correlation in that model depends on how closely firms are tied to the broader economy. Which of the following statements about the single factor model is least likely correct?
- A.The single-factor model enables us to value default correlation through the credit’s beta to the market factor.
- B.The conditional variance of the default distribution is , so the conditional variance is reduced from the unconditional variance of 1.
- C.The single-factor model lets idiosyncratic risk play a role and the idiosyncratic risk is not dependent on the change in the market factor and on other firm’s shocks.
- D.In less extreme cases, there is no statistical relationship to the market factor, so idiosyncratic risk is nil, then the loss rate will very likely be very close to the default probability p.
27
When we apply the Gaussian copula utilized for financial model, which of the following statements is least accurate?
- A.The Gaussian copula assumes a low tail dependence which is an unrealistic, because dependencies will sharply increase in a crisis.
- B.The Gaussian copula is difficult to calibrate to market prices and to calibrate CDO tranches with a single correlation model.
- C.The Gaussian copula is principally static and consequently allows only limited risk management; there is no stochastic process for the critical underlying variables\u2019 default intensity and default correlation.
- D.The Gaussian copula is limited to market risk applications, but in credit risk there is no theoretical way to assume these values when they are pairwise default correlations.
28
The staff at Umbrella Street Bank, which is a commercial bank, produces several liquidity risk reports on a daily, weekly, monthly, and quarterly basis. Among these liquidity risk reports is a deposit tracker report. Among the following metrics, which is most likely to appear in their deposit tracker report?
- A.In the deposit tracker report, there is not only the current size of deposits but also the forecast of what the level of deposits is expected to be going forward.
- B.This deposit tracker report provides an idea of the Loan-to-deposit (LTD) ratio in the immediate short term and LTD ratio (current and forecast) usually has a lower bound of 120%.
- C.Market-to-book ratio of common equity (current and forecast) versus investor communicated target of 1.30.
- D.The leverage-adjusted duration gap (current and forecast) versus board-approved upper ceiling of 3.5 years.
29
Bank of Redrock, a fractional-reserve bank, is concerned about the funding liquidity risk. William, the head of the Assets and Liabilities Management Committee, is to search for information about the liquidity risk. which of the following statements is incorrect?
- A.Funding liquidity risk arises for market participants who borrow in short term to finance investments that require a longer time to become profitable.
- B.The core function of a commercial bank is to take deposits and provide commercial and industrial loans to non-financial firms, and in doing so, the bank carries out transformations in liquidity, maturity, and credit.
- C.The balance-sheet situation of a market participant funding a longer-term asset with a shorter-term liability is called a maturity mismatch.
- D.A properly calibrated asset-liability management system can fully immunize the fractional-reserve bank against loss of confidence in its ability to pay out depositors.
30
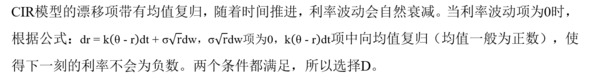
Analyst Johnson is evaluating various short-term interest rate models. Two primary criteria that he is told to meet is that:1) To avoid a model that will produce a negative short-term rate, where current short-term rate is set to zero.2) To make a model that will simulate a gradually decreasing volatility level.Which of the following approaches can help Johnson to meet the criteria?
- A.He can use Ho-Lee model and increase the convexity effect input assumption.
- B.He can assume a non-normal distribution like lognormal distributed rates.
- C.He can employ shadow rates which will set the negative rate as zero.
- D.She can assume a Cox-Ingersoll-Ross (CIR) model
31
Erik and Eric, two analysts within an investment firm, are discussing operational resilience, a new concept within the whole risk industry. Below are their comments on operational resilience. Which ones are right?I. Impact tolerance is a good measure to test operational resilience.II. Operational resilience is a kind of ability of firms to respond to disruptions.III. Continuity of business service is an essential component of operational resilience.IV. The objective of operational resilience is to maintain the firm’s systems and processes.V. The assumption of operational resilience is that disruptions will seldom occur.
- A.I II IV
- B.I II III
- C.II III IV
- D.II III V
32
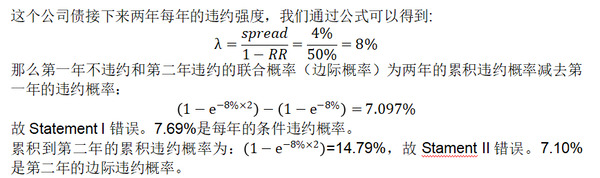
Cheryl Stjohn, a risk manage intern, just joined a credit rating agency. Although she learnt several quantitative methods to calculate the default probability for different issues and issuers, she has no practical experience in doing such thing. On her second week after joining the company, she was asked by her director Richard Coleman to estimate the implied default probability for a 2-year BB rated corporate bond using intensity model. The continuously compounded spreads are given in the following table: The recovery rate on that BB rated bond is expected to be constant at 50% in the event of default. Before send her report to Richard, there are two statements Cheryl is not certain. So, Cheryl asks her colleague’s opinions. Which of the following statements is/are the most likely correct?Statement I: The risk-neutral probability that the BB rated discount bond survives in the first year and then defaults in the second year is 7.69%Statement II: The risk-neutral probability that the BB rated discount bond defaults within the next 2 years is 7.10%
- A.Statement I
- B.Statement II
- C.Both Statements are correct
- D.Neither is correct
33
National Australia Bank (NAB), one of the largest Australia banks, suffered system shut down on Oct 19th, 2020. Information from social media showed NAB’s payment system, mobile bank and internet visiting were not available during that day. Millions of customers could not access to their banking accounts. It was not the first time for the kind of accident. The data shows the accelerating growth of the IT error from 1000 times in 2017 to 2300 times in 2020. Even Commonwealth Bank of Australia (CBA), the most state-of-the-art IT system owner, occurred system crash 2 times. Now Fat Cat Bank (FCB) takes the example above as a good external loss data resource. The operation team discusses the case carefully and summarizes lessons below:
- A.FCB should primarily avoid hardware damage to keep cyber resilience through system back-up.
- B.Impact tolerance will prevent failures of critical operational processes and the systems that support these processes.
- C.FCB could utilize impact tolerance to help the bank optimize its allocation of resources to its most important business services.
- D.NAB case should be classified to Clients, Products and Business Process (CPBP) operational risk event within categories of operation loss data. Which one is right?
34
After decades’ efforts, WALAWA Bank finally enters into tier-1 banks within the region and has introduced enterprise risk management (ERM). But recent two risk events alert the bank to improve its risk management. The heads of the bank gather a meeting to try guidelines for risk management. Below are opinions from these heads.CFO: Risk-based pricing for products and services should be promoted within the organization. This year, we need to introduce RAROC (Risk-adjusted Return on Capital) as a powerful tool to help us to select projects with risk department. As head of finance to manage financial risk, I will give the number of expected losses for RAROC calculation.CBO: We understand its importance of risk appetite framework (RAF) to the bank’s risk management. But its heavy work loading spent my lines business managers too much time. We all know the board has final responsibilities of risk management, why not let the board get RAF done.CIO: Cyber risk is coming! Recent two risk events have obvious logic chain with the cyber risk. So I need to build a special force within my IT department to fight with the support from risk department.CRO: As head of risk and supporter of ERM, I need to get more resources to build integrated risk department to handle all relevant risks. But I know resources is limited and should be allocated among various department, I am happy to talk to each senior managers to delegate my part of risk responsibility with you.CEO: We face more and more risk challenges. But board process is too long and late. The best way is to have part of independent power from the board to delegate to us to risk management in a flexible and timely way. So, I will launch meeting with the board to discuss.Whose opinion( ) is(are) right?
- A.CFO, CBO
- B.CIO, CEO
- C.All
- D.None
35
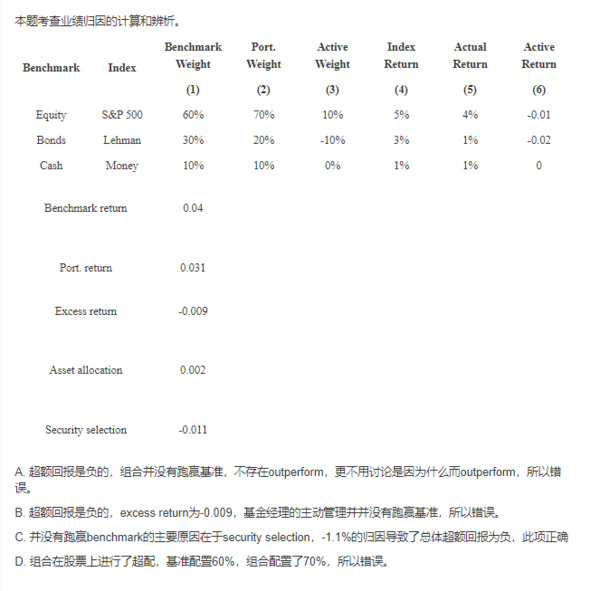
A portfolio manager’s “bogey” is a benchmark portfolio invested in three components: 60.0% in the S&P 500 (the equity index), 30.0% in a Lehman Bond Index (the bond index), and 10.0% in a money market fund (the cash index). The manager’s actual portfolio components included 70.0% in equities, 20.0% in bonds, and 10.0% in cash.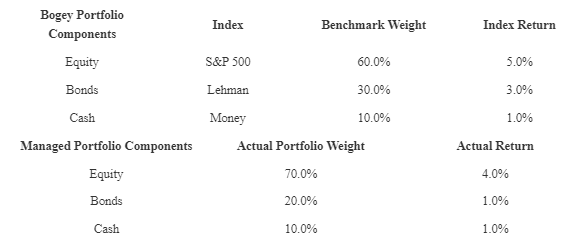 When evaluating an active manager’s performance, the excess return is usually decomposed into two components, asset allocation and security selection. Which of the following statements is CORRECT regarding performance attribution?
- A.The portfolio outperformed the benchmark due to better security selection.
- B.The excess return is 0.9% which indicates the outstanding active management of the manager.
- C.The failure of the active management can be attributed to poor security selection.
- D.The portfolio underweighted on equity compared with bogey portfolio.
36
Jenny makes an estimation that the underlying stock is currently at the volatility level of 25% per annum, and she has inputted the parameter into the Black-Scholes-Merton model to work out the European call option price as $4.88. While the market price of the call option is at $5.23. Now assuming a European put option with the same strike price and maturity on the same underlying stock. The put option has BSM model price output of $3.44 with the same volatility parameter input. What is the nearest price if the put option is traded in the market?
- A.3.09
- B.3.44
- C.3.79
- D.3.94
37
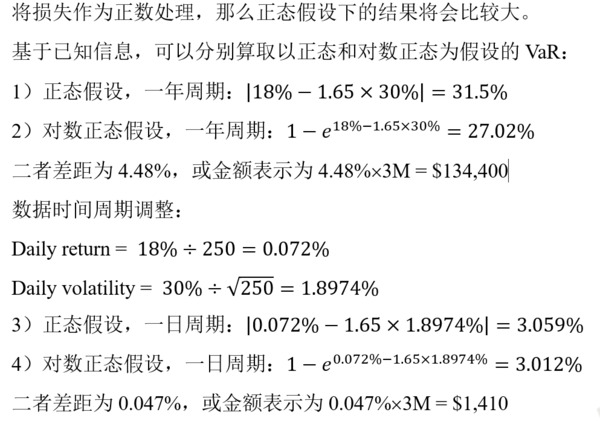
Andy, a senior risk manager, is now estimating the market risk of his portfolio with both the normal and lognormal distribution assumptions. He has gathered following information:Annualized expected return = 18%Annualized volatility = 30%Current portfolio value = $3,000,000Trading days within one year =250Confidence level: 95%Andy is curious about which of the two assumptions will lead the calculation outcomes much larger, and what is the differences between the two? (Setting the loss as positive amount)
- A.VaR in normal distribution assumption will be larger, and the differences are 0.47% on one-day time horizon.
- B.VaR in normal distribution assumption will be larger, and the differences are $134,400 on one-year time horizon.
- C.VaR in lognormal distribution assumption will be larger, and the differences are $1,410 on one-day time horizon.
- D.VaR in lognormal distribution assumption will be larger, and the differences are 4.48% on one-year time horizon.
38
A popular group of correlation options are multi-asset options. In the choices below, S1 is the price of asset #1 and S2 is the price of asset #2 at option maturity. K is the strike price, the price determined when entering into the contract, at which the underlying asset can be bought in the case of a call, and the price at which the underlying asset can be sold in the case of a put. For which of the following multi-asset options does an increase in correlation between the asset prices S1 and S2 imply an increase in the option price?
- A.Call on the maximum of two: Payoff = max [0, max (S1, S2) - K]
- B.Option on the worse of two: Payoff = min (S1, S2)
- C.Exchange option: Payoff = max (0, S2 - S1)
- D.Spread call option: Payoff = max [0, (S2 - S1) - K]
39
A bank has implemented a VaR model for its portfolio of commodity derivatives. The bank’s risk management unit would like to establish a process for the validation of this new model. Which of the following actions would be most appropriate for a validator to take as part of this process?
- A.Validate the model with the help of the model development team to leverage the team\u2019s expertise and experience with the model.
- B.Review the input parameters and analyze the operational processes and information technology systems that generate the model output.
- C.Ensure that traders have access to an independent market and risk data source so that they can determine VaR limits to be used in the model.
- D.Ensure that modeling assumptions remain constant over extended periods of time so that model output can be successfully backtested.
40
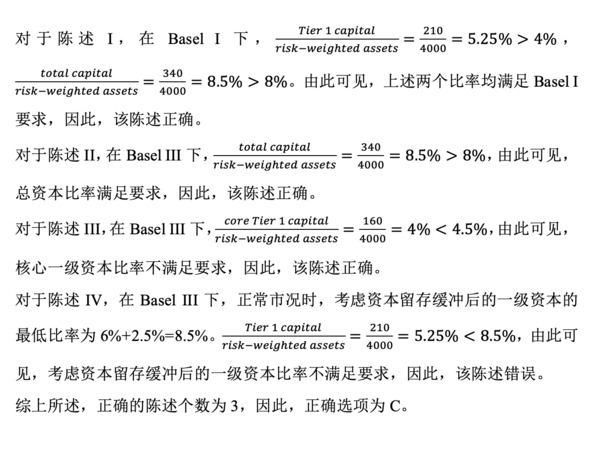
Golden bank carries risk-weighted assets (RWA) of 4 billion Euros. For regulator’s capital requirement, the bank holds:-160 million Euros of Common Equity Tier 1 Capital (CET-1)-50 million Euros of Additional Tier 1 Capital-130 million Euros of Tier 2 CapitalHow many statements below are right?I. The bank’s capital structure meets the bottom line capital requirement of Basel I.II. The bank’s total capital meets the bottom-line capital requirement of Basel III.III. The bank’s core Tier 1 capital does not meet the bottom line capital requirement of Basel III.IV. The bank’s Tier 1 capital meets the capital requirement of Basel III after considering the capital conservation buffer in normal times.
- A.1
- B.2
- C.3
- D.4
41
A regulatory analyst at a large multinational bank is examining regulatory requirements the bank must comply with under the Basel Committee’s FRTB guidelines. The analyst explores how the FRTB guidelines evolved from the Basel I and Basel II.5 frameworks as well as the instructions for applying the guidelines. Which of the following is correct regarding the FRTB?
- A.While Basel I and Basel II.5 allowed market risk to be calculated at the trading desk level, FRTB requires that market risk be calculated on a firm-wide basis.
- B.While Basel I and Basel II.5 emphasized the use of a standardized approach to calculating market risk, FRTB encourages each bank to develop and rely on an internal models approach.
- C.FRTB standardizes the liquidity horizon used for all risk factors in the market risk capital calculation as 10 days, rather than the different horizons used in Basel I and Basel II.5.
- D.FRTB requires that the stressed ES measure be used in determining market risk capital, rather than the VaR and stressed VaR measures that were used in Basel I and Basel II.5, respectively.
42
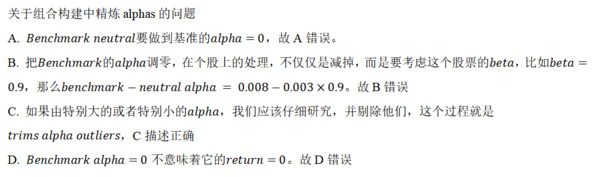
Aoi Banerjee, CIO of Sagittarius Fund (a fund managing several large portfolios investing in EMEA market), is concerned that some of these portfolios may have previously unidentified biases in their alphas. She asked a senior analyst to prepare a presentation on process of refining alpha and benchmark neutralization alpha for the portfolio managers. Regarding the process of scaling the alphas, trimming alpha outliers, and benchmark neutralization, which of the following statements is correct?
- A.For a benchmark-neutral alpha, the benchmark has an alpha of one.
- B.In order to reach benchmark-neutral, if the benchmark has alpha of 0.003, the stock should subtract 0.003 from the original alpha (i.e., if the stock has an original forecast alpha = 0.8%, alpha after benchmark-neutralization = 0.008-0.003=0.005)
- C.Very large positive or negative alphas can have undue influence, we should closely examine them and trim these outliers.
- D.When the benchmark portfolio has an alpha of zero, the benchmark return is 0%.
43
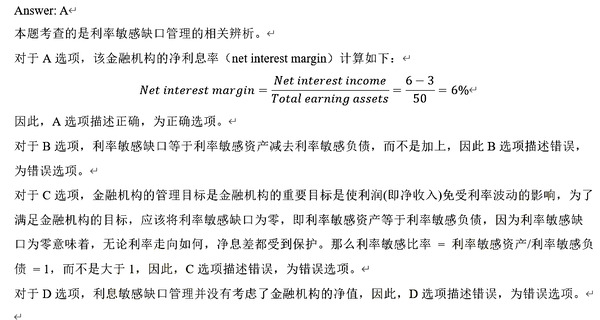
Tom, FRM, a manager under asset-liability committee of financial institution, is aggressively searching ways to insulate asset and liability portfolios and the profits from the ravages of changing interest rates. The financial institution is dealing with the important goal which is to insulate profit (i.e., net income) from the effects of fluctuating interest rate. To meet the goal, Tom collects some data of his financial institution and applies interest-sensitive gap management as the hedge strategies. 6 billion dollars in interest revenues from its loans and security investment, 3 billion dollars in interest expense paid out to attract borrowed funds and it holds 50 billion dollars in earning assets. Which of the following statement Tom made is correct?
- A.The financial institution’s net interest margin calculated from the data Tom collected is 6%.
- B.Interest sensitive gap equals to interest sensitive assets plus interest-sensitive liabilities.
- C.To meet the financial institution’s goal, Tom should maintain the interest sensitivity ratio greater than one.
- D.The biggest advantage of interest-sensitive gap management is that this method considers both net income and net worth of the financial institution.
44
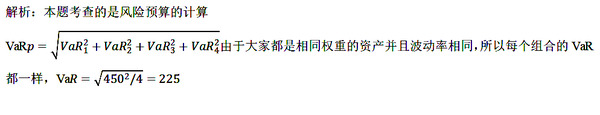
Annette, FRM is an independent financial risk consultant providing risk management solutions for large pension fund. These days, Annette was hired by a pension fund named Silver Fund to tackle issues regarding risk budget. The pension fund is considering the risk budget among four portfolios which are equally weighted and all have 5% annualized volatility. How much risk budget should be allocated to each portfolio if all portfolios are uncorrelated? Assume the the annual VaR risk budget for the whole fund is $450 million using 95% confidence level.
- A.$112.5 million
- B.$225 million
- C.$50.625 million
- D.$68.18 million
45
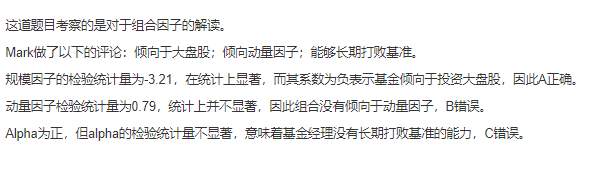
Lee, a risk analyst from RUMs, collected the past performance of Neptune Endowment emerging market portfolio and generated a report to Mark Shaw, who would be delegated to manage the portfolio in one month. The market returns are derived from MSCI Emerging Markets Index. The key information from the factor regression is shown in the following table: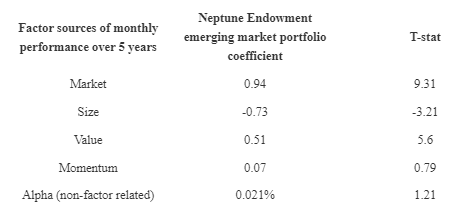 After reviewing the key information, Mark made the following short comments regarding the Neptune Endowment emerging market portfolio:üOrientation of large size stocksüMomentum factor tiltüBeat the benchmark in long runWhich of Mark’s comments about the portfolio is most accurate?
- A.Orientation of large size stocks
- B.Momentum factor
- C.Beat the benchmark
- D.None
46
Rosenfeld's startup company has built a new electronic financial platform that enables participants to trade derivatives on certain cryptocurrencies. Rosenfeld knows that market participants have a strong preference for continuous liquidity, and participants will avoid a market that suffers lack of liquidity. Rosenfeld is preparing a marketing brochure to promote the new exchange. If her goal is to promote the exchange's well-functioning liquidity features, which feature contributes to a stable market concerning liquidity?
- A.Stop loss rules
- B.Trend trading
- C.Liquidity black hole
- D.Negative feedback traders
47
Netting is a traditional way to mitigate counterparty risk where there may be a large number of transactions of both positive and negative value with either a single counterparty (bilateral netting) or multiple counterparties (multilateral netting). Close-out refers to the process of terminating and settling contracts with a defaulted counterparty. Which of the following statements about netting and close-out is least likely correct?
- A.In general, netting can be seen as a method of aggregating obligations whilst keeping market risk constant (or close to constant), but reducing settlement risk, counterparty risk, operational risk, liquidity risk, and systemic risk.
- B.A modern-day equivalent of clearing rings in OTC derivatives markets is portfolio compression, which achieves multilateral netting benefits via the cooperation of multiple counterparties.
- C.Netting could not only reduce the exposure of OTC derivatives counterparties but also reduce the exposure of other creditors.
- D.Close-out netting allows the surviving institution to realize gains on transactions against losses on other transactions immediately and effectively jump the bankruptcy queue for all but its net exposure.
48
Covered interest parity (CIP) is a physical law in international finance that hold the interest rate differential between two currencies should equal the differential between the forward and spot exchange rates. But it has been violated since 2014 and many bankers are studying why. And this law is related with the FX swap, cross-currency swap and cross-currency basis swap. Which of the following statement is correct about this issue?
- A.An FX swap is a long-term instrument, and in this kind of swap, the borrowed amount is exchanged at the initial spot exchange rate at both the beginning and maturity. And in the cross-currency swap the borrowed amounts exchanged at the spot rate and repaid at the pre-agreed forward rate at maturity.
- B.In a cross-currency basis swap, during the life of the swap, the counterparties periodically exchange interest payments. The party who receives non-US dollar currency at initiation usually pays interest based on the reference rate which is the respective Libor rates plus the basis.
- C.The demand for currency hedges from banks, institutional investors and non-financial firms are the main explanation to why the basis does not close.
- D.After the great financial crisis, the new constraints on arbitrage activity such as the regulation changes, the cost and risk increase, and the structural changes in pricing are the main driver to cause swap basis to opens up.
49
Several banks are currently trying to automate their lending decision making process using machine learning.Wally Wong is a student of University of Pennsylvania, majoring in Computer & Cognitive Science. When she applied for the credit risk summer internship program in Morgan Stanley, she wrote following sentences in her cover letter to convince HR of her thorough understanding of algorithms and models in machine learning and artificial intelligence:“Altman’s Z-score model is used commonly nowadays and we can easily get z-score for public firms from Bloomberg. With this approach, algorithm is given a great deal of data on firms and whether they have defaulted, and then it come up with a rule for distinguishing between those firms that default from those that do not.The most significant advantage of this model is that it is a nonlinear discriminant analysis model which can explore nonlinear relationship between features and dependent variable. Moreover, there is no need to worry about overlapping zone because Z-score model can provide perfect classification.There are some complex algorithms increasingly used in risk management such as neural networks. Neural networks algorithm tries to simulate the behavior of the human brain, to mimic human’s fuzzy logic and to learn from success or failure outcomes over time.However, complex algorithms also have some shortcomings, such as black box. It is hard for any human to understand and audit from outside, and to examine step by step how results are obtained.”Which of the concepts Wally Wong shared in her cover letter is inaccurate?
- A.The introduction of Altman\u2019s Z-score model
- B.The advantage of Z-score model
- C.The concept of neural networks
- D.Black box
50
A risk management team of a large investment bank is running a risk control of bank’s counterparty risk. The bank has a large number of counterparties and demands a better counterparty risk management system. Different managersare suggesting different credit risk mitigation methods: netting, collateral, and central counterparty, and they made the following statements on their risk report to department head:Statement I: Since CCP offers great transparency, efficiency and a well-defined loss mutualization process, every member will be benefited. It can effectively mitigate systemic risk because OTC counterparty risk can almost be eliminated by CCP clearing.Statement II: When using collateral under Credit support Annex, an initial margin will more likely make the exposure overcollateralized. The bank should encourage counterparties to post initial margin to reduce counterparty risk, operational risk and funding liquidity risk.Statement III: Rehypothecation is the reuse of variation margin by margin payer. For end users, reuse of margin is common because they often involve in offsetting transactions.Which of these statements is/are most likely correct?
- A.Statement I only.
- B.Statement II only.
- C.Statement III only.
- D.None of three statements is correct.
51
The board of directors of an insurance company has identified a number of potential growth opportunities for the company to consider. To help assess these opportunities and determine an optimal risk structure to use across the organization, the risk committee has recommended that the company implement an ERM program. Which of the following would best represent an appropriate goal for the firm to state as part of the ERM program?
- A.Determine a risk-return trade-off that reflects the company\u2019s target credit rating and ensure that business unit managers evaluate new projects with this firm-wide target in mind.
- B.Attempt to eliminate the company\u2019s probability of financial distress to maximize company value.
- C.Maximize the firm's leverage ratio within its risk tolerance to ensure the highest expected return on equity.
- D.Establish a target minimum level of annual earnings and guarantee to shareholders that it will maintain this level.
52
As we know, the bank prefers economic capital as capital requirement to regulatory capital under standardized approach. Below are the reasons and advantages for economical capital except:
- A.Firm-wide economic capital considers correlation or diversification effect among different product portfolios and tends to be less than firm-wide regulatory capital of the same bank generally.
- B.Regulatory capital requirements are based on accounting capital rather than economic capital, thus if a bank with economic values higher than accounting values may be penalized, and the bank may have to retain higher amounts in liquid assets to cover the shortfall.
- C.Economic capital needs more resources to input to estimate the capital requirements compared to regulatory capital under standardized approach.
- D.Economic capital is more suitable for less-developed small bank and developed large bank more favor regulatory capital under standardized approach.
53
Billy Cox works in Dwarf Planet, a special purpose vehicle established by a Poland-based investment bank that was recently formed by the merger of three small investment banks in Poland, Belarus and Czech. A SPV is a distinct legal entity that is the “company” through which a securitization is undertaken, and to secure favorable tax treatment, Dwarf Planet is set up in Cayman Islands. After reviewing the underlying asset pool, Billy recommends credit enhancements for a better issuance.The following are excerpts from a recent internal document by Billy about the credit enhancements:1. Overcollateralization is one of the credit enhancement methods we can use. We can issue a par amount of ABSs that is smaller than the par amount of underlying collateral. This method provides credit enhancement for all of the bond tranches of a securitization.2. We can consider excess spread. Excess spread means that there is more cash flow received from the assets used to secure the issue than the interest paid to investors.3. We can also seek help from external support. Some composite insurance companies provide insurance policy (pool insurance) to cover the risk of principal loss in a collateral pool.4. Afterall, we should note that overcollateralization is soft credit enhancement while excess spread is hard credit enhancement.Which of the features about credit enhancement is incorrect?
- A.The description of overcollateralization
- B.The definition of excess spread
- C.The comparison between soft and hard credit enhancement
- D.The recommendation of external credit enhancement
54
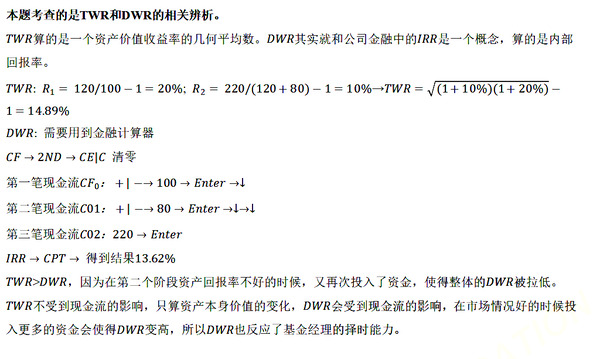
Eric, a fund manager of Jupiter Fund. After managing the fund for two years, he is requested by the limit partners of the fund to provide a comprehensive investment performance report. According to the reporting requirement, time-weighted return and dollar-weighted return should be applied simultaneously. Eric recalled his investment decisions as follows: He invested $100 million in an account, initially. After one year, the value of his investment was $120 million, and Eric added another $80 million into the account. At the end of Year 2, the total value of the investment was $220 million. Which of the following statements about the return calculation is CORRECT?
- A.If using dollar-weighted return as measurement, Eric will have a better performance.
- B.Dollar-weighted return is depressed because there is an investment before a period of relatively poor portfolio performance.
- C.Time-weighted return will be affected by cash withdrawals or additions.
- D.If funds are contributed to a portfolio at a favorable time, the time-weighted rate of return will increase.
55
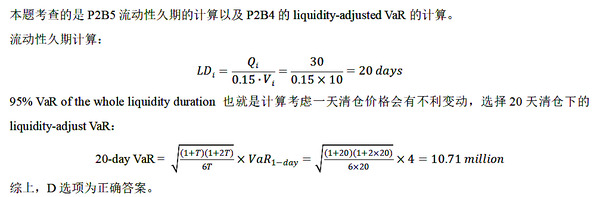
Afund manager of a pension fund manages a 30 million portfolio only including one security. Due to repay the pension funds to the investors, the fund manager needs to liquidate the portfolio. The assistant of the fund manager collects the information on that daily volume in that security is 10 million and one-day liquidation does not exceed 15% of the daily volume in that security can avoid a material adverse earning impact. During the liquidity duration, the fund manager equally liquates the positions and assumes the daily volatility keeps constant. Before liquidation, the 1-day 95% VaR of this portfolio is 4 million dollars. Please calculate the liquidity duration and convert the 1-day 95% VaR to the 95% VaR of the whole liquidity duration considering the adverse price impact. Liquidity duration 95% VaR of the whole liquidity duration
- A.3 days 6.93 million
- B.20 days 17.89 million
- C.3 days 4.99 million
- D.20 days 10.71 million
56
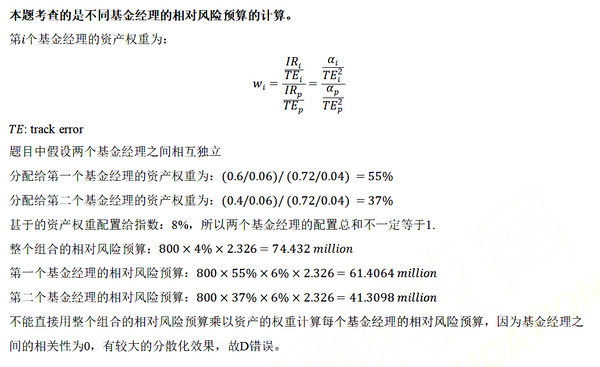
An endowment fund has received a donation of USD 800 million. The fund’s CIO has decided to invest the USD 800 million in a portfolio that contains two actively managed portfolios which managed by different active managers, both benchmarked to the same index. Currently, the CIO is trying to decide how to allocate the USD 800 million to these two active managers within the overall portfolio so as to maximize the resulting information ratio, subject to an overall 4% tracking error target. Relevant statistics for the two managers, the current overall portfolio, and the benchmark index are given in the following table: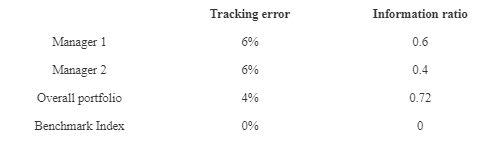 Assuming the active returns of the two managers are independent and normally distributed, which of the following statements is INCORRECT about the fund’s relative risk budget?
- A.The weights of the allocations to the managers do not necessarily have to sum to one.
- B.The relative risk budget for the whole fund is VaR $74 million at the 99% confidence level.
- C.37% of the $800 million will be allocated to Manager 2.
- D.The relative risk budget for Manager 1 is VaR $41 million at the 99% confidence level.
57
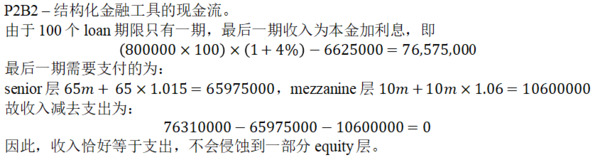
An underwriter structures a collateralized loan obligation (CLO) composed of 100 identical loans, each with a notional value of GBP 800,000 to be repaid in one year with an interest rate of LIBOR+3%. The CLO has one planned payment at maturity and its capital structure is given by: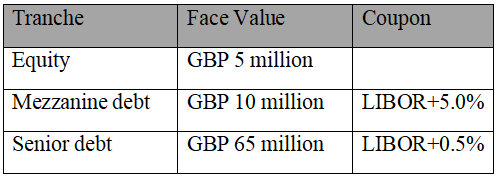 At maturity the CLO accumulates GBP 6,625,000 of losses from defaults and unpaid interest. If LIBOR was flat at 1% over the 1-year period, and assuming no recovery on the defaults, how would the losses be absorbed by the capital structure?
- A.The equity tranche will lose some of its value, and the other tranches will not be affected.
- B.The equity tranche will lose all of its value, and the other tranches will not be affected.
- C.The equity tranche will lose some of its value, and the mezzanine tranche will lose some of its value.
- D.The equity tranche will lose all of its value, and the mezzanine tranche will lose some of its value.
58
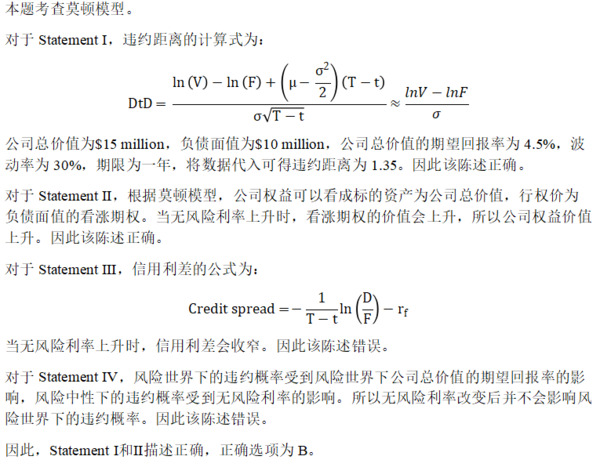
An analyst is employing the Merton model to estimate the default probability. The capital structure of the firm consists of two parts: zero-coupon debt with a face value of $10 million and the rest of is equity. The firm current asset value is $15 million with an expected return of 4.5% per annum with continuous compounding. The volatility of the firm’s assets is 30% and the risk-free rate is 3%. Which of the following statements is most likely correct?Ⅰ. The approximate distance to default of the firm is 1.35 for one year horizon.Ⅱ. An increase in the risk-free rate will increase the firm’s equity market value.Ⅲ. The credit spreads widens as interest rates increase.Ⅳ. An increase in the risk-free rate will decrease the risky world default probability.
- A.Ⅰ, Ⅱ and Ⅲ
- B.Ⅰ and Ⅱ
- C.Ⅰ, Ⅲ and Ⅳ
- D.Ⅰ, Ⅱ and Ⅳ
59
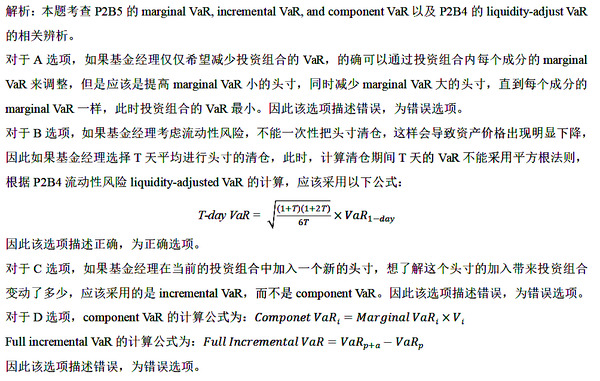
In portfolio risk management, there is a systematic application of VaR to many sources of portfolio risk. VaR was developed as a methodology to measure portfolio risk initially andover time, risk managers have discovered that they could use the VaR process for active risk management by using marginal VaR, incremental VaR, and component VaR. What’smore,the calculation of VaRcanalsoconsider liquidityrisk.which of the statement about VaR tools is correct?
- A.If the fund manager only wants to reduce the portfolio VaR, he can allocate more for the position with the highest marginal VaR and allcate less for the position with the lowest marginal VaR.
- B.When considering liquidity risk, the fund manager usually uses T days to equally liquidate the position of the portfolio, and in this situation, we also cannot calculate T-days VaR by using the square root rule to convert the time horizon from the 1-day portfolio VaR.
- C.If the fund manager adds a new position to the current portfolio, he can calculate the component VaR to measure how the portfolio VaR changes.
- D.Both the component VaR and full revaluation of incremental VaR can be calculated from marginal VaR.
60
Basel III introduces two buffers to reduce procyclicality and build-up additional capital in normal time that can be drawn down in periods of stress respectively. Which of the following statements concerning the two buffers is (are) correct?I. Basel III introduces a capital conservation buffer of 2.5% (of RWA) consisting of common equity Tier 1 capital.II. Basel III introduces a countercyclical capital buffer of between 0% and 2.5% (of RWA) to be determined by respective national supervisory authorities.
- A.Neither I nor II.
- B.Only I.
- C.Only II.
- D.Both I and II.
61
Peter is an analyst who works for a hedge fund. Unlike many of his peers from business school, who work for funds that cannot much drift from their somewhat narrowly defined investment styles, Peter’s fund has broad discretion with respect to both location of opportunity and trade tactics. However, his fund does tend to make directional bets in liquid, often highly liquid, markets. For which type of hedge fund does Peter most likely work?
- A.Equity market neutral
- B.Global macro
- C.Convertible arbitrage
- D.Distressed debt
62
Sammi Li, CFA, FRM, CQF, is a manager in treasury department of a small bank, Bank Capricorn. She is monitoring and managing quantitative liquidity risk by using the term structure of expected cash flows and the term structure of expected cumulated cash flows. She collects the data in the following chart: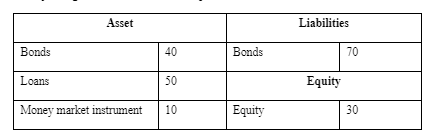
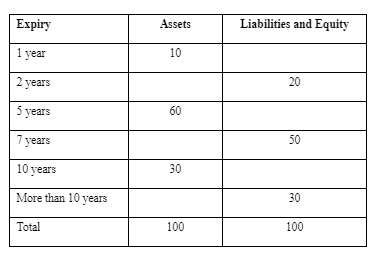 According to the information Sammi collected, which of the following statement is correct?
- A.The term structure of expected cash flows only describes as in the chart of the relationship between positive expected cash flows and the date up to expiry.
- B.When the bank is interested in how the past dynamic evolution of net cash flows affects its total cash position on that date, Sammi should use the term structure of cumulated expected cash flows to analyze.
- C.According the information in the above chart, there is no negative cumulated expected cash flows period in the term structure.
- D.When the term structure of expected cash flows shows negative values on an expected basis, this means that the bank may become insolvent.
63
A bank issues a $200,000,000 loan with the following characteristics:■ Loan pays a fixed annual interest rate of 8.5%.■ The interest expense associated with the loan is 6.0%.■ The operating cost to the bank’s commercial lending division is $1,600,000.■ Economic capital required to support the loan is $16 million, which is invested in T-bills paying a rate of 2.8%.■ The expected loss associated with the loan is 15 basis points per year.■ The effective tax rate is 20%.What is the risk-adjusted return on capital (RAROC) for this loan?
- A.11.21%.
- B.13.89%.
- C.16.65%.
- D.17.74%.
64
Thomas Wood, FRM, joins Falent Investment as junior risk analyst. He is dispatched to the credit risk quant team. He and his colleague discuss how to deal with credit risk mitigation more effectively. They make the following four statements:1. The credit value adjustment (CVA) is defined as the present value of the expected value or price of counterparty credit risk.2. A greater CVA value represents a cost to one party who bears a greater propensity to credit loss of his counterparty.3. Implementing a netting scheme will be more effective than increasing collateral to lower credit risk.4. Setting minimum transfer amount and posting collateral will help lower CVA.Which of the sentences that Thomas Wood says is(are) correct?
- A.Sentence 1 & sentence 2
- B.Sentence 1, 2, &3
- C.Sentence 1
- D.Sentence 2&3
65
Jackson is an employed risk analyst who is evaluating the latest back-testing results of his firm’s VaR. The back-testing is based on the framework for conditional coverage model on one-year statistical test. Which of the following is the most likely reason to be the justification for a shift to a conditional coverage model?
- A.Exception days are clustering and bunching over 2 weeks.
- B.Evidence of the existence of a long-run inconstant volatility.
- C.Sample size is not large enough to generate low probability of Type I and Type II error.
- D.Previous two-tail hypothesis test method which may trigger null hypothesis rejection when too many or too little exceptions happen.
66
Basel II requires a back-testing of a bank’s internal value at risk (VaR) model (IMA). Assume the bank’s ten-day 99% VaR is $1.35 million. The null hypothesis is that VaR model is accurate under two-tailed 95% or 99%confidence interval. Out of 1,000 observations, 25 exceptions are observed.
- A.True VaR should be higher than $1.35 at the confidence level of 99%, but we risk a Type I error.
- B.True VaR should be higher than $1.35 at the confidence level of 95%, but we risk a Type II error.
- C.True VaR should be lower than $1.35 at the confidence level of 99%, but we risk a Type I error.
- D.True VaR should be lower than $1.35 at the confidence level of 95%, but we risk a Type II error.
67
Lucy, FRM, is a quantitative analyst and recently uses historical simulation to estimate the 95% expected shortfall of certain risky portfolio. She firstly takes 100 trading-days loss data, and assumes empirical loss/profit distribution as a uniform distribution, and collects data as follows.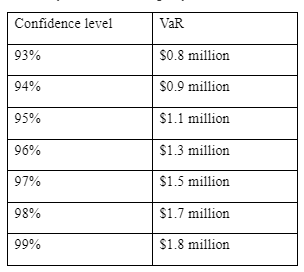 Before she calculates the expected shortfall, she finds that all of the seven largest loss data happened from 40 to 60 trading days ago. According to the age-weighted historical simulation method with decay rate of 0.9, which of the following statements is most likely correct (Setting the loss as positive amount)?
- A.The expected shortfall is $1.575 million under uniform distribution, and will become larger under age-weighted method.
- B.The expected shortfall is $1.575 million under uniform distribution, and will become smaller under age-weighted method.
- C.The expected shortfall is $1.1 million under uniform distribution, and will become larger under age-weighted method.
- D.The expected shortfall is $1.1 million under uniform distribution, and will become smaller under age-weighted method.
68
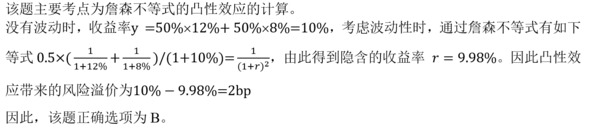
Assuming the current one-year interest rate is 10.0%. In each of the next two years, the rate will either increase or decrease by 2.0% with equal probabilities. It is expected that the rate will either increase to 12.0% or decrease to 8.0% in the next year due to volatility. If there is no volatility, the term structure of the interest rate will stay flat, indicating current one-year interest rate is equal to the one-year spot interest rate starting one year from now. What is the absolute yield change regarding spot interest rate starting one year from now owing to convexity effect implied by Jensen's Inequality (Assuming interest rate is compounded annually)?
- A.0
- B.2 bp
- C.10 bp
- D.12 bp
69
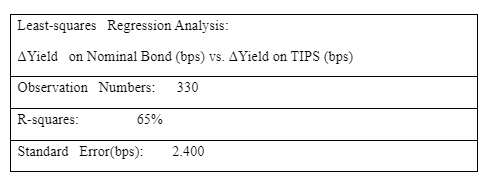
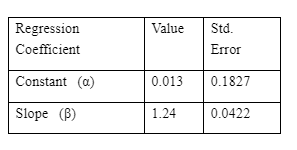
Assuming a trader has currently bought $100 million of nominal Treasury bond. Since he holds the belief that the bond markets will go bearish and hedging protection is necessary, he decides to take a face amount of TIPS based on either DV01-hedge or single-variable regression method. The regression results are shown as below: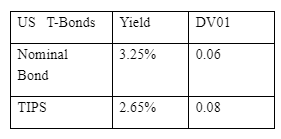
 Which of the following statements is least likely considered as correct?
- A.According to the model, the correlation estimation between changes in the two kinds of bonds is about 80.62%.
- B.Given the 95% confidence level, the trader should give up the beta coefficient of 1.24 and accept 1.0 as the true value.
- C.The trader should short $75 million of TIPS bonds based on the DV01-hedge method.
- D.The difference between a DV01-hedge and a regression hedge is about $18 million of the TIPS bonds.
70
The senior management team of a small regional bank has established a committee to review procedures and implement best practices related to entering into significant contracts with third-party vendors. The committee is reviewing one proposed relationship with a third-party vendor who would have a significant responsibility for marketing the bank’s financial products to potential customers. In establishing policies to reduce the operational risk associated with this potential vendor contract, which of the following recommendations would be most appropriate?
- A.The bank should review all third-party audit reports of the vendor that are publicly available.
- B.The bank should ensure that the vendor's sales representatives are compensated mainly with commissions from the sale of the bank\u2019s products.
- C.The bank should prevent the third-party vendor from gaining access to any of its critical services and processes.
- D.The bank should be responsible for developing the vendor's contingency planning process to mitigate risk exposure to the vendor.
71
To understand the volatility in foreign currency options, an FRM candidate collects the volatility data of foreign currency options to draw the graph showing the relationship between implied volatility and K/S0 along with the implied and lognormal distribution for foreign currency options. Since the graph illustrates volatility skewness, the analyst finds out that there is a negative correlation between equity prices and volatility. Which of the following statements is least likely correct?
- A.Volatility smile is present for the foreign currency options based on empirical results.
- B.The price of a deep in-the-money call option valued by implied distribution is higher compared to lognormal distribution.
- C.The implied distribution has heavier left tail and lighter right tail than lognormal distribution.
- D.The implied volatility is relatively low for at-the-money options.
72
Assume we map an option portfolio of long call options only to delta and vega. What is the impact to our mapped exposures of a sharp decline in the underlying asset price?
- A.Gain in value due to both risk factors
- B.Gain in delta mitigated by loss in vega
- C.Loss in delta mitigated by gain in vega
- D.Loss in value due to both risk factors
73
Fürstentum Bank (FB), a bank with operations in Germany, Switzerland and Austria, is currently preparing for business expansion and reviewing its portfolios containing several credit-risky securities. Edmund Freitag, a junior risk analyst at FB, distributes the documentations to the risk management team for reviewing. The credit-risky securities that FB holds are bonds, commercial papers, off-balance-sheet exposures such as guarantees and several CDSs. Freitag shares the information he collected to help the risk management team to establish an overview of developed portfolio credit risk models. He says:Sentence I: “One of the most developed portfolio models is Credit Portfolio View model by McKinsey. This model is a top-down model which focuses on the effect of macroeconomic factors on portfolio credit risk.”Sentence II: “KMV model is also a well-developed portfolio credit risk model. The essential feature of this model is the distance to default (DD), which is an application of the Merton approach to estimate the probability of default.”Sentence III: “Another model I want to introduce is CreditRisk+ by Credit Suisse. This model is a mark-to-market model which considers changes in market values and ratings changes. The mark-to-market model is more superior because it takes any movement in the market value of the bond or in the credit rating into considerations.”Which of the sentences that Freitag says is(are) correct?
- A.I&II
- B.III
- C.I&III
- D.II&III
74
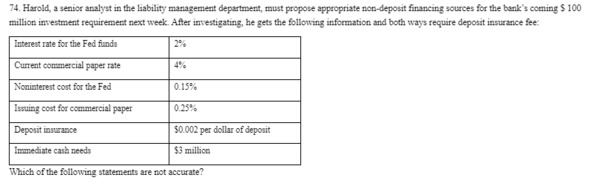
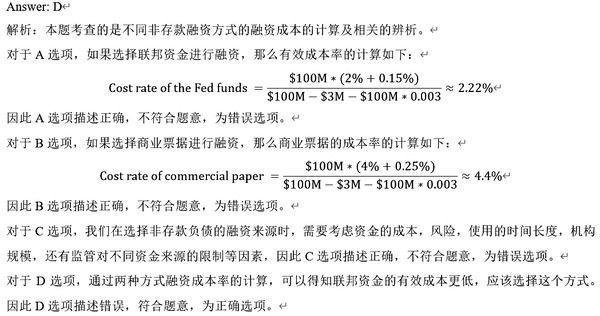
- A.The effective cost rate of the Fed funds is 2.22%.
- B.The effective cost rate of the commercial paper is 4.4%.
- C.When choosing the alternative nondeposit sources, we should consider the factors including cost rate, risk (i.e., volatility and dependability of the funding source), length of funds needs and so on.
- D.Harold should suggest the commercial paper for financing due to the lower effective cost rate.
75
After financial crisis, capital supplement becomes the major trend for large banks. But turbulence financial market delays the process. People realize the system should mobilize more capital channels to fill the capital hole.One possible channel banks favor is CoCo bond. But the Deutsche bank CoCo crisis made investors have big concerns on the tool.Another possible channel is capital conservation buffer, which allow banks to gather money in flexible market time.Xuan Zhang, Zhen Zhang, 2 senior analysts of Forget Your Money Bank, were assigned the job to assess the capital inject plan. Below are their discussion results.
- A.Both CoCo bond and capital conservation buffer have same effects on the bank\u2019s capital structure.
- B.Capital conservation buffer is better than the CoCo bond on the bank\u2019s capital supplement.
- C.Capital conservation buffer is better than the CoCo bond on the cost of capital.
- D.The capital percentage of capital conservation buffer is the same as the CoCo bond.
76
John, a risk management analyst, who works in an investment bank, predicts that the market has gone through such a volatile period, which is quite different from the past. He proposes to choose an appropriate non-parametric historical simulation to adapt to the forecasted market. Which of the following statements about the non-parametric model is least correct?
- A.Age-weighted historical simulation helps to reduce ghost effects.
- B.Volatility-weighted historical simulation produces risk estimates that are appropriately sensitive to current volatility estimates.
- C.Correlation-weighted historical simulation adjusts historical returns to reflect changes between historical and current correlations.
- D.Filtered historical simulation works badly than weighted historical simulation.
77
Aeolos Fund manages two European equity portfolios and the benchmark for both is MSCI Europe Index. Two portfolios are managed by two different active managers. At the end of the year, RMUs appraise the performance of two active managers. During the monitoring process, RMUs discuss the characteristics of different performance evaluation methods. Which of the following statements regarding the performance evaluation methods is INACCURATE?
- A.Jensen\u2019s alpha is the excess return on the portfolio over and above the predicted by the CAPM.
- B.If RMUs focus on performance measurement of active management, an indicator which measures the excess reward per unit of risk earned by deviating from the benchmark\u2019s holdings will be suitable and information ratio should be recommended.
- C.M2 is an improved measure of risk that the volatility of portfolio matches the volatility of the benchmark.
- D.In order to measure the excess reward per unit of systematic risk incurred, RMUs should choose Sharpe ratio to appraise the performance.
78
Bach Barthélemy got an interview opportunity from the recommendation by his ESSEC business school alumnus. After the first phone interview, the risk manager Laurent Gérard sent Bach a small case to test his capacity of Python. Bach was asked to draw the expected exposure of four different position by Python. Based on features of these different instrument, Bach used Monte Carlo Simulation to simulate the distribution of these instrument and then draw the diagrams of expected exposure. Which of the following diagrams of expected exposure is most likely incorrect?
- A.FX forward contract
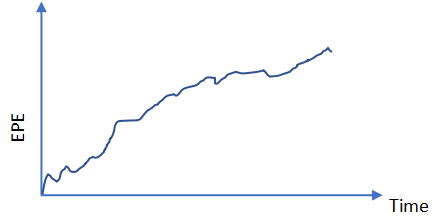
- B.interest rate swap paid quarterly and received semi-annually
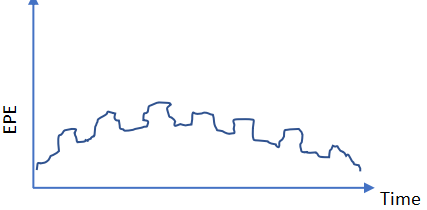
- C.Credit Default Swap
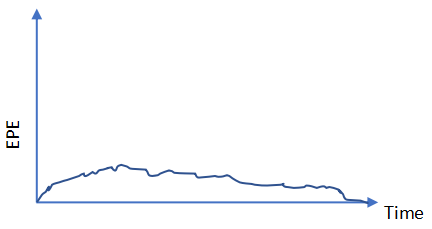
- D.Cross currency swap
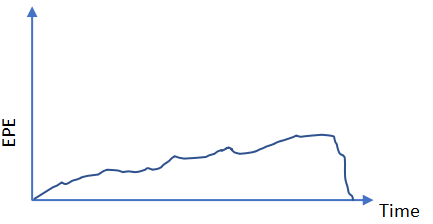
79
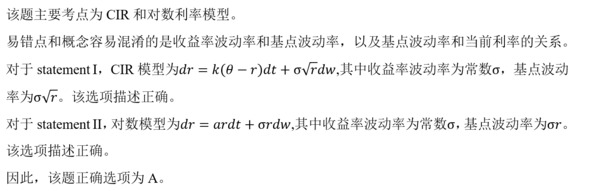
Jim works in a financial company that has recently bought large numbers of fixed-rate bonds. He wants to choose appropriate interest rate models to hedge the interest rate risk. After analyzing some models with time-dependent volatility, the CIR and lognormal models come into his consideration. Which of the following statements regarding the characteristics of these two models is (are) most likely correct?Statement I: The CIR model has a constant yield volatility and the basis volatility increases proportionally to the square root of interest rate.Statement II: The lognormal model has a constant yield volatility and the basis volatility increases linearly with interest rate.
- A.Both I and II.
- B.Only I
- C.Only II
- D.Neither I nor II
80
Leo, a risk head of a local commercial bank, is reviewing the developments of Basel I~ Basel III and gives his comments below. Which one is wrong in these comments?
- A.From Basel I to Basel III, the standardized approach for credit risk measurement did not change too much except risk weights more granular, asset types more comprehensive.
- B.From Basel I to Basel III, the standardized approach for market risk measurement changed dramatically from traditional standardized approach which focuses on asset classification and risk weights to risk factor sensitivity approach.
- C.From Basel I to Basel III, the approaches for operational risk measurement adjusted to internal model approach.
- D.From Basel I to Basel III, Basel II.5 was a unique version since it only covered market risk measurement in order to respond urgently to the 2008 global financial crisis.
输入阅读码
查看答案与解析需要输入阅读码