2025年FRM金融风险管理师《FRM一级》模拟试卷三
FRM一级
模拟试卷
共 100 题
3375 次浏览
更新于 2026-09-26
一、单选题
根据题目描述选择正确答案
1
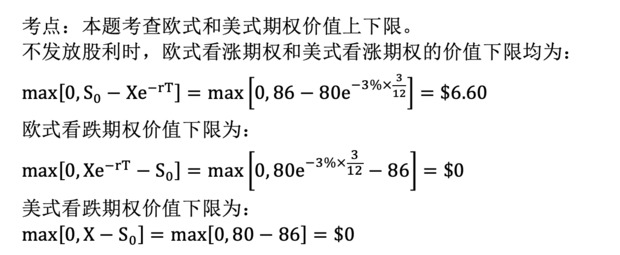
What are the minimum values of an American-style and a European-style 3-month call option and put option with a strike price of $80 on a non-dividend-paying stock trading at $86 if the risk-free rate is 3%?American call European call American put European put
- A.$6.00 $6.00 $6.00 $6.00
- B.$6.60 $6.60 $6.00 $6.60
- C.$6.00 $6.60 $0 $0
- D.$6.60 $6.60 $0 $0
2
Suppose the current stock price is USD 18. The price of a European call option with strike price USD 20 that will mature in three months is USD 3. The price of a European put with the same strike price and time to maturity is USD 4, while the three-month risk free rate is 2% per year (annually compounded). Assume the stock on which the options are written provides no dividends. What kind of actions should an arbitrageur take to capture an arbitrage opportunity?
- A.Long the call, short the risk-free bond, long the put, and short the stock.
- B.Short the call, long the risk-free bond, short the put, and long the stock.
- C.Short the call, short the risk-free bond, long the put, and long the stock.
- D.Long the call, long the risk-free bond, short the put, and short the stock.

3
Peter, senior manager in operational risk management apartment in Red Rever Bank. Peter learns that in Basel II, banks can use advanced measurement approach to calculate the operational regulatory capital. And he draws the loss distribution of his bank, which is a positively skewed distribution andthedotted line representsthemode, meanandmedianofthelossdistribution, respectively.Which part of the distribution is the operational regulatory capital?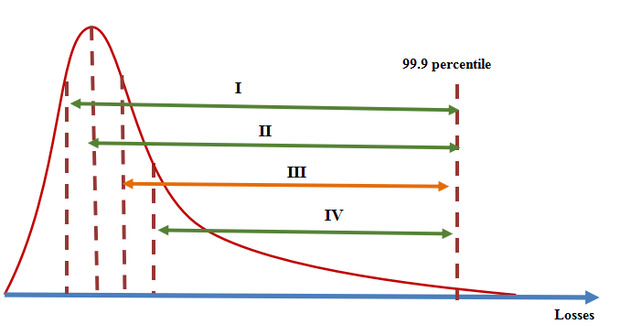
- A.I
- B.II
- C.III
- D.IV
4
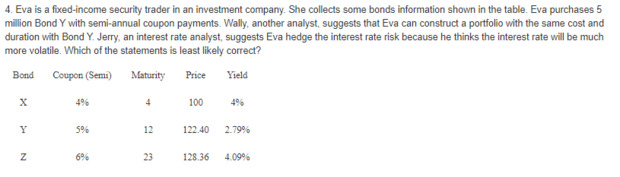
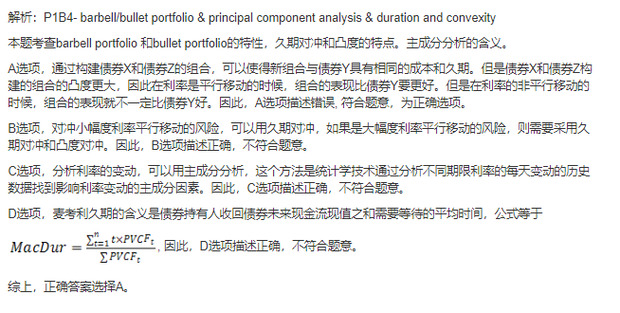
- A.With the same cost and duration of Bond Y, Eva could use Bond X and Bond Z to construct a barbell portfolio which has a bigger convexity than Bond Y. And the portfolio will outperform Bond Y in both parallel and non-parallel shifts of interest rate term structure.
- B.Eva is considering hedging the risks of parallel shift of the interest rate. Jerry suggests Eva, if the parallel shift is small, we can do duration-based hedge but if the parallel shift is big, we need to do duration and convexity-based hedge.
- C.Jerry also suggest Eva to learn Principal Component Analysis to analyze the shift of interest rate, which is a statistical technique that looks at the historical data of daily movements in interest rates of various maturities and identifies certain factors.
- D.Eva wants to use the formula to calculate the Macaulay duration of the Bond Y, the formula is
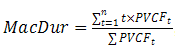 , which means the average time the bondholder has to wait before receiving the present value.
5
Isabelle Burns, FRM, is an investment advisor for a firm whose client base is composed of high-net-worth individuals. In her portfolio, Burns has an investment in Torex, a company that has developed software to speed up internet browsing. Burns has thoroughly researched Torex and believes the company is financially strong yet currently significantly undervalued. According to the GARP Code of Conduct, Burns may:
- A.not recommend Torex as long as she has a personal investment in the stock.
- B.not recommend Torex to a client unless her employer gives written consent to do so.
- C.recommend Torex to a client, but she must disclose her investment in Torex to the client.
- D.recommend Torex to a client without disclosure as long as it is a suitable investment for the client.
6
A risk consultant is reviewing the role of regulatory arbitrage in the 2007 credit crisis to better understand the lessons learned as a result of the crisis. Which of the following best describes how regulatory arbitrage took place in the mortgage securitization market?
- A.Banks securitized mortgages and then invested in tranches of these MBS to get more favorable treatment for capital purposes.
- B.Mortgage originators were required to purchase a portion of MBS equity tranches, which were then offered in the secondary market.
- C.Pension funds that invested in mortgage securities were required to hold only securities rated AAA and above.
- D.Mortgage originators were encouraged to offer adjustable-rate mortgages to subprime borrowers with initial low \u201cteaser\u201d rates.
7
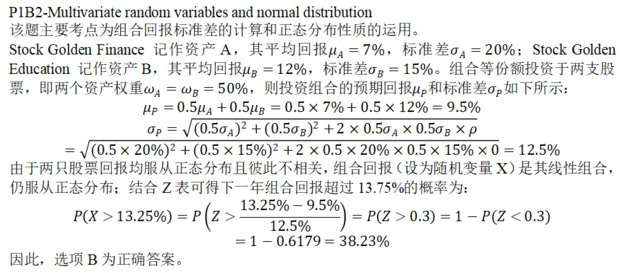
Stock Golden Finance has a mean return of 7% and a standard deviation of returns of 20%; Stock Golden Education has a mean return of 12% and a standard deviation of returns of 15%. Both stocks have their returns normally distributed and uncorrelated with each other. Tao Feng, FRM, decides to equally invest into these two stocks. What is the probability that the portfolio return over the next year will be greater than 13.25%?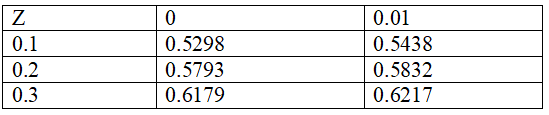
- A.42.07%
- B.38.23%
- C.63.79%
- D.57.93%
8
Warrants, convertibles and employee stock options are option-like securities that the holders can exercise the right to obtain shares at predetermined price. Compared to typical options traded by the CBOE, which of the following statements is most likely correct?
- A.Convertible bonds and employee stock options are issued by companies and traded on exchanges.
- B.Employee stock options usually issued out of the money on the grant date if an employer promises that they will be granted on future dates.
- C.The number of options traded on the CBOE is not predetermined while a predetermined number of options are issued for warrants and convertibles.
- D.When these securities are exercised, the companies don\u2019t need to issue new shares.
9
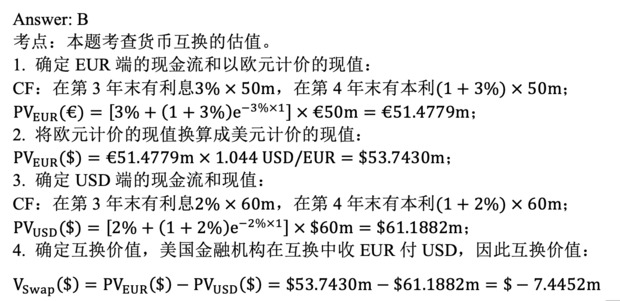
A U.S. financial institution entered into a 4-year currency swap contract with a French industrial company. Under the terms of the swap, the financial institution receives interest at 3% per year in EUR and pays interest at 2% per year in USD. Payments and receipts are made at the end of the year. The principal amounts are EUR 50 million and USD 60 million, and interest payments are exchanged once a year. Suppose that it is exactly one year before expiration of the swap contract and just in time for the year 3 cash flow payments and receipts when the exchange rate is USD 1.044 per EUR 1, the 1-year French risk-free rate is 3.0%, and the 1-year US Treasury rate is 2.0%. Assuming continuous compounding, what is the value of the swap to the financial institution at the end of year 3?
- A.USD -7.603 million
- B.USD -7.445 million
- C.USD -7.068 million
- D.USD -6.921 million
10
A company is expected to announce the terms of a materially important contract negotiation in early April. A trader expects the company's stock to be range-bound until then and has entered into a position that is short 100 March calls with a strike price of USD 50 and long 100 April calls with a strike price of USD 50. After some consideration, the risk committee believes there is a possibility that the news will be released in mid-March and informs the trade of this change. Based on the new information, the trader sells the 100 April calls with a strike at USD 50. He also buys 50 March calls with a strike at USD 30 and 50 March calls with a strike at USD 70. What types of positions did the trader have?
- A.The original position was long a call spread and the final position was long a strangle.
- B.The original position was long a calendar spread and the final position was long a butterfly spread.
- C.The original position was long a reverse calendar spread and final position was long a call spread.
- D.The original position was long a calendar spread and the final position was short a butterfly spread.
11
The market portfolio has the Sharpe ratio of SRM, an investor formed a portfolio by borrowing 30% at the risk-free rate and then investing in the market portfolio, the Sharpe ratio of this leveraged portfolio is SRP, which of the following is correct?
- A.The leveraged portfolio is not on the efficient frontier, SRP
- B.The leveraged portfolio is not on the efficient frontier, SRP=SRM.
- C.The leveraged portfolio is still on the efficient frontier, SRP
- D.The leveraged portfolio is still on the efficient frontier, SRP=SRM.
12
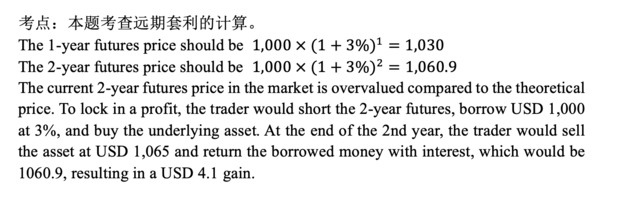
A trader in the arbitrage unit of a multinational bank finds that a financial asset is trading at USD 1,000, the price of a 1-year futures contract on that asset is USD 1,030, and the price of a 2-year futures contract is USD 1,065. Assume that there are no cash flows from the asset for 2 years. If the term structure of risk-free interest rates is flat at 3% per year, which of the following is an appropriate arbitrage strategy? (with annual compounding)
- A.Short 1-year futures contracts and long 2-year futures contracts
- B.Short 2-year futures contracts and long 1-year futures contracts
- C.Short 1-year futures contracts and long the underlying asset funded by borrowing for 1 year at 3% per year
- D.Short 2-year futures contracts and long the underlying asset funded by borrowing for 2 years at 3% per year
13
Mike is a hedge fund manager in Gold Investment. He invested in some structured products issued by Star Bank. Due to the Covid-19, the structured product was unfortunately downgraded from BBB- to BB+ by S&P in 2020. The price of the product plunged 10% due to the downgrade. Recently, S&P gave positive reviews and the structured product is hopeful to be upgraded. Mike gave his point of view about the investment and rating agencies. Which of the following is not accurate?
- A.The product will rise by 10% at least once the structured product\u2019s rating is raised back to BBB-.
- B.Mike is still a little uneasy, as the CDS for the structured product is becoming more expensive, indicating the negative outlook of the credit rating.
- C.Rating of the structured product depends almost entirely on a model. If the probability that the structured product would give a loss decreases, the ratings of structured products could be increased.
- D.After the 2008 crisis period, rating agencies are no longer used by bank supervisors to determine regulatory capital.
14
There are four types of risk strategies, namely risk avoid, risk retain, risk mitigate and risk transfer, which of the following is not a risk mitigate technique on credit risk?
- A.Looking at the difference between the asset and liability values for each counterparty and having in place documentation saying that these exposures can be netted against each other.
- B.Collateral can be used to offset credit losses in the event of default.
- C.Buy-and-hold business model adopted by banks.
- D.Reassignment of credit exposure to another party in the event of some predefined trigger (e.g., a rating downgrade).
15
The Chief Executive Officer and Chief Risk Officer of a national bank is discussing the implementation of the new round of stress testing required by the regulatory rules. Which of the following statements is correct regarding the key elements of effective governance over stress testing?
- A.Senior management has ultimate oversight responsibility for the institution\u2019s stress-testing activities and set the \u201ctone at the top\u201d.
- B.Internal audit should follow the advices from middle management to provide evaluation of the ongoing performance, integrity and reliability of stress-testing activities to ensure that stress-testing activities are being conducted in a sound manner.
- C.Stress-testing should not only be applied at various levels (business line, portfolio, risk types, individual exposures or instruments and enterprise-wide basis) but also be conducted over various relevant time horizons.
- D.The scenarios in stress-testing should consider the impact of both firm-specific and systemic stress events and circumstances. In particularly, the scenarios should focus only on historical experience but not hypothetical occurrences as the latter are too subjective to be used.
16
After decades of efforts, GOGO Bank finally enters tier-1 banks within the region. But recent 2 risk events alert the bank to improve its risk management. The heads of the bank gather at a meeting to try guidelines for risk management. Which opinion from CRO is right?
- A.As head of the risk and supporter of ERM, I need to get more resources to build integrated risk dept to handle all relevant risks. But I know resources are limited and should be allocated among various dept, I am happy to talk to each CXO to delegate my part of risk responsibility to you.
- B.Risk culture should be engrained within the staff team, but not for senior executives since leaders have enough risk knowledge and skill.
- C.Since the risk culture is invisible at any time, it should be the tone from the top.
- D.Since resources are limited, ERM should be executed in a top-down way.
17
Life insurance companies will face various risks in the process of daily operation. Taking mortality risk as an example, when people's life expectancy decreases due to war or plague, what impact will it have on the profitability of whole life insurance contracts and annuity contracts? Whole life insurance contracts Annuity contracts
- A.Increase Increase
- B.Increase Decrease
- C.Decrease Increase
- D.Decrease Decrease
18
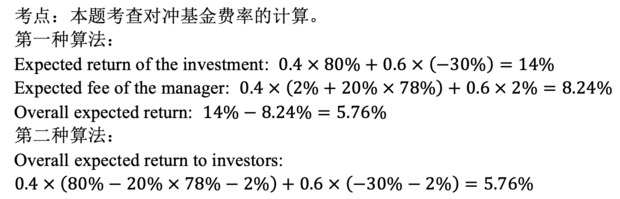
Suppose that a hedge fund manager is presented with an opportunity where there is a 40% probability of a 80% profit and a 60% probability of a 30% loss with the fees earned by the hedge fund manager being 2 plus 20%. What is the overall expected return to investors?
- A.3%
- B.6.68%
- C.5.76%
- D.4%
19
Linda is a risk analyst of Golden Investment Group. She is considering add one security A in her portfolio as the hedging instrument. To predict the fluctuation in the future, she models the performance of security A with a time series model. The ACF and PACF of this model are shown in the following chart. Which of following is most suitable to model the performance of security A?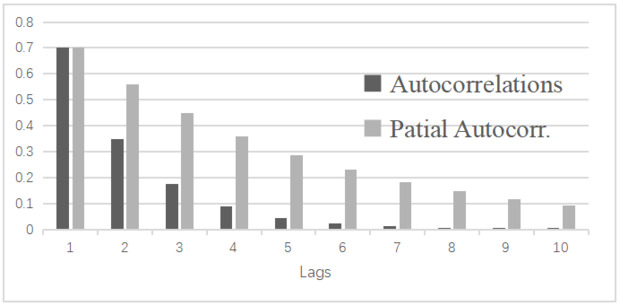
- A.AR (1)
- B.AR (2)
- C.MA (1)
- D.ARMA (1,1)

20
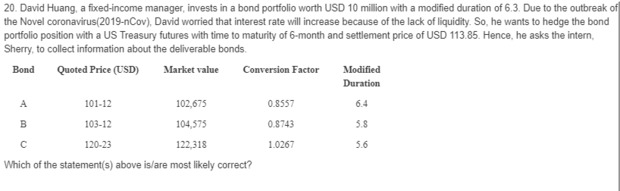
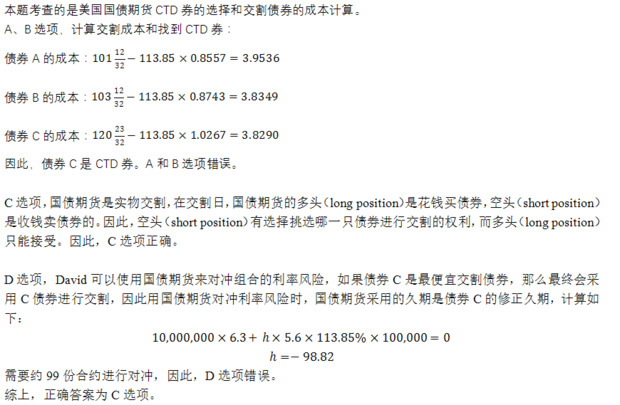
- A.If Bond B is chosen to be delivered, the net cost for the short position to deliver the bond is USD .
- B.he cheapest-to-delivery bond of these three bonds is BondB. The cheapest-to-delivery bond of these three bonds is Bond B.
- C.On the delivery day, short position in US Treasury futures is to deliver the bond to the long position. Hence, Short position has the option to choose which bond to deliver while long position has no choice but to accept.
- D.If Bond C is the cheapest-to-delivery bond, to hedge interest rate risk, David needs to short 90 contracts of the Treasury future.
21
The GOGO Company perceives the credit risk of a certain public retailer is mispriced by the market. GOGO is considering buying or selling a credit default swap (CDS) to speculate on this view concerning the retailer's credit profile. In comparison to buying or shorting the retailer's cash bond, GOGO has already identified advantage to the CDS: it has better liquidity. Which of the following is a disadvantage of the CDS?
- A.The CDS will introduce a new counterparty risk and legal risk to GOGO.
- B.The CDS will introduce basis risk because GOGO will need to also purchase the retailer's bond( ) that are referenced by the CDS.
- C.Although the CDS is a good vehicle for expressing GOGO's view on the retailer's default risk, it will not adjust for mere credit deterioration.
- D.Unlike credit ratings which are frequently updated, GOGO will need to wait until it sells the CDS to obtain price discovery concerning a change in the retailer's credit risk.
22
Michal is a new investment manager of C&D InvestmentBank. On his first day at work, he is informed by the Personnel Department that he will get bonus only when his performance significantly excesses the average performance of the peer group. At the end of the year, the Personnel Department builds a linear regression model of Michal’s monthly excess returns (Ri) against the average excess returns of the peer group(ri) and gets the following result: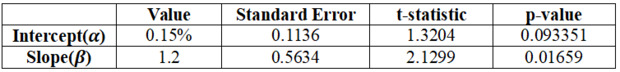 Based on the information, which of the following statements is mostlikely incorrect?
- A.The sensitivity of Michal’s excess returns as regard to the peer group is 1.2.
- B.If the average excess return of the peer group is 10%, the average excess return of Michal is12.15%.
- C.The intercept stands for the extent to which Michal uses greater or less amount of leverage compared to the peer group.
- D.If the size of test is set at 5%, Michal can’t get his bonus this year.

23
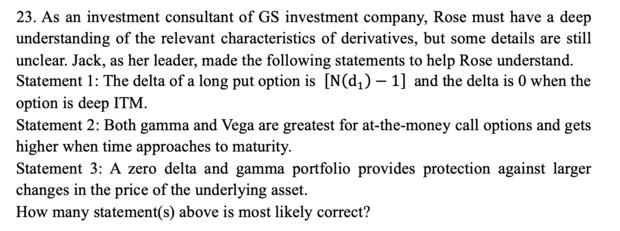
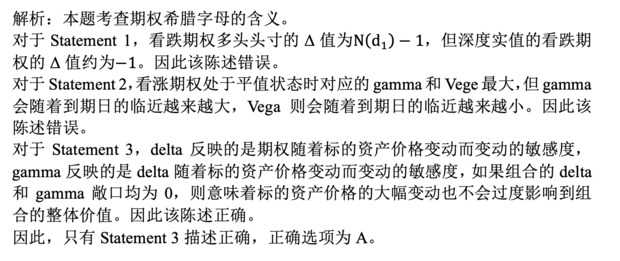
- A.1
- B.2
- C.3
- D.None
24
The board of directors at a large bank is considering creating a risk management committee and a CRO position. Which of the following is not an appropriate description of the risk management committee and CRO position?
- A.A board risk management committee is responsible for setting the firm\u2019s risk appetite and approving the firm\u2019s risk appetite on an annual basis.
- B.CRO should review the analysis of policy guidelines, methodologies, and risk management infrastructure.
- C.CRO is usually a member of the risk committee and is responsible for the design of the firm\u2019s risk management program.
- D.A board risk management committee is responsible for independently reviewing the governance of all material risks.
25
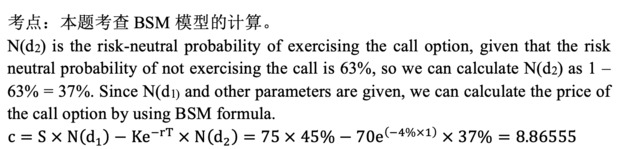
Consider a 1-year European call option with an exercise price of EUR 70. The price of the underlying non-dividend-paying stock is EUR 75 and the annual risk-free rate is 4%. The following estimates have been made:Black-Scholes-Merton model N(d1) = 45%Risk-neutral probability of not exercising the call option at maturity = 63%Which of the following is closest to the price if the call option?
- A.EUR 8.87
- B.EUR 9.89
- C.EUR 10.75
- D.EUR 12.32
26
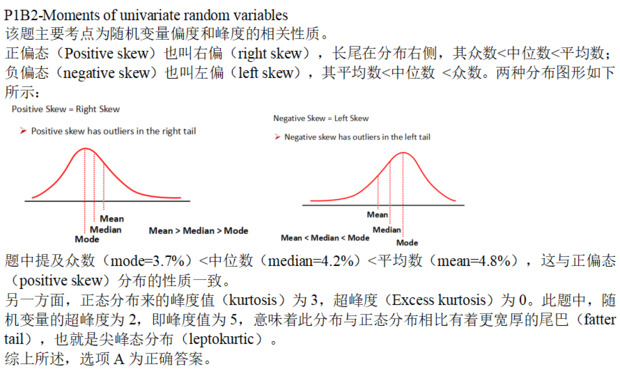
Rachel Xu, FRM, is concerned with the skewness and the kurtosis of a distribution of returns over a period of time for a company she is examining. She does some calculations and finds that the median return is 4.2% , the mean return is 4.8%, and the mode return is 3.7%. She also finds that the measure of excess kurtosis is 2. Based on this information, the correct characterization of the distribution of returns over time is: Skewness Kurtosis
- A.Positive Leptokurtic
- B.Positive Platykurtic
- C.Negative Platykurtic
- D.Negative Leptokurtic
27
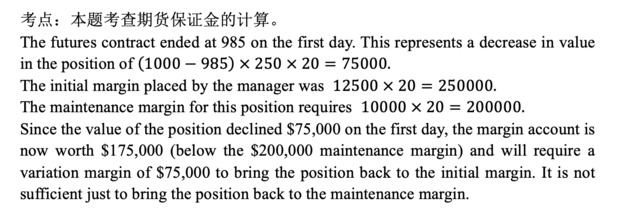
To equitize the cash portion of assets under management, a portfolio manager enters into a long futures position on a stock index with a multiplier of 250. The cash position is $5,000,000, which at the current futures value of 1,000 requires the manager to be long 20 contracts. If the current initial margin is $12,500 per contract, and the current maintenance margin is $10,000 per contract, the variation margin the portfolio manager needs to advance if the futures contract value falls to 985 at the end of the first day of the position is closest to:
- A.$25,000.
- B.$30,000.
- C.$50,000.
- D.$75,000.
28
Joshua Li, an equity analyst, develops a regression model to attribute returns on an equity fund to a risk factor. The regression results are shown as follows: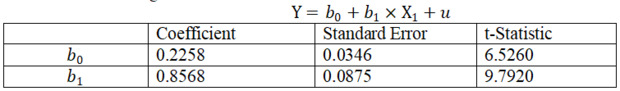 Appendix:Partial Student’s t-distribution (one-tailed probabilities)
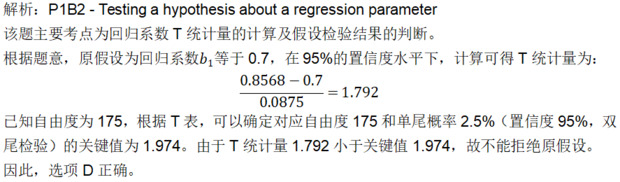
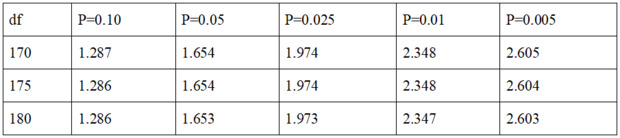 The degreeoffreedomis 175, and Joshua wants to test the null hypothesis that the coefficient of slope is 0.7 at a 95% confidence interval. According to the regression result and t-distribution above, Joshua would:
Appendix:Partial Student’s t-distribution (one-tailed probabilities)The degreeoffreedomis 175, and Joshua wants to test the null hypothesis that the coefficient of slope is 0.7 at a 95% confidence interval. According to the regression result and t-distribution above, Joshua would:- A.Reject the null hypothesis because the t-statistic is greater than 1.645
- B.Fail to reject the null hypothesis because the t-statistic is less than 1.654
- C.Reject the null hypothesis because the t-statistic is greater than 1.974
- D.Fail to reject the null hypothesis because the t-statistic is less than 1.974
29
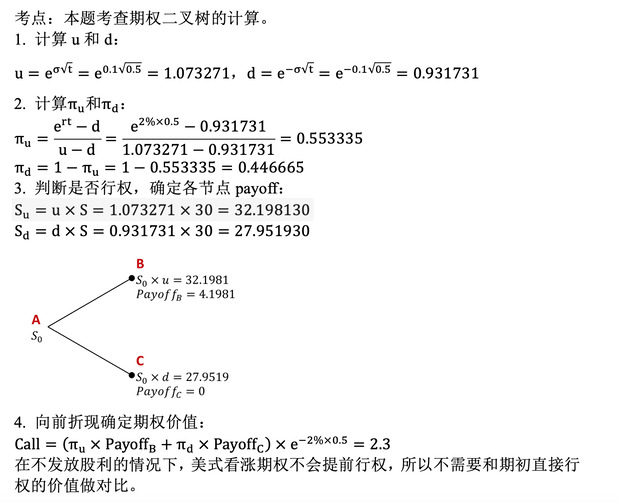
George just finished the course of Derivatives, and he plans to value a half-year American call option with the exercise price at $28, based on one-step binomial model. The underlying asset is Stock A, which is currently priced at $30, and the annual volatility of its return is 10% without dividends. Assume the continuous compounded risk-free rate is 2%. What is the value of this call option?
- A.2.3
- B.3.4
- C.4.1
- D.2.0
30
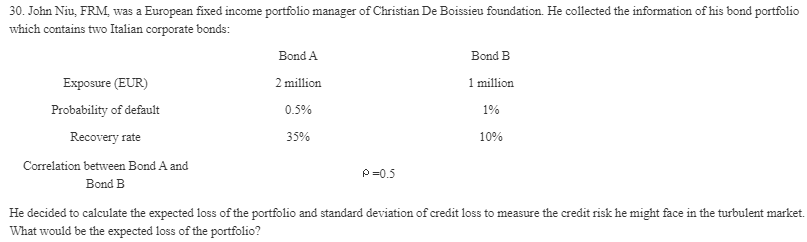
- A.EUR 4,500
- B.EUR 15,500
- C.EUR 764,000
- D.EUR 2,126,000
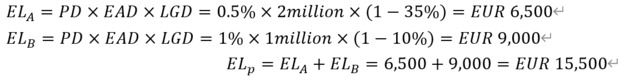
31
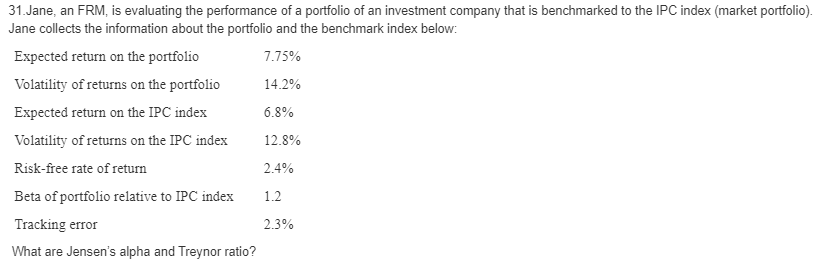
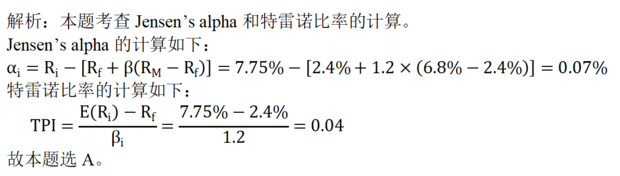
- A.0.07%; 0.04
- B.0.08%; 0.37
- C.0.06%; 0.41
- D.0.07%; 0.37
32
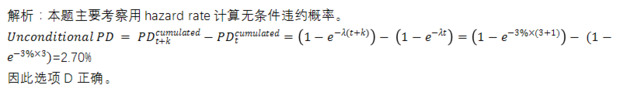
Lucy Yang, a bond trader of Alpha Fund, is estimating the default risk of a bond - Haihua 19 rated with A+. Suppose that the hazard rate of the bond is 3% per year. What is closest to the unconditional probability of a default occurring during the fourth year?
- A.3.59%
- B.3.25%
- C.3.10%
- D.2.70%
33
When firms deal with business overseas, they are exposure to foreign exchange risk. Assume Autocrat is a multi-national operated company with headquarter based in Greenwich, Connecticut. The London office will receive 8 million euros and paid 10 million pounds on Dec 1st, 2020. At the end of year 2020, the company need to prepare consolidated financial statements which include the international trade. Which risk will the company encounter mainly when preparing financial statements?
- A.Transaction risk
- B.Market risk
- C.Translation risk
- D.Economic risk
34
Happy, a bond trader in Blue-blue asset management company, is analyzing the sovereign debt. Which of the following statements is most likely accurate about the sovereign debt?
- A.Greece and other members of the European Union use the euro as their domestic currency and they have the right to print euros to pay for their debts.
- B.Rating agencies provide both local currency ratings and foreign currency ratings, and the local currency rating is the same as the foreign currency rating.
- C.Both Credit spread from credit default swaps and credit rating can provide investors the information on the ability of a country to repay its debt. But credit rating is more granular than credit spread.
- D.Credit default swaps are like insurance contracts that protection sellers provide a payoff to the protection buyers if the reference sovereign issuer defaults within a certain period.
35
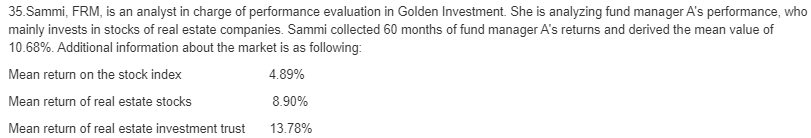
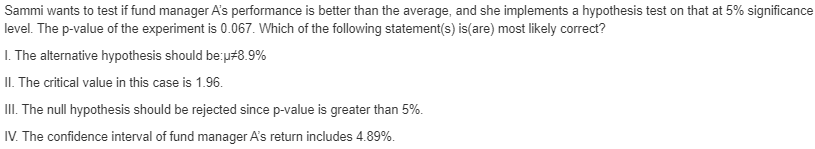
- A.I, and IV
- B.I, II and III
- C.I, III and IV
- D.None of above
36
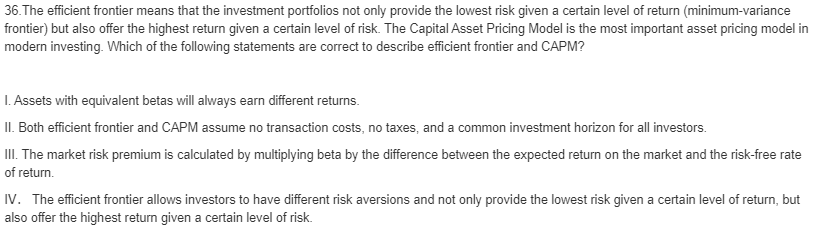
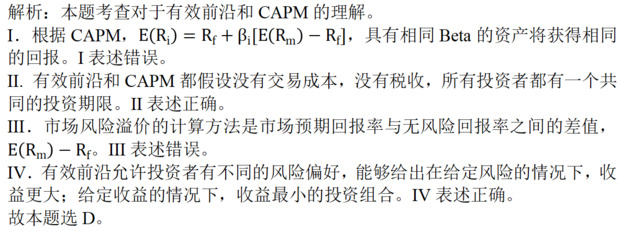
- A.I & II
- B.I & III
- C.III & IV
- D.II & IV
37
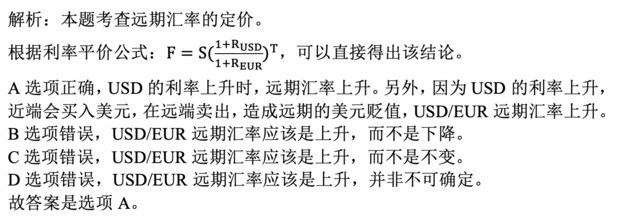
A trader was asked to determine the no-arbitrage 3-year forward exchange rate between the US dollar and the EUR. She observed that the current spot exchange rate between the US dollar and the EUR is USD 1.30 per EUR. She also checked with the chief economist of the bank and found that in the US the 3-year real risk-free interest rate is 1.00% and the expected inflation rate is 2.00%, while in the euro-zone, the 3-year real risk-free interest rate is 1.25% and the expected inflation rate is 2.50%. Affected by the domestic economy, the expected inflation rate of the United States has risen to 2.3%. What impact does this have on the forward exchange rate of the US dollar against the euro?
- A.The forward exchange rate will rise.
- B.The forward exchange rate will fall.
- C.The forward exchange rate will be unchanged.
- D.The change of forward exchange rate is uncertain.
38
Wang, FRM, an equity analyst from Golden Portfolio is concerned about making different types of errors when conducting a hypothesis testing. His supervisor, Leo, convinces him to lower the confidence level of the test. Which of the following statements is most likely correct when only the confidence level of the test is decreased with other factors being held constant?
- A.The likelihood of rejecting the null hypothesis when it is true increases.
- B.The likelihood of making a type I error decreases.
- C.The power of test decreases.
- D.The likelihood of making a type II error increases.
39
Amy Chen, FRM, an asset manager, is running multiple linear regression between asset returns and risk factors. She has done both t-tests and F-test. The results of t‐tests indicate that none of the individual coefficients is significantly different from zero, while the result of F‐test indicates overall significance. Which of the following best describes the problem of her regression analysis and the corresponding impact? Problem Impact
- A.Multicollinearity makes OLS estimators biased
- B.Multicollinearity does not affect the unbiasedness of OLS estimators
- C.Omitted Variable Bias makes OLS estimators biased
- D.Omitted Variable Bias does not affect the unbiasedness of OLS estimators
40
Duration measures the sensitivity of a bond’s price to a change of interest rates, while convexity demonstrates how the duration of a bond changes as the interest rate changes. Despite some limitations, duration and convexity are commonly used in the risk management. The following statements are about duration and convexity. Statement I. Macaulay duration of a zero-coupon bond is equal to the bond’s time to maturity.Statement II. Modified duration provides a good approximation of the percentage price change for a callable bond given a change in yield.Statement III. When considering the effect of a large non-parallel shift in the interest rate term structure, convexity should be used in addition to duration.Statement IV. Macaulay duration and modified duration provide a linear estimate of the percentage price change for a bond given a change in yield ( Δ%P≈-Dur×Δy). Macaulay duration applies in the situation where y is measured with continuous compounding, and modified duration applies here when y is measured with discrete compounding. Which of statements above is (are) incorrect?
- A.I, II
- B.I, III
- C.II, III
- D.III, IV
41
Financial data often exibitshigh dependences, and risk managers need to pay special attention to these dependences. Nowadays, the focus is on three kinds of measures of dependencies: Pearson correlation, Spearman’s correlation, and Kendal’s τ. A risk manager of a major hedge fund, is assigned to test new intern applicants regarding this topic, and he has written the following four statements:Statement I: Spearman’s correlation and Kendall’s τ both measure non-linear dependences and both are scale invariant.Statement II: Spearman’s correlation increases as ρ increases, while Kendall’s τmay not have this characteristic.Statement III: Kendall’s τalways produces the same sign as the sample correlation and often produces smaller absolute values compared with the linear correlation.Statement IV: Although Spearman’s correlation and Pearson’s correlation both lie between -1 and 1, they can have different results when measuring dependences between independent variables.Which of these statement( ) onthe quiz is(are) most likely correct?
- A.Statement I, III
- B.Statement II, IV
- C.Statement II, III, IV
- D.Statement I, III, IV
42
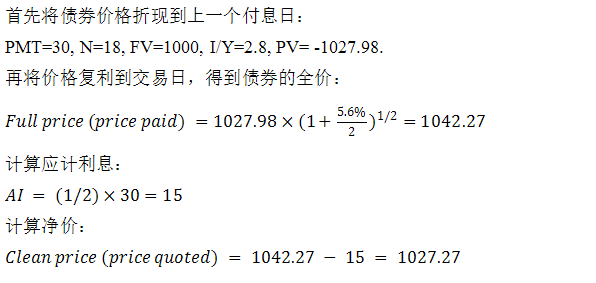
Consider a 6% semi-annual coupon bond, issued by Star Company, with par value of 1000 and required yield of 5.6%. The bond will mature on 15 February 2028 and coupon are made on 15 February and 15 August of each year. The bond is to be priced for settlement on 15 May 2019, which is in the middle of two coupon date. What should be the price quoted?
- A.1047.27
- B.1027.27
- C.1015.46
- D.1000.46
43
Jenny Zhang, FRM, is considering developing a new risk measure indicator, called Jenny-score. Her leader Steven is evaluating the coherence of this indicator. Suppose there is a portfolio A with a size of 100,000 dollars and portfolio B with a size of 100,000 dollars. The Jenny-score of portfolios A and B is 370 and 450, respectively. His evaluation includes the following four parts. Which of the following statement is incorrect?
- A.Suppose the portfolio A\u2019s size is 200,000 million dollars rather than 100,000 million dollars, the Jenny-score would be 820. This indicates Jenny-score violates the homogeneity.
- B.Merge portfolio A and B to get portfolio
- C.Portfolio C\u2019s Jenny-score is 900. This indicates Jenny-score satisfies the subadditivity.C. Portfolio C\u2019s Jenny-score is 900. This indicates Jenny-score satisfies the subadditivity. C. In all circumstances, the portfolio B produces a worse result. This indicates Jenny-score satisfies the monotonicity.
- D.If an amount of cash K is added to portfolio A, A\u2019s Jenny-score will be 370-K. This indicates Jenny-score satisfies the translation invariance.
44
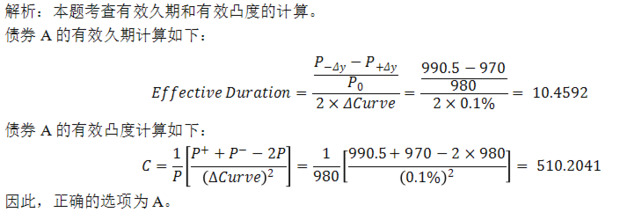
Winston is a deputy manager of a mutual fund and is assigned to manage a portfolio. The portfolio consists of only one bond, Bond A. The original price of Bond A is $980. If all the interest rates rise 10 bps, the price of Bond A will be $970. And if all the interest rates decrease 10 bps, the price of Bond A will be $990.5. What is the effective duration and the effective convexity of Bond A?
- A.10.5 510.2
- B.8.5 500.5
- C.12.7 490.8
- D.15.5 550.8
45
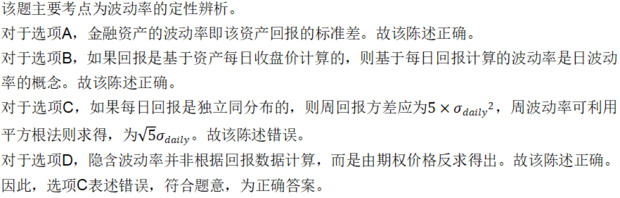
The volatility of financial assets is a common measure to address risk. Among the following statements regarding volatility, which is least likely correct?
- A.The volatility of a financial asset is usually measured by the standard deviation of its returns.
- B.If returns are computed using daily closing prices, the corresponding measure is daily volatility.
- C.If the daily returns are independently, identically distributed, the weekly variance rate can be calculated as.
- D.Implied volatility is not based on daily returns but option prices.
46
Tom is attending the induction training of the GS investment company. Many employees in this training are talking about options. Which of the following statements about options is most likely correct?
- A.If the relevant conditions are consistent, the order of option premium from the most expensive to the cheapest is American option, European option, and Asian option.
- B.Buying zero-cost products means no costs.
- C.For an ITM digital option, the long position will receive a specific asset at maturity.
- D.Lookback option also called the Russian option, which provides a payoff dependent on an arithmetic average of the underlying asset price during the life of the option.
47
Arguably the U.S. savings and loan (S&L) crisis in the 1980s had multiple causes, but among the following which is the BEST summary explanation of the S&L crisis?
- A.S&Ls engaged in a practice called "riding the yield curve" to make money, by maintaining positive spreads between interest rates earned on longer-term assets and interest paid on shorter-term liabilities.
- B.A dramatic increase in short-term interest rates resulted in the negative interest rate spread due to their asset-liability mismatch.
- C.A dramatic decrease in short-term interest rates wiped out banks' interest rate spread due to their asset-liability mismatch.
- D.Rising inflation in the late 1970s promoted the Fed to implement a restrictive monetary policy, which can help them solve the interest rate crisis.
48
In the cases of Continental Illinois and Northern Rock, we can learn that asset liability management is important and there is a trade-off between funding liquidity risk and interest rate risk. If the duration of debts is shorter than that of loans, the bank will be exposed to ( ) interest rate risk and ( )funding liquidity risk.
- A.lower, higher
- B.lower, lower
- C.higher, higher
- D.higher, lower
49
There are two European put options trading at market, the first one has 3-month to expiration, while the second has 4-month. Both of them have the same strike price of USD 20, and the underlying stock is trading at USD 5. The underlying company has just announced a cash dividend distribution plan which will happen 3-month and half from now. Which of the following statements is most likely accurate about the value of two put options? (TIPS: Gap of value is defined as Value of short-term option minus Value of long-term option, and more negative value means narrower gap)
- A.The short-term option has lower value, and the dividend plan will narrow down the gap of value.
- B.The short-term option has higher value, and the dividend plan will narrow down the gap of value.
- C.The short-term option has lower value, and the dividend plan will strengthen the gap of value.
- D.The short-term option has higher value, and the dividend plan will strengthen the gap of value.
50
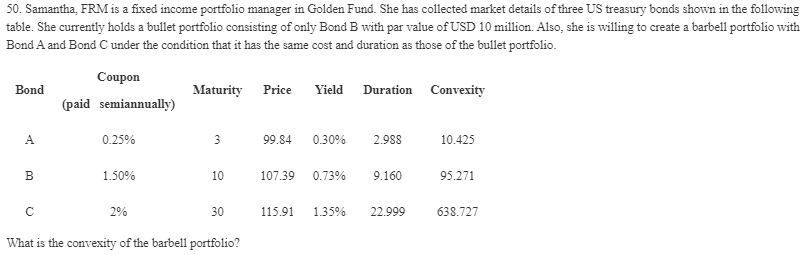
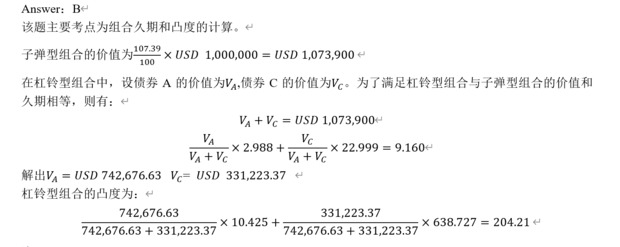
- A.102.38
- B.204.21
- C.333.46
- D.488.32
51
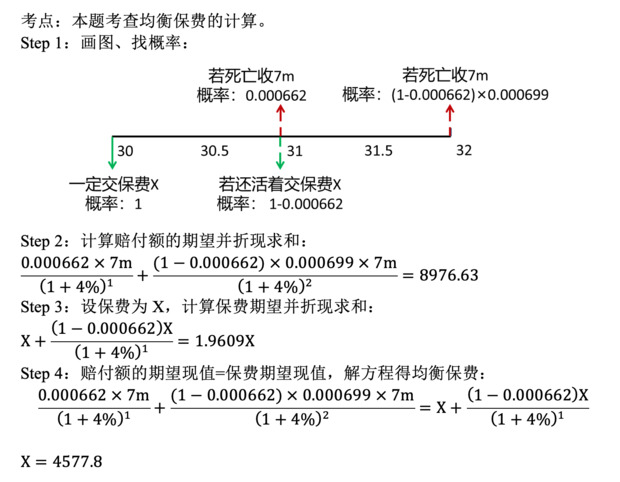
Alice Yang, CFA, the Head of Accounting Module of CFA & FRM Research Center of Golden Finance, aged 30. Now she wants to purchase a two-year term life insurance after an internal seminar from Dr. Xu. If she wants to be paid $7,000,000 when the insurance contract works, and the relevant interest rate for insurance contracts is 4% per annual and all premiums are paid annually at the beginning of the year. Assume that payouts occur at the end of the year. Using the mortality rates table, which of the following amounts is closest to the insurance company’s breakeven premium for a two-year term? (with annual compounding)Information: probability of death in 1 year for 30-aged and 31-aged female is 0.000662 and 0.000699.
- A.4,677
- B.4,578
- C.4,500
- D.4,725
52
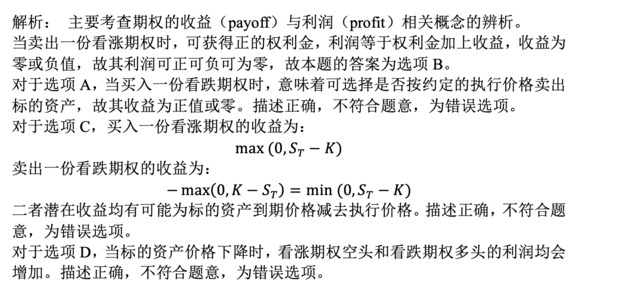
A stock option is a derivative whose value is dependent on the price of a stock. Similar to the valuation analysis of the underlying stock, it is also meaningful to determine the payoff and profit of the option. Which of the following statements regarding the payoff and profit of options is most likely incorrect?
- A.When you buy a put option, the payoff is positive or zero.
- B.When you write a call option, the profit is negative or zero.
- C.The potential payoff of purchasing a call option and writing a put option may both be price at maturity minus strike price.
- D.Both the profit of selling a call option and buying a put option will increase if the underlying assets price decrease.
53
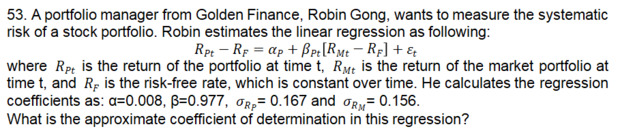
- A.0.913
- B.0.833
- C.0.977
- D.0.955
54
There are several types of insurance companies: life insurance, nonlife insurance and health insurance. Jam, FRM,have several years of working experience in insurance market, he comes to the following statements:Statement 1: Life insurance provides payments to policyholder’s beneficiaries that depend on when policyholder dies.Statement 2: Based on surplus premium choice, life insurance contracts can be divided into term life insurance and whole life insurance.Which of the statement( ) above is/are most likely correct?
- A.Only statement 1
- B.Only statement 2
- C.Both statements
- D.Neither of two statements
55
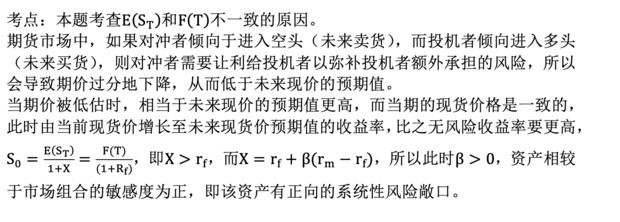
Suppose that speculators tend to take long positions on one commodity, while hedgers entering into short positions. What is the most accurate estimation about the commodity futures price and its systematic risk exposure according to CAPM?
- A.Futures price is overestimated compared with the expected future spot price, and the underlying has positive systematic risk exposure.
- B.Futures price is overestimated compared with the expected future spot price, and the underlying has negative systematic risk exposure.
- C.Futures price is underestimated compared with the expected future spot price, and the underlying has positive systematic risk exposure.
- D.Futures price is underestimated compared with the expected future spot price, and the underlying has negative systematic risk exposure.
56
A firm named XYZ. Ltd, faces exposure to interest rate volatilities, and the CRO of XYZ Ltd. is considering using a complicated instrument to hedge the exposure, however, the board is worried that the instruments might increase the firm’s financial exposure, which of the following statements cannot help convincing the board to adopt hedging strategies?
- A.Hedging is often intended to reduce the chance of financial distress and costs of capital.
- B.Hedging can stabilize earnings and enhance the ability to finance growth.
- C.Hedging, as a risk reduction activity, may offer synergies with the operations of the firm.
- D.Risk management requires specialized skills, knowledge, infrastructure, and data acquisition and processing effort.
57
Lucy, FRM, is evaluating the default probability of the two sovereign bonds which are allocated in her portfolio. The information is as the following table: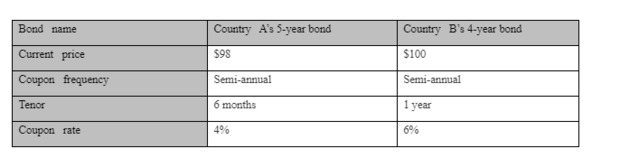 Suppose that the T-bill yields for the 6 months and 1 year are 3% and 3.5%, respectively. There is no available rating information for the two bonds. By computing the yield spread, which of the following conclusions will Lucy draw?
- A.Market implies that Country A’s bond has more credit risk than Country B’s bond.
- B.Market implies that Country B’s bond has more credit risk than Country A’s bond.
- C.Market implies that the two bonds from Country A and B have equal credit risks.
- D.The information is not enough to compare the credit risk for the two bonds.
58
Markus Freitag,a fresh risk analyst, is pricing a zero-coupon bond. The current spot curve is upward sloping. Markus thought he was using aspot rate to value the bond by discounting the future cash flow. But he used a forward rate at the same maturity by mistake, instead of a spot rate. The result obtained by Markus will be?
- A.Larger than the true value of the zero-coupon bond.
- B.Smaller than the true value of the zero-coupon bond.
- C.Identical to the true value of the zero-coupon bond.
- D.Not easy to be compared with the true value of the zero-coupon bond, as lacking sufficient information.
59
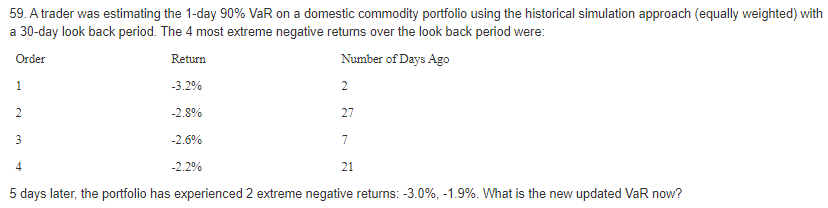
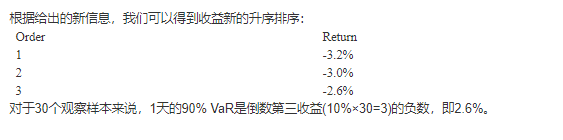
- A.3.0%
- B.2.6%
- C.2.8%
- D.3.2%
60
While idiosyncratic risk can theoretically be eliminated through diversification, the same is not true for systematic risk. However, factor betas can be used to construct a hedging strategy to eliminate systematic risk. Which of the following statement is NOT true about factor betas?
- A.Each factor can be regarded as fundamental security and can therefore be used to hedge the same factor that is reflected in a given security.
- B.If the goal is to hedge out all the factor risks and create a zero-beta portfolio, then we can take the opposite positions in each of the factors so that the combined portfolio contains no factor exposures.
- C.The selection of the appropriate systematic factors depends on judgment and there is no single perfect set of factors for all investors.
- D.Once the factor model is correctly determined, the hedging strategy will achieve the desired results.
61
Jennifer is a candidate of Master of Risk Management in Golden Future University. She is reviewing her notes to prepare the final exam. When it comes to the part of VaR estimation, she is not confident whether her notes are correct. There are several statements in her notes:Statement I: The historical simulation is a full revaluation method, while the Monte Carlo simulation is not a full revaluation method.Statement II: Delta normal approach is comprised of delta approximation (delta-only approximation) and delta-gamma approximation. If the delta approximation and the delta-gamma approximation are applied simultaneously to calculate VaR of a portfolio, the VaR calculated from delta approximation tends to be lower than that from delta-gamma approximation.Statement III: The historical simulation is quite flexible. It could generate correlated scenarios and models the correlations among different risk factors based on a statistical distribution.Statement IV: When calculating the portfolio’s VaR, the historical simulation and the delta normal approach are both assuming normality of value change of the portfolio.How many statements are correct?
- A.0
- B.1
- C.2
- D.4
62

- A.5%
- B.6%
- C.7%
- D.8%
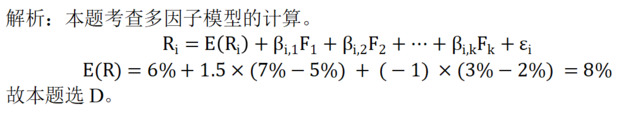
63
Gordon is an senior derivative trader in vista security, he is currently researching basis risk management skills. Which of the following statement below about basis risk is incorrect?
- A.Basis risk is the uncertainty associated with the basis at the time a hedge is closed.
- B.Choices left to the seller about the physical settlement of the futures contract in terms of grade of the commodity, location, chemical attributes may result in basis risk.
- C.One of the reasons which cause basis risk is that the asset being hedged and the underlying asset of futures contract is not the same.
- D.Long-hedge position benefits from strengthening of basis.
64
Andy, a credit analyst in Blue-blue bank, is measuring the credit capital. The regulator and the board of the bank have different requirements in determining the credit capital amount in different models. Which of the following statements is most likely accurate about the capital for the bank’s risk?
- A.CreditMetrics is the model bank often use to determine regulatory capital because it considers the impact of rating changes.
- B.Both regulatory capital and economic capital separate capital calculations for credit risk, market risk, and operational risk. One important difference between regulatory capital and economic capital is that total regulator capital for all risks considers the correlations between each other.
- C.A Monte Carlo simulation is carried out to model how ratings change during the year in the Vasicek model which use to determine regulatory capital in Basel II.
- D.The Basel Committee sets the percentile to be 99.9% for regulatory credit capital in the internal ratings-based approach in Basel II.
65
Bob Hatfield has his money management firm with two clients. The accounts of the two clients are equal in value. It is Hatfield's opinion that interest rates will fall soon. Based on this, Hatfield begins increasing the bond allocation of each portfolio. To comply with Best Practices in the GARP Code of Conduct, the analyst needs to:
- A.inform the clients of the change and tell them it is based upon an opinion and not a fact.
- B.make sure that the change is identical for both clients.
- C.file a report with the SEC of the new portfolio allocation.
- D.perform all these functions.
66
A foreign trade company went to the bank to carry out settlement and sale of foreign exchange. The company had 1 million US dollars to be converted into euros after three months. The EURUSD spot prices are quoted as bid 1.1744 and ask 1.1746, while EURUSD three-month forward are quoted as bid 1.1824 and ask 1.1827. Then the company came to the following statements:Statement 1: To convert the US dollars to euros, the company should use the forward rate 1.1827.Statement 2: Today, if an another company wants to exchange euros for US dollars, the bank would use the spot rate 1.1744.Which of the statement( ) above is/are most likely correct?
- A.Only statement 1
- B.Only statement 2
- C.Both statements
- D.Neither of two statements
67
A bank’s Chief Risk Officer is considering persuading the government’s regulatory officials that it is appropriate for the bank to adopt Advanced Measurement Approach (AMA) for the calculation of the bank’s capital requirement for the operational risk. Which of the following statements about AMA is incorrect?
- A.The AMA would need to generate the operational risk loss distribution which requires the modeling of loss frequency using Poisson Distribution and loss severity using Uniform Distribution.
- B.After generating the operational loss distribution by AMA, the operational risk capital requirement is calculated by the difference of 99.9% one-year VaR and the expected loss.
- C.One concern for the AMA is the insufficient internal data for the modeling of the loss distribution function so that utilizing external data would serve as a solution for the concern.
- D.When obtaining external data, one would need to make some adjustment before using it in the AMA. For example, for external operational loss data from a much larger bank, one would need to scale it down relatively.
68
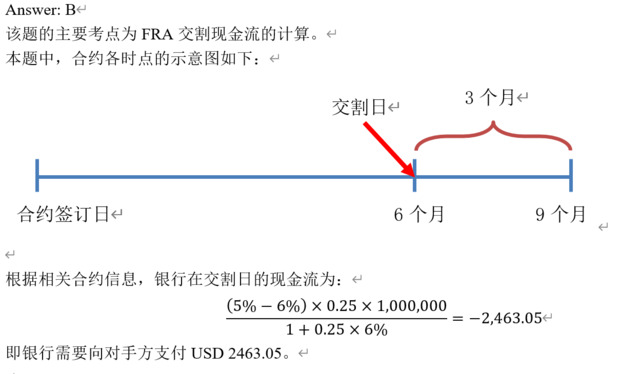
A local bank has entered into an FRA (forward rate agreement) contract to lock the interest rate risk of making a loan in the future. The contract specified a fixed rate of 5% on a principal of USD 1 million for 3-month period starting in 6 months. LIBOR is the reference rate in the contract, and the bank takes the short position in the contract. After 6 months, the 3-months LIBOR happens to be 6%, what is the pay-off on the settlement date?
- A.2,463.05
- B.-2,463.05
- C.2,500
- D.-2,500
69
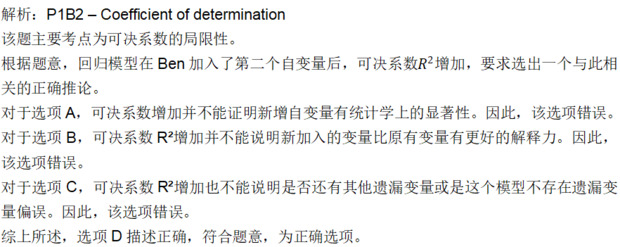
Ben Niu, FRM, a risk analyst, is working on creating a regression model to forecast defaults of a portfolio of residential mortgages. After running a regression with a single regressor, Ben gets a R²of 0.2. He decides to add a second regressor into the model and the R²for the model increases. What can Ben conclude most correctly with the increasing R²:
- A.The new regressor is a statistically significant predictor variable.
- B.The new regressor is a better cause of the movements in the dependent variables.
- C.There is no omitted variable bias in this model after including the second regressor.
- D.None of above.
70
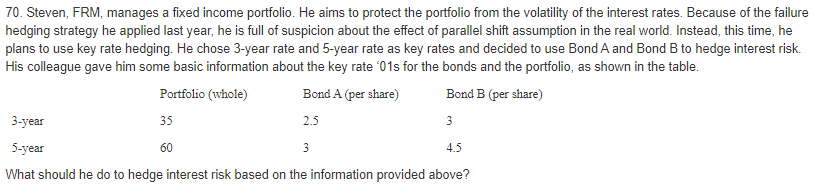
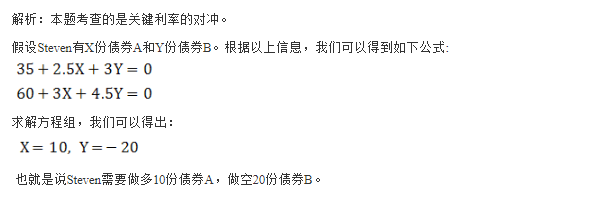
- A.Long 10 shares of Bond A, and short 20 shares of Bond B
- B.Short 10 shares of Bond A, and short 20 shares of Bond B
- C.Short 10 shares of Bond A, and long 20 shares of Bond B
- D.Long 10 shares of Bond A, and long 20 shares of Bond B
71
The supervisor is recently reviewing a regional bank’s risk data aggregation and risk reporting and suggests the bank upgrade its capability to comply with the Basel guidelines. Which of the following is the most important functionality for the bank to achieve?
- A.Enhance the readability of risk reports by using the same metrics for all kinds of risks and making them under the same monitoring frequency.
- B.Develop customized risk data aggregation systems for different departments to fulfill their risk management requirements.
- C.Only those risks that will threaten the survival of the bank should be reported to the board to improve efficiency.
- D.The bank\u2019s risk data aggregation capabilities and risk reporting practices should be subject to strong governance agreements consistent with the principles established by the Basel Committee.
72
Marilyn is the head of trading desk in SuperMe Investment Group. These days, she is not satisfied with the accuracy of the VaR (used as the risk measure for a call option position), which is estimated by the delta-only approach. The monthly 95% VaR of the underlying asset is 10%. The call option is at-the-money, and the gamma is 0.201. What is the monthly VaR of the call option estimated by delta-gamma approach?
- A.10%
- B.5.1%
- C.5%
- D.4.9%
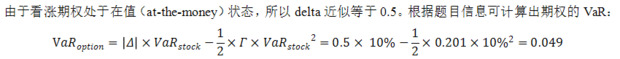
73
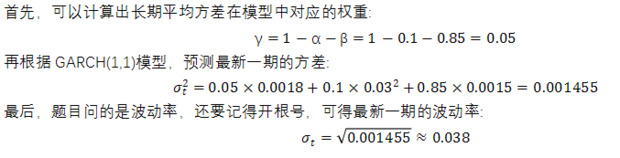
Danny McBride intends to update the volatility of the portfolio. He decides to adopt GARCH(1,1)model to fulfill his purposes. The model he runs is as follow: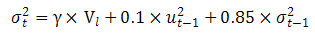 Base on his research, the long-term variance for the portfolio is 0.0018, the return for the previous day is 0.03, and the estimated variance for the previous day is 0.0015. The renewed volatility for the portfolio is closest to:
- A.0.038
- B.0.056
- C.0.0031
- D.0.0154
74
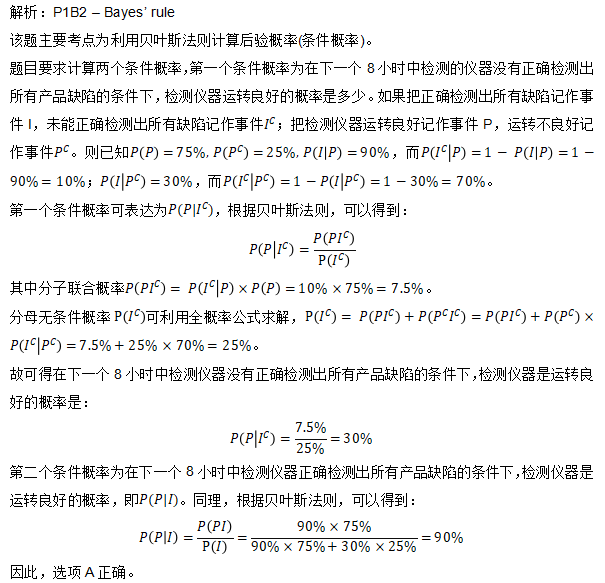
Pineapple, a cell phone manufacturer, is performing routine inspection on adaily basis. Its quality control department has recently received an abnormally huge amount of complaints regarding the unqualified cell phones, so the CEO of Pineapple decides to check the machines doing the inspections as well as the whole inspection process. Based on the historical analysis data, hegets the following results: When the inspection machine performs well, it has a 90% probability of accurately inspecting all deficiencies in the products in an 8-hour time shift; while this probability will drop to 30% if the machine doesn’t perform well. On average, the probability of the inspection machine performing well is 75%. What will be the probability of the machine performing well given that it does not accurately inspect all deficiencies in the following 8-hour time shift, and given that it does accurately inspect all deficiencies in the following 8-hour time shift, respectively?
- A.30%; 90%
- B.7.5%; 67.5%
- C.25%; 75%
- D.17.5%; 7.5%
75
Option is one type of various financial derivatives, it can be used to do some trading strategies, such as single option strategies, spread trading strategies. Here are three statements about the single option strategies.Statement 1: Covered call strategy is structured to long a stock and short a European call option. The potential profit of this strategy is limited and do face the downside risk of the stock.Statement 2: Principal protected notes is structured to long a corporate bond and short a European put option. This strategy can ensure that the investors will not lose their principal on the maturity date.Statement 3: Protective put strategy is structured to long a stock and short a European put option. This strategy could achieve the purpose of yield enhance and protect the downside risk of stock.Which of the statement( ) above is/are most likely correct?
- A.Only statement 1
- B.Only statement 2
- C.Statements 2 and 3
- D.Statements 1 and 2
76
Daisy Tu is a fund manager who focuses her investment on MBS and structured financial sector. In her portfolio, there are agency MBSs, non-agency MBSs, credit-card ABSs and other CDOs. She indicates that although these instruments are all securitization-related products, the risk characteristics vary. Which of the following statements is accurate regarding agency MBS?
- A.CMO is a basic form of agency MBS which directly passes the cash flows from asset pools to the investors.
- B.100PSA is the benchmark for mortgage pass-through securities. 70 PSA means that this MPS is trading at 70% of its par.
- C.If the single monthly mortality of a MPS is 0.4%, the conditional prepayment rate is 4.91%.
- D.Sequential-pay tranching reallocates the prepayment risk to various tranches, leading some tranche retiring earlier.
77
Derivatives markets have attracted many different categories of traders. Those traders can be identified in terms of their activities. An individual that makes profit from bid-ask spread of a given security and add liquidity to facilitate trading is:
- A.a hedger.
- B.a speculator.
- C.an arbitrageur.
- D.a market maker.
78
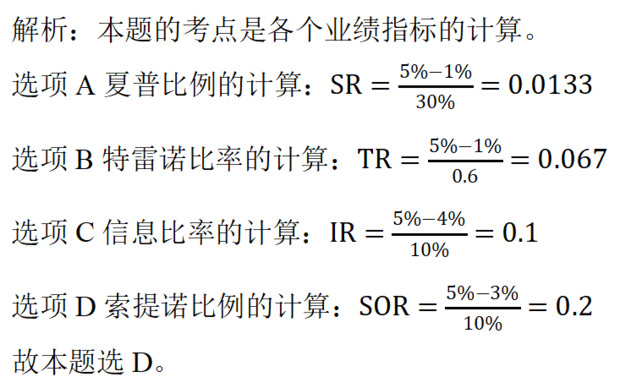
Consider the following results of an ex-post analysis of a portfolio and its benchmark.ŸThe risk-free rate is 1.0% per annum;ŸThe benchmark (market index) had an average return of 4.0% per annum with a volatility of 20.0%;ŸThe portfolio's average return was 5.0% per annum with a volatility of 30.0%;ŸThe portfolio correlation to the benchmark, ρ(p, M), was 0.60;ŸThe portfolio's tracking error was 10.0%;ŸThe portfolio's minimum acceptable return (MAR) was 3.0% per annum and its downside deviation was 10.0%.Assume all values are already annualized. Which of the following measures gives the highest value?
- A.Sharpe ratio
- B.Treynor ratio
- C.Information ratio
- D.Sortino ratio
79
Alice, a credit analyst in Blue-blue bank, learns that the Merton model considers the company’s equity as a call option on the assets of the firm with a strike price equal to the face value of the debt. So, the value of equity can be calculated by the BSM model. Under this model, which of the following can be viewed as the default probability?
- A.N(d1)
- B.1-N(d1)
- C.N(d2)
- D.1-N(d2)
80
Whenstudying referential statistics, Linda and her classmates Yuri are quite confused about several new concepts related to this topic. So, they ask their tutor to give some advice. Their tutor, Mr. Huang, invites some other students to join the discussion and asks them to express their views concerning about properties of estimators. After that, he will correct their wrong understandings. Linda first starts to talk:” I’ve learned that an ideal estimator should possess several properties to be BLUE, which is the acronym for briefness, linearity, unbiasedness and efficiency.” Yuri complements the statement:” the mean estimator is a good example of a BLUE one and has the smallest variance among all the biased and unbiased estimators.” Another student, Jacob, also expresses his idea:” I don’t agree with Yuri’s statement, for an unbiased estimator is always better than a biased one.” Which of the following conclusion is most likely correct?
- A.Yuri is correct while Jacob is incorrect.
- B.Jacob is correct while Yuri is correct.
- C.Linda is correct about an ideal estimator but incorrect about the acronym for BLUE.
- D.Linda is correct while the other two students are incorrect.
81
A portfolio of stock A and options on stock A is currently delta neutral, but has a positive gamma. Which of the following actions will make the portfolio both delta and gamma neutral?
- A.Buy call options on stock A and sell stock A
- B.Sell call options on stock A and sell stock A
- C.Buy put options on stock A and buy stock A
- D.Sell put options on stock A and sell stock A
82
Monte Carlo simulation is a very important practical tool with a wide variety of applications. However, the simulation error is a big concern. Luckily, there are ways to improve the accuracy of simulations. Which of the following is most likely correct?
- A.Although repeating the simulation improves the accuracy of the approximation, this method is rather costly.
- B.The standard error of the estimated expected value could be reduced by assuming that the sample draws are independently, identically distributed(iid).
- C.Antithetic variables can reduce simulation error due to introducing a new variable that has a high correlation with the original variables.
- D.Control variate involves another set of variables that have positive correlations with the iid variables used in the simulation.
83
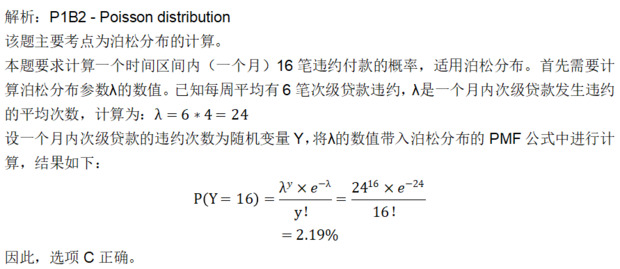
Prior to the 2007-2009 financial crisis, some of the biggest buyers of U.S. subprime securities were European banks.Sachsen Landesbank was one of those buyers. Silver Group sold Credit Default Swaps to Sachsen Landesbank asa protection seller. For each security, Silver Group charged 2% of the principal amount for compensation. When the subprime crisis bursted out in 2007, lots of subprime securities held by Sachsen Landesbank went default. Silver Group had to make payments to Sachsen Landesbank for defaulted securities. Silver Group provided 15800 CDS to Sachsen Landesbank in total, and statistically, 6 subprime securities went default in one week on average. Silver Group measured that they had to pay for less than 16 defaulted securities in one month to continue operating. What was the probability that Silver Group makes exactly 16 payments to Sachsen Landesbank next month?
- A.1.32%
- B.1.44%
- C.2.19%
- D.31.68%
84
Lynn King is the CFO of Montag & Caldwell. Montag & Caldwell plans to issue a 10-year bond to fund its new project. However, the current interest rate is considerably high and Lynn predicts that the interest rate will decrease in the future. Lynn has a friend called Milly Scott who set up the listed company, Legacy Fortune Management. Milly is considering issuing more stocks to raise money. However, the current stock price is quite low, and she feels it is too expensive to issue the stock at the current price. Furthermore, as the founder of the company, she is confident that the stock price will rise in the future. With these considerations, what type of bonds might be choices for Montag & Caldwell and Legacy Fortune Management to raise funds now respectively?
- A.Callable bond; convertible bond
- B.Putable bond; convertible bond
- C.Callable bond; putable bond
- D.Putable bond; callable bond
85
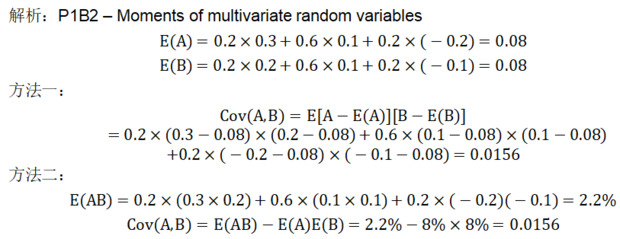
James Warden, an economic analyst from Golden News, has calculated the probabilities of three possible states of the economy next year. James’ colleague Teresa Chen has estimated the possible returns on two stocks, A and B, under each of the three economy states, which are shown in the following table: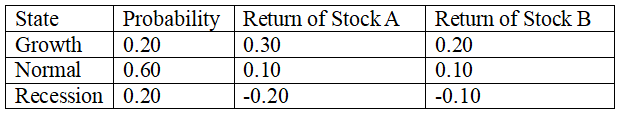 Given that the standard deviation of the estimated returns on stocks A and B are 16.0% and 9.8%, respectively, what is the covariance of the estimated returns on stocks A and B?
- A.-0.0187
- B.-0.0156
- C.0.0156
- D.0.0178
86
Leblanc, FRM, is a quantitative analyst. She is trying to build a model on a set of stationary time series data. Which of the following regarding joint tests of residual autocorrelations is most likely correct?
- A.Jarque-Bera test could be used to conduct joint tests of autocorrelations.
- B.If the null hypothesis is rejected, it indicates that the time series is stationary.
- C.The null hypothesis for the test is that all of the autocorrelations are simultaneously zero.
- D.If the null hypothesis is rejected, it indicates that the time series model is ideal.
87
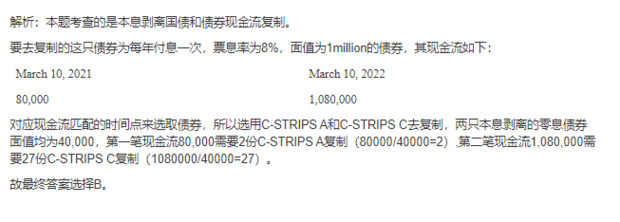
Evelyn, CFA, CAIA, FRM, is an analyst with Beat Market Hedge Fund. She is investigating the arbitrage opportunities of the treasury bond market. After reviewing, she focuses on a treasury bond which matures on March 10, 2022 with 8% annual coupon payments and 1 million face value. Evelyn decides to use STRIPS to replicate the coupon-bearing bond. The STRIPS she can use are as follows: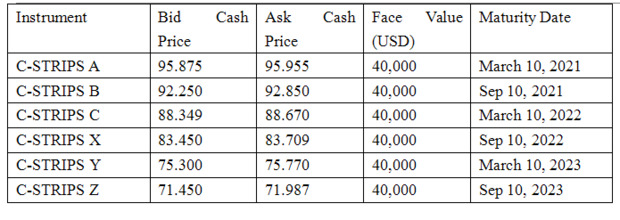 Today is September 10, 2020, how can Evelyn construct the replicating portfolio?
- A.Long 8 C-STRIPS A and long 108 C-STRIPS B
- B.Long 2 C-STRIPS A and long 27 C-STRIPS C
- C.Long 8 C-STRIPS A, long 8 C-STRIPS C and long 108 C-STRIPS Y
- D.long 2 C-STRIPS A and long 27 C-STRIPS B
88
Susan and Mike is talking about the characteristics of exotic options. And they makes the following assertions:Ⅰ. A gap option is a European call or put option where the trigger determining whether there will be a payoff is different from the strike price used to calculate the payoff.Ⅱ. A floating lookback put is an option that pays off the amount by which the maximum asset price during the option's life exceeds the final asset price.Ⅲ. As the correlation between the returns decreases, a basket option becomes more valuable because large movements in the value of the portfolio become more likely.Which of the assertions is(are) correct?
- A.Only \u2160.
- B.Both \u2160 and \u2161.
- C.Both \u2161 and \u2162.
- D.All of them.
89
One of the investment banking’s activity is underwriting business, which helps companies raising capital in the form of debt, equity, or more advanced securities. Which of the following statements regarding underwriting is incorrect?
- A.When the new securities are sold with some specific life insurance companies and pension plans is the form of private placement of underwriting.
- B.If a public offering is on a best efforts basis, the investment bank does as well as it can to sell the securities for a higher price.
- C.The firm commitment arrangement is more risker for the issuing company than a best efforts arrangement.
- D.Not only clients of the underwriting investment bank, but also other investors can participate an IPO through Dutch auction.
90
In the 2008 Financial crisis, firms that were selling their credit exposures found themselves retaining a growing pipeline of credit risk. Furthermore, they did not adequately measure and manage the risks that would materialize if assets could not be sold. Some levered SIVs suffered from significant liquidity and maturity mismatches, making them vulnerable to a classic bank run. Which of the following statement is NOT correct?
- A.There were misaligned incentives along the securitization chain, driven by the pursuit of short-term profits, banks had fewer incentives to conduct in-depth due diligence on borrowers.
- B.The risks embedded in securitized products were not transparent, investors had difficulty assessing the quality of the underlying assets and the potential correlations between them.
- C.There was poor securitization risk management, particularly regarding the identification, assessment, handling, and stress testing of market, liquidity, concentration, and pipeline risks.
- D.Rating agency provides accurate and transparent ratings of mortgage-backed securities.
91
Dummy variables, also known as binary variables, are used to reflect qualitative information in models. When considering deterministic seasonality, Sara decides to use four dummy variables to represent different seasons in a year. The regression model she intends to build is as follows: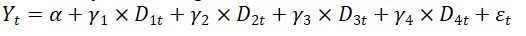 When running the regression on the computer, the computer suddenly crashes. Sara tries several times but still can’t get the result. Which of the following statements is most likely correct about the model?
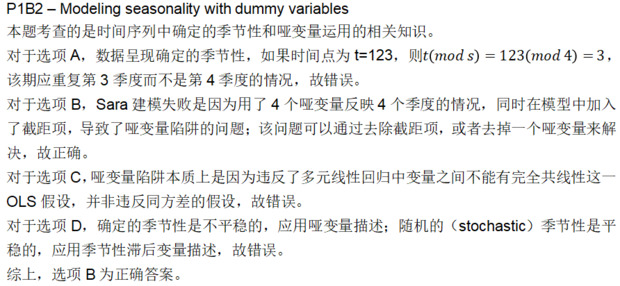
- A.The result of the 123rd period will repeat what is like in the fourth season.
- B.Sara’s failure is due to dummy variable trap, which could be avoided by omitting the intercept or one of the dummy variables.
- C.The model couldn’t operate since it violates one of OLS assumptions—homoskedasticity.
- D.Sara should have used seasonal lags rather than dummy variables to model the deterministic seasonality.
92
Jack, CRO, working in Hello World Bank, attends a global financial risk management summit and learns other banks’ operational experience. At the summit, Jack knows a model called power law: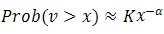 Which statement is correct about power law?
- A.The power law not only describes the right tail of a distribution but also the whole distribution.
- B.The parameter α reflects the fatness of a distribution’s right tail. And as the parameterα decreases, this tail becomes thinner.
- C.The parameter K is a scale parameter. And as the parameter K increases, this tail becomes thinner.
- D.Power law is a cumulative probability distribution function that indicates the cumulative probability when a random variable v goes larger than an extreme value x, like in the top 5% of the distribution.
93
Jeffrey works in the market risk department of Duck Bank and he knows risk indicators like value at risk (VaR) and expected shortfall (ES) are widely used in banks. VaR and ES are based on the loss distribution. A few months later, He transfers to another apartment to conduct stress testing. He compares Stress Testing versus VaR and ES. Which statement he makes is correct?
- A.Like stress testing, one disadvantage of VaR and ES is that they are usually backward-looking.
- B.VaR and ES focus on a wide range of scenarios while stress testing concentrates on a small number of scenarios that are all bad for an organization.
- C.In terms of market risk, both the VaR\/ES approach and stress testing often consider a short time horizon.
- D.The VaR and ES indicators are measured by the data gathered from particularly stressful periods.
94
Tonny is a newcomer in the operational risk management apartment of Red Rever Bank. His supervisor Peter assigns him to categorize the operational risk collected from news according to the seven categories identified by the Basel Committee. Which operational risk is correctly categorized?
- A.China Daily reports that over a decade, one teller who worked in ABC bank pocketed more than \uffe52,000 illicit income by depositing customers' changes in an account he could control. Tonny categorizes this event as clients, products, and business practices.
- B.The Paper reports that China Construction Bank's business system crashed for about 20 minutes on 15th July morning and that it was the telecommunication problems. Tonny categorizes it as execution, delivery, and process management.
- C.People's Daily reports that the floods in Henan destroyed many bank branches and caused losses of about 10 million yuan. Tonny categorizes it as employment practices and workplace safety.
- D.Qilu Evening News reports that according to the preliminary investigation by Jinan Public Security Bureau, the criminal suspect Liu defrauded Qilu Bank of up to 6 billion yuan by forging financial certificates. Tonny categorizes it as external fraud.
95
Enron's bankruptcy in 2001 was the largest corporate bankruptcy in the US when it occurred. Each of the following is true about the Enron case study EXCEPT which is false?
- A.Enron was a poster child of corporate governance failure and poor risk management.
- B.Enron used fraudulent accounting practices to hide actual financial losses.
- C.Enron's chief problem was the basis risk realized when its hedges against electricity prices collapsed due to unexpected price volatility.
- D.Enron outsourced its audit function to Arthur Anderson who explicitly approved, or failed to capture, several of its fraudulent accounting practices.
96
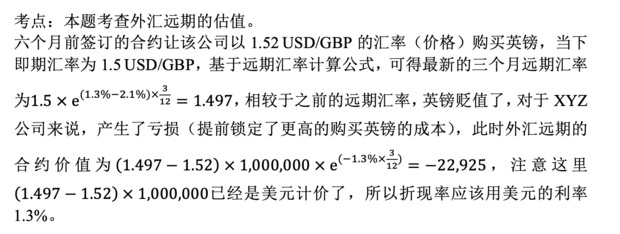
Corporation XYZ entered into a nine-month forward contract six months ago which obligates it to buy GBP 1,000,000 for USD 1,520,000. Today, the spot exchange rate is 1.5 USD/GBP. And the three-month US interest rate is 1.3%, while the three-month UK interest rate is 2.1%. What is the value of this forward contract? (with continuous compounding)
- A.USD 20,000
- B.USD -20,000
- C.USD 22,925
- D.USD -22,925
97
Many different type of swaps exist. Examples of swaps include: interest rate swaps, currency swaps, commodity swaps, equity swaps, and volatility swaps. A swaption is an option which gives the holder the right to enter into a swap. Which of the following statements about swaps and swaptions is most likely correct?
- A.Equity swap payments may be floating on both sides.
- B.Unlike options, premiums for swaptions are not dependent on the strike rate specified in the swaption.
- C.The most common reason for entering into commodity swap agreements is to speculate on commodities prices.
- D.For the fixed-rate payer in an S&P500 Index swap, a negative index return does not require a payment from the fixed-rate payer.
98
Risk-adjusted return on capital (RAROC) is commonly used in financial analysis to balance reward and risk, which of the following description is NOT an advantage of RAROC?
- A.RAROC is a modified return on investment that takes elements of risk into account.
- B.RAROC allows firms to compare the performance of business lines that require a different amount of risk capital.
- C.The denominator of RAROC is the capital adjusted for risk which satisfies the regulatory requirement, thus, RAROC can be used as a regulatory tool.
- D.RAROC can be used as an investment analysis tool, by determining if a project provides a return above a hurdle rate demanded by the shareholders.
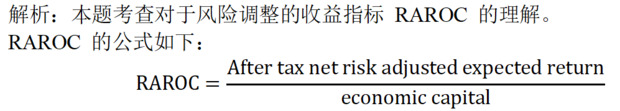 选项 A,RAROC是一种考虑了风险因素后的修正的投资回报率。选项 A 表述正确,不符合题意。选项 B,RAROC允许公司比较需要不同风险资本的业务线的绩效,这是因为不同业务线承担的风险大小不同,所需的经济资本也不同,RAROC 可以得出各个业务条线每花费一单位经济资本所获得的的收益是多少,具备可比性。选项 B表述正确,不符合题意。选项C,RAROC其分母是经济资本而非监管资本,经济资本是银行站在自己业务发展和风险管理角度测算出的资本金水平,而不是为了满足监管要求而设置的资本金水平,因此,经济资本和监管资本在数值上可能相差巨大。选项 C 表述错误,符合题意,故本题选 C。选项 D,RAROC可作为一种投资分析工具,通过确定项目的 RAROC是否高于股东要求的最低回报率。选项 D 表述正确,不符合题意。
99
As a junior analyst in GS Investment Fund, Tom is learning about pricing orders in the futures market recently. He gives the following four statements.Statements 1: In a discretionary order, the customer can delay filling in hopes of getting a better price.Statements 2: Limit order can only be executed at the specified price or a price move favorable to the trader.Statements 3: Stop-loss order is the order that becomes a market order once the asset reaches a specified or a less favorable price.Statements 4: Market-if-touched (MIT) order is an order that becomes a market order if a trade occurs at the specified price a more favorable price.How many statement( ) above are correct?
- A.1
- B.2
- C.3
- D.4
100
Emily Ho is a risk analyst at Golden Investment Group. She needs to implement asimulation on the expected return of S&P 500 for the next year. She collects historical data of returns on S&P 500 from 2015 to 2020. Emily has two options to run the simulation, which are Monte Carlo Simulation and Bootstrapping. She makes the following statements about those two methods:Statement I: The COIVD-19 has negatively influenced the stock returns on S&P 500 in early 2020. Therefore, Bootstrapping gives a better prediction than Monte Carlo Simulation if we use the historical data from 2015 to 2020.Statement II: For running both Bootstrapping and Monte Carlo Simulation, we need to make assumptions regarding the distribution of returns.Which of those statement( ) is(are) most likely correct?
- A.Only Statement I
- B.Only Statement II
- C.Both statements
- D.Neither statement is correct
输入阅读码
查看答案与解析需要输入阅读码